
 (800) 949-0401
Commercial Smokehouse Equipment Financing: The Complete Guide for Meat Processing Business Owners
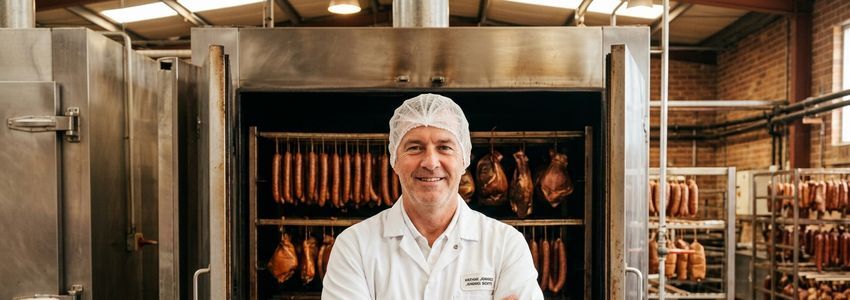
Commercial smokehouse equipment financing gives meat processors, butcher shops, barbecue restaurants, and specialty food producers a way to acquire industrial smokers, curing chambers, and processing lines without draining cash reserves. Whether you are outfitting a new smokehouse from scratch or replacing an aging unit that can no longer keep pace with demand, understanding how this financing works can mean the difference between a costly cash purchase and a manageable monthly payment that keeps your production line running.
This guide breaks down everything a business owner needs to know about commercial smokehouse equipment financing: what it is, how it works, the types of equipment it covers, who qualifies, and how it compares to other funding options. We will also walk through real-world scenarios and answer the 15 most common questions meat processing and food production business owners ask before applying.
In This Article
What Is Commercial Smokehouse Equipment Financing?
Commercial smokehouse equipment financing is a type of business loan or equipment lease specifically structured to help meat processors, butcher shops, barbecue operations, and specialty food producers purchase industrial smoking, curing, and processing equipment. Instead of paying the full purchase price upfront, a business spreads the cost across fixed monthly payments over a term that typically ranges from two to seven years.
This type of financing covers a wide range of equipment, from single-unit commercial smokers used by a growing barbecue restaurant to full industrial smokehouse lines used by USDA-inspected meat processing facilities. Lenders that specialize in equipment financing, like Crestmont Capital, structure the loan around the equipment itself, which often makes approval faster and more flexible than a traditional bank loan.
Because smokehouse and meat processing equipment is capital-intensive, ranging from a few thousand dollars for a small commercial unit to hundreds of thousands of dollars for an automated industrial smokehouse system, financing is often the only realistic path for small and mid-size operators to access the equipment they need to grow.
The economics of smokehouse ownership have shifted in recent years as demand for smoked, cured, and artisanal meat products has grown steadily across restaurant, retail, and grocery channels. Consumers increasingly seek out house-smoked bacon, craft sausage, and small-batch charcuterie, which pushes many operators to upgrade from a single countertop or backyard-style unit to a production-grade smokehouse capable of consistent, repeatable batches. That transition almost always requires outside financing, since few operators keep six-figure cash reserves earmarked purely for equipment upgrades.
Equipment financing also differs meaningfully from a general-purpose business loan. Because the smokehouse, curing chamber, or processing line itself typically secures the financing, lenders can often extend more favorable terms than they would for an unsecured loan of the same size. This is one of the main reasons meat processors and specialty food producers gravitate toward equipment-specific financing rather than trying to fund a major equipment purchase out of a general working capital facility.
Ready to Upgrade Your Smokehouse?
Get fast, flexible equipment financing from the #1 business lender in the U.S. No obligation, apply in minutes.
Apply Now →Key Benefits of Financing Smokehouse Equipment
Financing industrial smoking and meat processing equipment offers several advantages over paying cash, particularly for operators who want to preserve working capital for payroll, inventory, and day-to-day operations.
- Preserve cash flow. Instead of tying up tens of thousands of dollars in a single purchase, you spread the cost over predictable monthly payments.
- Faster approval than traditional bank loans. Because the equipment itself often serves as collateral, equipment financing can close in days rather than weeks.
- Access to newer, more efficient equipment. Modern smokehouses offer better temperature control, humidity management, and energy efficiency than older units, which can reduce spoilage and improve product consistency.
- Fixed monthly payments. Most equipment financing structures use a fixed rate, so you know exactly what you owe each month regardless of interest rate movement.
- Potential tax advantages. Many businesses structure equipment purchases to take advantage of depreciation schedules, though you should always consult a qualified tax professional for guidance specific to your business.
- Options for new and used equipment. Financing is available for both brand-new industrial smokehouses and certified used equipment, which can lower the total cost of the purchase.
Key Stat: According to the U.S. Census Bureau's Annual Survey of Manufactures, the animal slaughtering and processing sector is one of the largest food manufacturing subsectors in the country, representing tens of billions of dollars in annual shipments and supporting hundreds of thousands of jobs nationwide.
How Commercial Smokehouse Equipment Financing Works
The process of financing a commercial smokehouse or meat processing line follows a fairly consistent structure across most equipment lenders, though the specifics can vary based on the size of the equipment purchase and the lender you choose.
Step 1: Identify the equipment and get a quote. Before applying, get a written quote from your equipment vendor or manufacturer that specifies the make, model, and total cost of the smokehouse, smoker, or processing line you intend to purchase.
Step 2: Submit a financing application. Most equipment lenders require basic business information, time in business, and recent bank statements. Many equipment financing applications can be completed online in minutes.
Step 3: Underwriting and approval. The lender reviews your business's financial health, the value of the equipment, and your ability to repay. Because the equipment secures the financing, approval decisions are often faster than unsecured loan products.
Step 4: Funding and equipment delivery. Once approved, funds are typically sent directly to the equipment vendor, or in some cases reimbursed to your business if you have already made a purchase. Your smokehouse or processing equipment is then delivered and installed.
Step 5: Repayment. You make fixed monthly payments over the agreed term, typically two to seven years depending on the equipment's useful life and the size of the financing.
By the Numbers
Meat Processing and Food Manufacturing Equipment Financing
2-7 Yrs
Typical financing term for industrial smokehouse equipment
24-48 Hrs
Typical approval turnaround for equipment financing applications
33M+
Small businesses operating in the U.S., per the SBA
80-100%
Typical financeable portion of equipment cost, including install
Types of Smokehouse Equipment You Can Finance
Commercial smokehouse equipment financing is not limited to a single piece of machinery. Most equipment lenders, including Crestmont Capital, finance a wide range of equipment used across the meat processing and specialty food production industry.
- Industrial smokehouses. Large-batch smoking chambers used by USDA-inspected meat processors, often with programmable temperature, humidity, and smoke density controls.
- Commercial smokers. Standalone units used by barbecue restaurants, catering operations, and smaller processing facilities for daily production.
- Curing and drying chambers. Equipment used for dry-curing sausages, hams, and charcuterie products that require controlled humidity and airflow over extended periods.
- Sausage stuffers and linkers. Processing equipment used alongside smokehouses to prepare product before smoking.
- Blast chillers and cooling tunnels. Equipment used to rapidly cool smoked product to safe holding temperatures after processing.
- Packaging and vacuum sealing equipment. Machinery used to package finished smoked and cured products for retail or wholesale distribution.
- Refrigeration and cold storage. Walk-in coolers and freezers used to store raw materials and finished product.
- Wood chip and pellet delivery systems. Automated smoke generation systems used in larger industrial operations.
Financing is generally available for both new equipment purchased directly from a manufacturer and certified used or refurbished equipment purchased from a dealer, which can significantly reduce upfront cost for growing operations.
Beyond the smokehouse itself, most equipment financing programs also allow ancillary equipment to be bundled into the same application. A processor installing a new industrial smokehouse, for example, may also need upgraded ventilation and smoke exhaust systems, additional electrical capacity, floor drains rated for wet processing environments, and stainless steel prep tables to handle the increased product volume. Rolling these ancillary costs into a single financed package, rather than paying for them separately out of pocket, keeps the project cash-flow neutral from day one.
It is also worth noting that many smokehouse and processing equipment purchases qualify for financing structures where monthly payments are timed to begin once the equipment is installed and operational, rather than the day the financing is approved. This alignment between when payments start and when the equipment begins generating revenue is one of the most valuable, and most overlooked, features of a well-structured equipment financing agreement.
Who Smokehouse Equipment Financing Is Best For
Commercial smokehouse equipment financing is best suited for a specific set of business owners who need reliable, production-grade smoking and curing equipment but do not want to deplete cash reserves to acquire it.
- Meat processors and USDA-inspected facilities expanding production capacity or replacing aging equipment.
- Butcher shops and specialty meat markets adding in-house smoking and curing capabilities to differentiate their product line.
- Barbecue restaurants and catering businesses scaling up from a single smoker to a larger production setup to meet growing demand.
- Charcuterie and artisan food producers investing in curing chambers to expand into new product lines.
- Sausage and deli meat manufacturers needing integrated processing, smoking, and packaging lines.
- Co-packers and contract processors that smoke and cure product on behalf of other food brands.
Comparing Smokehouse Equipment Financing to Other Options
Business owners considering how to fund a new smokehouse or processing line typically weigh equipment financing against a few alternatives. Here is how they compare.
| Financing Option | Best For | Speed | Collateral |
|---|---|---|---|
| Equipment Financing | Purchasing specific smokehouse or processing equipment | Fast (often 1-3 days) | The equipment itself |
| SBA Loan | Larger facility buildouts or expansions | Slower (weeks to months) | Often required, broader collateral |
| Business Line of Credit | Ongoing working capital needs, not large one-time purchases | Fast once established | Varies, often unsecured |
| Cash Purchase | Businesses with significant reserve capital | Immediate | None, but ties up cash |
For most meat processors and food producers, equipment financing strikes the best balance between speed, preserving cash flow, and matching the payment schedule to the useful life of the equipment.
It is worth noting that these options are not always mutually exclusive. Many established processors use a business line of credit for day-to-day fluctuations in raw material costs while reserving equipment financing specifically for capital equipment purchases like a new smokehouse or curing chamber. Keeping these funding sources separate helps a business avoid using short-term credit to pay for long-term assets, which can strain cash flow if the equipment financing is not properly aligned with the equipment's useful life.
Some processors also explore leasing structures rather than a traditional equipment loan. A lease can lower monthly payments further in exchange for either returning the equipment at the end of the term or making a final buyout payment. This can make sense for operators who expect to upgrade equipment again in a few years as production volume grows, though most meat processors ultimately choose a financing structure that builds toward ownership since smokehouses and curing chambers tend to remain useful for many years with proper maintenance.
How Crestmont Capital Helps Finance Your Smokehouse Equipment
Crestmont Capital works with meat processors, butcher shops, and specialty food producers across the country to structure equipment financing that fits the realities of running a production business. Rather than a one-size-fits-all loan product, Crestmont evaluates the specific equipment, your business's cash flow, and your growth plans to structure a payment schedule that works.
For businesses that also need general kitchen or processing line upgrades alongside a new smokehouse, Crestmont's food equipment financing and commercial kitchen equipment financing programs can be combined into a single application, reducing paperwork and speeding up approval.
Businesses looking to reduce upfront cost can also explore Crestmont's used equipment financing program, which allows qualifying operators to finance certified pre-owned smokehouses and processing equipment at a lower total cost than buying new. And for processors who need working capital on top of equipment, Crestmont's unsecured working capital loans can supplement an equipment purchase to cover installation, staffing, or inventory needs during a facility upgrade.
If your business is also looking at broader meat processing equipment needs beyond the smokehouse itself, our guide to meat processing equipment financing covers cutting, grinding, and packaging equipment financing in more depth. Butcher shop owners specifically may also find our butcher shop equipment financing guide useful for retail-focused processing needs.
Pro Tip: When requesting quotes from equipment vendors, ask for the total installed cost, not just the equipment price. Financing that covers installation, electrical work, and ventilation modifications in a single payment is often easier to manage than paying for those items separately out of pocket.
Scale Your Smokehouse Operation
Whether you need one commercial smoker or a full industrial line, Crestmont Capital can structure financing that fits your production goals.
Apply Now →Real-World Scenarios
Scenario 1: The growing barbecue restaurant. A regional barbecue chain outgrows its single commercial smoker as catering orders increase. Rather than paying cash for a second, larger unit, the owner finances a commercial-grade rotisserie smoker over a four-year term, using the freed-up cash to hire additional kitchen staff for the catering division.
Scenario 2: The USDA-inspected processor expanding capacity. A small regional meat processor wins a new wholesale contract that requires doubling smoked product output. The business finances a full industrial smokehouse line, including a blast chiller and packaging equipment, structured over a six-year term to match the equipment's useful life and the length of the new contract.
Scenario 3: The charcuterie startup scaling production. An artisan charcuterie producer that started curing product in a small chamber needs a larger, humidity-controlled curing room to meet demand from regional grocery accounts. Equipment financing allows the business to install the new chamber without pulling capital from its ingredient and packaging budget.
Scenario 4: The butcher shop adding in-house smoking. A retail butcher shop wants to differentiate itself by offering house-smoked bacon and sausage. Financing a mid-size commercial smoker lets the shop add a new, higher-margin product line without a large upfront cash outlay, with the monthly payment covered by the incremental sales the new product generates.
Who Qualifies and How to Apply
Qualification requirements for commercial smokehouse equipment financing vary by lender, but most equipment financing companies look at a similar set of factors.
- Time in business. Many lenders can work with businesses that have been operating for one year or more, though established businesses generally receive better terms.
- Revenue and cash flow. Lenders want to see that your business generates enough consistent revenue to support the monthly payment.
- Credit history. Both business and personal credit may be reviewed, though equipment financing is often more flexible on credit than unsecured products because the equipment secures the loan.
- Equipment quote or invoice. A formal quote from your equipment vendor speeds up the underwriting process significantly.
- Bank statements. Recent business bank statements help the lender verify cash flow and average balances.
To apply, gather your equipment quote, recent bank statements, and basic business information, then submit an application online. Most equipment financing decisions are returned within one to two business days, with funding often available shortly after approval.
Businesses that plan ahead tend to get the best outcomes from the application process. Requesting your equipment quote at least a few weeks before you intend to install new equipment gives the lender time to review the purchase thoroughly, and it gives you room to compare financing terms across more than one lender if you choose to shop the offer. Rushing the process at the last minute, such as when an existing smokehouse fails unexpectedly, is still workable, but it limits your negotiating leverage and may narrow the field of lenders willing to move quickly enough to meet your timeline.
It also helps to have a clear picture of your expected return on the equipment before applying. Lenders are more comfortable extending favorable terms when a business can articulate how the new or upgraded smokehouse will directly increase revenue, whether through added production capacity, a new product line, or improved yield from reduced spoilage. Even a simple projection showing expected monthly production increase and the associated revenue can strengthen an application and may help secure a longer term or lower payment.
Start Your Smokehouse Financing Application
Get a fast decision on commercial smokehouse and meat processing equipment financing. No obligation.
Apply Now →Frequently Asked Questions
Next Steps
Request a written quote from your smokehouse or processing equipment vendor.
Pull recent bank statements and basic business financials together.
Apply online in minutes with Crestmont Capital for a fast financing decision.
Once approved, your equipment is ordered, delivered, and installed so production can begin.
Conclusion
Commercial smokehouse equipment financing gives meat processors, butcher shops, and specialty food producers a practical way to acquire the industrial smokers, curing chambers, and processing equipment they need without tying up working capital. Whether you are scaling from a single commercial smoker to a full production line or replacing outdated equipment with a modern, more efficient system, the right financing structure can make a significant equipment purchase manageable.
Crestmont Capital works with meat processing and food production businesses across the country to structure equipment financing around real production needs, not a one-size-fits-all template. If your business is ready to invest in new or upgraded smokehouse equipment, getting pre-qualified is a fast, no-obligation first step.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.








