
 (800) 949-0401
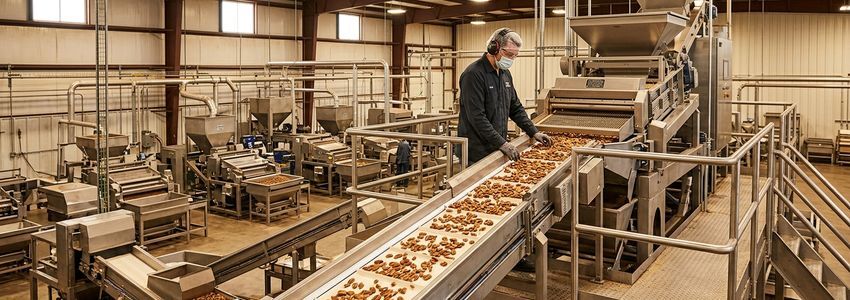
Commercial Pecan and Nut Processing Equipment Financing: The Complete Guide for Nut Processors
Nut processing equipment financing gives pecan, almond, walnut, and specialty nut processors a way to fund shellers, roasters, sorters, and packaging lines without draining working capital. Whether you run a family pecan operation in Georgia or a growing almond processing facility in California, the right equipment can be the difference between a bottleneck season and a record harvest year.
In This Article
What Is Nut Processing Equipment Financing?
Nut processing equipment financing is a funding solution that allows businesses in the tree nut and peanut processing industry to acquire shelling machines, cracking equipment, roasters, sorters, dryers, and packaging systems through structured payments rather than a single upfront purchase. Instead of paying $40,000 for a pecan cracker or $250,000 for a full sorting and grading line out of pocket, a processor can spread that cost over a term that matches the useful life of the machine.
This category of financing covers everything from small-batch operations processing a few hundred pounds a day to large commercial facilities running multiple shifts during peak harvest. Lenders typically structure these deals as either an equipment loan, where the business owns the asset from day one and builds equity with every payment, or an equipment lease, where the processor pays for the use of the machine and may have a purchase option at the end of the term.
Because nut processing equipment is specialized and often expensive to source new, financing also opens the door to purchasing well-maintained used equipment from equipment dealers or private sellers, which can significantly reduce the total cost of a processing line upgrade.
Unlike a general working capital loan, equipment financing is tied directly to a specific machine or production line. That connection matters because it changes how a lender evaluates risk. A pecan cracker or an optical sorter has resale value and a known useful life, so the equipment itself typically serves as collateral. This is one reason equipment financing can be more accessible for nut processors than an unsecured loan of a similar size, even for businesses with a thinner credit file or a shorter operating history.
The nut processing industry also has some unique financing considerations compared to other food manufacturing sectors. Harvest timing drives most of the revenue for pecan, walnut, and almond processors, which means equipment often needs to be installed and tested well before the busiest weeks of the year. Lenders who work regularly with agricultural and food processing businesses understand this seasonality and can structure financing around it, rather than forcing a processor into a standard flat monthly payment that ignores when the cash actually comes in.
Ready to Upgrade Your Processing Line?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation, apply in minutes.
Apply Now →Key Benefits of Financing Your Nut Processing Equipment
Nut processors operate on tight seasonal margins, and tying up cash in a single equipment purchase can leave a business exposed when unexpected costs hit mid-harvest. Financing spreads that cost out and keeps capital available for labor, raw material purchases, and storage.
- Preserve working capital - keep cash on hand for payroll during peak harvest season, raw nut purchases, and cold storage costs instead of locking it into one machine.
- Match payments to revenue - many nut processing businesses are seasonal, and some equipment financing structures allow seasonal or step-up payment plans that align with harvest income.
- Access newer technology faster - modern optical sorters and moisture-controlled roasters improve yield and reduce waste, and financing makes it possible to adopt them without a large capital outlay.
- Predictable monthly costs - fixed payment schedules make budgeting for the next harvest cycle far easier than trying to forecast a large lump-sum equipment purchase.
- Potential tax benefits - depending on how the financing is structured, payments and depreciation may offer tax advantages. Always confirm specifics with your accountant.
- Build business credit - consistent on-time payments on equipment financing help establish a stronger credit profile for future growth financing.
- Flexibility to scale - financing makes it easier to add a second processing line or expand capacity ahead of demand rather than waiting years to save up cash.
- Reduced downtime risk - financing a backup or replacement machine before an aging one fails outright can prevent a costly production stoppage during peak harvest weeks.
- Room to negotiate better supplier terms - once a piece of financed equipment is generating additional throughput, processors often have more leverage to negotiate better pricing with growers or buyers because they can handle larger volumes reliably.
Beyond the immediate cash flow advantages, financing equipment rather than paying cash also protects a nut processing business against the opportunity cost of tying up capital in a single asset. A pecan sheller or almond sorter does not generate returns sitting in a bank account; it generates returns when it is running. Financing lets the equipment start producing revenue immediately while the payments are spread across the months and years the machine is actually earning its keep.
Key Stat: The U.S. Census Bureau reports that the vast majority of American food manufacturers, including nut and specialty food processors, are small businesses employing fewer than 100 people, meaning access to capital for equipment upgrades is a critical growth lever for this industry.
How Nut Processing Equipment Financing Works
The process of financing nut processing equipment follows a fairly predictable path, though the exact steps can vary slightly by lender and equipment type.
- Identify the equipment. Get a quote from an equipment dealer or manufacturer for the sheller, cracker, roaster, sorter, dryer, or packaging line you need.
- Submit an application. Provide basic business information, the equipment quote, and financial documentation such as bank statements and tax returns.
- Underwriting review. The lender evaluates your business's time in operation, revenue, credit profile, and the value of the equipment being financed.
- Approval and terms. You receive approval with a specific rate, term length, and monthly payment amount, along with any down payment requirement.
- Funding. Once you accept the terms, funds are sent directly to the equipment vendor or seller, or in some cases directly to your business account for equipment you have already sourced.
- Equipment delivery and installation. Your new or used processing equipment is delivered and installed, and you begin making scheduled payments.
Most equipment financing applications for established nut processing businesses can be approved within a few business days, and funding can often be completed within a week, which matters when harvest timing is tight.
Types of Nut Processing Equipment You Can Finance
Nut processing covers a wide range of equipment depending on the nut variety and the stage of production. Common equipment categories that qualify for financing include:
- Shelling and cracking equipment - pecan crackers, walnut crackers, almond hullers, and in-shell separators designed for specific nut sizes and shell hardness.
- Sorting and grading machines - optical color sorters, size graders, and gravity separators that remove shell fragments, foreign material, and off-grade product.
- Roasting equipment - dry roasters, oil roasters, and continuous roasting lines used for peanuts, cashews, almonds, and pecans.
- Drying and moisture control systems - industrial dryers that bring harvested nuts to safe storage moisture levels before shelling or roasting.
- Blanching and skin removal equipment - used primarily for almonds and peanuts to remove skins prior to packaging or further processing.
- Packaging and bagging lines - vertical form-fill-seal machines, vacuum sealers, and nitrogen flush packaging systems that extend shelf life.
- Storage and material handling - bulk storage bins, conveyor systems, elevators, and forklifts used to move product through the facility.
- Quality control and testing equipment - aflatoxin testing systems, metal detectors, and X-ray inspection machines required for food safety compliance.
Financing is not limited to brand-new equipment. Many lenders, including Crestmont Capital's manufacturing equipment financing programs, will finance well-maintained used equipment from a reputable dealer, which can be a smart way to add capacity at a lower cost.
Quick Guide
How Nut Processing Equipment Financing Works, At a Glance
Source pricing from your equipment dealer for the sheller, roaster, or sorter you need.
Provide basic financials and business details for underwriting review.
Receive your rate, term, and monthly payment, often within days.
Funds go to your vendor, equipment is delivered, and you start processing.
Who This Financing Is Best For
Nut processing equipment financing tends to make the most sense for a specific set of business situations:
- Growing nut processors who have outgrown their current shelling or sorting capacity and need to add a second line or larger equipment.
- Seasonal harvest operations such as pecan farms and processors that need equipment ready well before harvest but generate most of their revenue after the crop comes in.
- Co-ops and family processing operations that want to modernize aging equipment without taking on a large lump-sum expense.
- Contract processors who process nuts on behalf of growers or brands and need reliable, higher-throughput equipment to take on more contracts.
- Specialty and organic nut processors who need dedicated equipment lines to maintain certification standards and avoid cross-contamination with conventional product.
- New entrants to nut processing who are moving from raw agricultural sales into value-added processing and packaging.
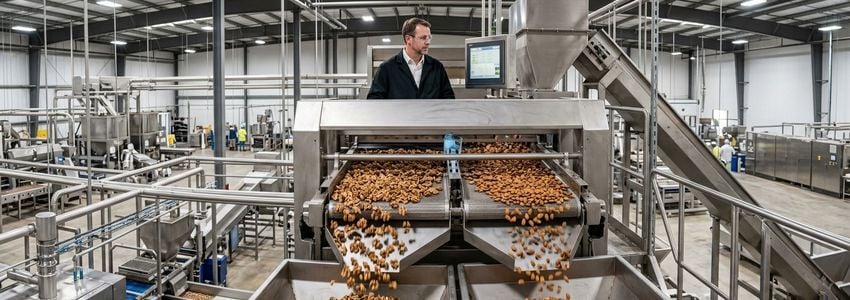
Financing Options Compared
Nut processors typically have several financing paths available. Choosing the right one depends on your credit profile, how quickly you need funding, and whether you plan to own or eventually upgrade the equipment.
| Option | Best For | Ownership | Typical Term |
|---|---|---|---|
| Equipment Loan | Processors who want to build equity in the machine | Own from day one | 2 to 7 years |
| Equipment Lease | Processors who want lower monthly payments or plan to upgrade often | Optional purchase at end of term | 2 to 5 years |
| SBA 7(a) Loan | Larger facility upgrades with longer payback needs | Own from day one | Up to 10 years for equipment |
| Business Line of Credit | Smaller equipment purchases or repair needs mid-season | Own from day one | Revolving, draw as needed |
For larger equipment purchases with a longer useful life, such as a full sorting and packaging line, an SBA loan or a term equipment loan often makes the most financial sense. For smaller, more urgent needs, such as replacing a failed conveyor mid-harvest, a business line of credit can provide faster access to funds.
How Crestmont Capital Helps Nut Processors
Crestmont Capital works with nut processors, food manufacturers, and agricultural businesses across the country to structure financing that fits seasonal cash flow patterns. Rather than a one-size-fits-all loan product, Crestmont looks at your harvest cycle, revenue timing, and equipment needs to build a payment structure that works for your business.
Our manufacturing equipment financing programs cover shellers, roasters, sorters, and packaging lines, while our agricultural equipment financing options extend to the farm and harvest-side equipment many nut processors also rely on, from drying equipment to material handling. For processors who prefer to lease rather than buy outright, our equipment leasing programs offer lower monthly payments with the flexibility to upgrade equipment as your business grows.
We have also worked with related food processing businesses on equipment upgrades. If you want to see how similar businesses have approached financing, our guide on food processing equipment financing covers many of the same principles that apply to nut processing lines, and our coffee roasting equipment financing guide walks through how another specialty food processor approached a similar roasting equipment upgrade.
Ready to Expand Your Processing Capacity?
Crestmont Capital structures equipment financing around your harvest cycle, not a generic monthly schedule. Apply in minutes.
Get Started →Real-World Scenarios
Scenario 1: The Family Pecan Operation Adding a Second Sheller
A third-generation pecan processing operation in Georgia was running a single shelling line that could not keep up with a growing number of grower contracts. Rather than waiting until they had saved enough cash, they financed a second commercial pecan cracker and matching sorter, structured with lower payments during the off-season and higher payments during the fall harvest window.
Scenario 2: An Almond Processor Upgrading to Optical Sorting
A mid-size almond processing facility in California was losing product value due to manual sorting errors that let shell fragments and off-color nuts through to premium-grade lots. They financed an optical color sorter, which paid for itself within two seasons through improved grade yield and fewer customer rejections.
Scenario 3: A Contract Roaster Expanding Capacity
A contract roasting business that processes cashews and peanuts for several regional snack brands needed a second continuous roasting line to take on a new client contract. Equipment financing allowed them to add the line and fulfill the new contract without depleting the cash reserves they needed for ingredient purchases.
Scenario 4: A Walnut Huller Replacing Aging Equipment
A walnut processor with equipment nearing the end of its service life faced increasing downtime and repair costs during peak season. Financing a replacement huller and dryer system reduced unplanned downtime and let the business avoid a costly mid-harvest equipment failure the following year.
Scenario 5: A New Specialty Nut Brand Building Its First Processing Line
An entrepreneur launching a specialty flavored nut brand needed roasting, seasoning, and packaging equipment to move from co-packing to in-house production. Financing the full line let the business control quality and margins earlier than expected, without raising outside equity to fund the equipment.
Scenario 6: A Peanut Processor Adding Aflatoxin Testing Equipment
A peanut processing facility supplying commercial food manufacturers needed to add in-house aflatoxin testing capability to meet new buyer requirements. Financing the testing and inspection equipment allowed the business to retain existing contracts and pursue new buyers who required documented food safety testing on every shipment.
Pro Tip: If your nut processing business is seasonal, ask about seasonal or step-up payment structures. Many equipment lenders can align lower payments with your off-season and higher payments with harvest revenue instead of forcing a flat payment year-round.
Cost Considerations for Nut Processing Equipment Financing
Understanding the true cost of financing helps a processor compare offers accurately rather than focusing on monthly payment alone. Several factors typically drive the total cost of a financing arrangement.
- Equipment cost and age. New equipment generally qualifies for longer terms and better rates than used equipment, though used equipment can still be a smart choice for cost-conscious processors.
- Term length. A longer term lowers the monthly payment but increases total interest paid over the life of the financing. Matching the term to the expected useful life of the equipment is usually the best approach.
- Down payment. Putting money down can reduce monthly payments and may improve approval odds, though many equipment financing programs require little to no down payment for qualified borrowers.
- Business credit profile. Time in business, revenue trends, and credit history all influence the rate offered. Processors with several years of consistent harvest revenue typically see more competitive terms.
- Seasonal structuring. Custom payment schedules that align with harvest revenue may carry a slightly different rate structure than a standard flat monthly payment, so it is worth comparing both options directly.
Before signing any financing agreement, ask about prepayment terms as well. Some equipment financing structures allow early payoff without penalty, which can save money if a strong harvest season allows a processor to pay down the balance faster than planned.
Common Mistakes Nut Processors Make When Financing Equipment
A few recurring mistakes can cost nut processors money or slow down their equipment financing approval. Being aware of them ahead of time makes the process smoother.
- Waiting too long to apply. Starting the financing process only weeks before harvest can limit lender options and rush the decision. Applying several months ahead gives more time to compare offers and get equipment installed and tested.
- Underestimating total capacity needs. Financing equipment sized for current volume rather than projected growth often leads to another financing conversation within a year or two. It is usually worth financing slightly ahead of current needs if growth is realistic.
- Choosing the lowest payment without checking total cost. A longer term with a lower monthly payment can end up costing significantly more in total interest, especially on higher-priced equipment like a full sorting line.
- Not comparing lease versus loan structures. Processors sometimes default to whichever option a dealer offers on-site rather than comparing a lease against a loan from an independent lender, which can mean missing out on better terms.
- Skipping the seasonal payment conversation. Many processors do not realize seasonal or step-up payment structures are available and end up with a standard flat payment that strains cash flow during the off-season.
Frequently Asked Questions
Next Steps
Reach out to your equipment dealer for pricing on the sheller, sorter, roaster, or line you need.
Submit a short application to see your financing options based on your equipment need and business profile.
Compare rate, term, and payment structure, including whether a seasonal schedule fits your business.
Once approved, your equipment is delivered and installed so you can get back to processing.
Don't Let Outdated Equipment Slow Down Your Harvest
See what you qualify for with the #1 rated business lender in the U.S. Apply in minutes, no obligation.
Apply Now →Conclusion
Nut processing equipment financing lets pecan, almond, walnut, and specialty nut processors upgrade shelling, sorting, roasting, and packaging equipment without draining the cash reserves they need for raw material purchases and payroll. With flexible loan and lease structures, including seasonal payment options built around harvest timing, financing can help a growing processing business add capacity exactly when it is needed. Crestmont Capital works with food and agricultural processors nationwide to structure financing that fits the realities of a seasonal business, from a single replacement sorter to a full new processing line.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.








