
 (800) 949-0401
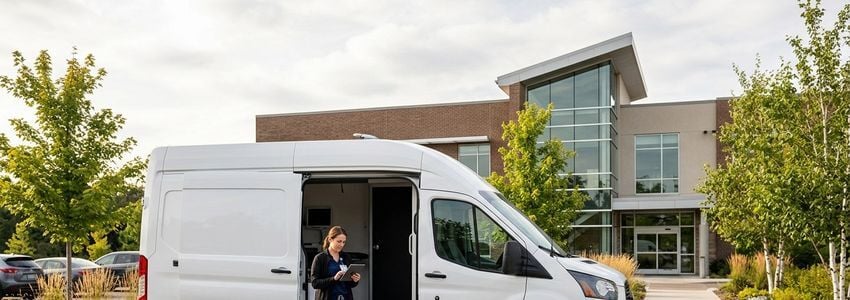
Mobile Medical Imaging Van Financing: The Complete Guide for Business Owners
Mobile medical imaging van financing gives diagnostic imaging entrepreneurs a practical path to launching or expanding a fleet of mobile X-ray, ultrasound, MRI, or CT units without draining working capital. Whether you are outfitting your first vehicle or scaling a regional route serving hospitals, nursing homes, and rural clinics, the right financing structure determines how quickly you can deploy equipment and start generating revenue.
Mobile imaging is one of the fastest-growing niches in healthcare services. Hospitals are outsourcing overflow imaging needs, skilled nursing facilities want on-site diagnostics instead of costly patient transports, and rural communities losing their local hospitals are turning to mobile providers to fill the gap. For entrepreneurs positioned to serve this demand, the barrier is rarely the market opportunity. It is the six-figure to seven-figure price tag attached to a properly equipped imaging vehicle.
This guide walks through every financing option available to mobile imaging business owners, how lenders evaluate these deals, what to expect during underwriting, and how to build a financing package that gets approved quickly.
In This Article
- What Is Mobile Medical Imaging Van Financing?
- Key Benefits of Financing a Mobile Imaging Van
- How Mobile Imaging Van Financing Works
- Types of Financing Available
- Who This Financing Is Best For
- Comparing Your Financing Options
- How Crestmont Capital Helps
- Real-World Scenarios
- What Lenders Look For
- The Application Process
- FAQ
- Next Steps
What Is Mobile Medical Imaging Van Financing?
Mobile medical imaging van financing refers to the loans, leases, and equipment finance agreements used to purchase or lease a specialized vehicle equipped with diagnostic imaging technology. This includes fully outfitted mobile X-ray units, portable ultrasound vans, mobile CT scanner trailers, and in some markets mobile MRI coaches. The financing typically covers both the vehicle chassis or trailer shell and the imaging equipment installed inside it, since the two are usually purchased and delivered as a single turnkey package from a specialty upfitter.
Unlike financing a standard commercial vehicle, mobile imaging van financing has to account for the fact that the imaging equipment itself, not the vehicle, represents the majority of the total cost. A base cutaway van or trailer chassis might run $60,000 to $90,000, while the imaging modality, shielding, power system, and climate control can add anywhere from $150,000 to well over $1 million depending on whether the unit houses a portable X-ray system or a full mobile MRI suite. Lenders who specialize in medical and diagnostic equipment understand this cost breakdown and structure financing accordingly.
Because these vehicles combine transportation equipment with sensitive diagnostic technology, financing packages often blend elements of equipment financing, commercial vehicle financing, and in some cases SBA-backed lending for larger fleet purchases. Understanding which structure fits your situation is the first step toward getting funded on workable terms.
Key Benefits of Financing a Mobile Imaging Van
Financing rather than paying cash for a mobile imaging vehicle preserves capital for the parts of the business that are harder to fund later, such as staffing, marketing to referral partners, and building a service contract pipeline with hospitals and long-term care facilities. Small-ticket equipment financing deals were up 6.2% year-over-year in 2025, according to Forbes Finance Council, showing strong momentum for businesses financing equipment purchases under $250,000.
- Preserve working capital. A single mobile imaging unit can cost as much as a small commercial building. Financing spreads that cost over the useful life of the asset instead of tying up cash reserves on day one.
- Match payments to revenue. Structured correctly, monthly payments can be timed to align with when service contracts and per-scan billing start generating cash flow, rather than requiring a lump sum before the van generates a single dollar.
- Access newer technology sooner. Leasing structures in particular make it easier to upgrade imaging modalities as technology improves, rather than being locked into equipment that becomes outdated mid-loan.
- Potential tax advantages. Certain equipment financing structures allow businesses to deduct financed equipment costs, though owners should always confirm current-year specifics with a qualified tax professional.
- Build business credit. Consistent, on-time payments on a properly structured equipment loan help establish a payment history that supports easier approval on future fleet expansion.
- Faster deployment. Approved financing can move a mobile imaging van from purchase order to revenue-generating service in weeks rather than the months it can take to save enough cash to buy outright.
How Mobile Imaging Van Financing Works
The mechanics of financing a mobile imaging vehicle generally follow the same core structure as other large equipment purchases, with a few industry-specific wrinkles related to how the vehicle and imaging technology are bundled.
- Get a quote from your upfitter or manufacturer. Most mobile imaging vans are built by specialty manufacturers who combine the chassis, shielding, and imaging modality into one purchase order. This quote becomes the basis for your financing request.
- Apply with supporting financials. Lenders will want to see business bank statements, tax returns, a copy of any signed service contracts or letters of intent from hospitals or facilities, and your personal credit profile.
- Underwriting review. The lender evaluates the collateral value of the vehicle and imaging equipment, your industry experience, and projected cash flow from imaging service revenue.
- Structure and terms. Once approved, you and the lender agree on term length (commonly 5 to 7 years for imaging equipment), down payment (often 0% to 20% depending on credit strength), and payment schedule.
- Funding and delivery. Funds are typically disbursed directly to the manufacturer or upfitter, sometimes in stages tied to build milestones for custom-built units.
- Deployment and service. Once delivered, the van goes into service and payments begin, ideally timed to coincide with your first billable imaging contracts.
Ready to Put a Mobile Imaging Van on the Road?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation. Apply in minutes.
Apply Now →Types of Financing Available for Mobile Imaging Businesses
There is no single "correct" way to finance a mobile imaging van. The right structure depends on your credit profile, how established your business is, and how much of the purchase you want financed versus paid up front.
Equipment Financing
Equipment financing is the most common route for mobile imaging vans because the vehicle and imaging technology together qualify as business equipment collateral. Terms typically run 5 to 7 years, matching the useful life of the imaging modality, with the equipment itself securing the loan. This keeps rates more competitive than unsecured options because the lender has collateral to fall back on.
Equipment Leasing
Leasing structures, including both fair market value leases and $1 buyout leases, let operators get into a mobile imaging unit with lower upfront cash outlay. This can be attractive for newer operators who want to preserve cash for staffing and marketing while they build a referral network, with the option to upgrade equipment at the end of the lease term as imaging technology evolves.
SBA 7(a) and 504 Loans
For larger fleet purchases or businesses combining a mobile imaging van with a fixed diagnostic facility, SBA loans can offer longer repayment terms and competitive rates. According to the U.S. Small Business Administration, the 504 program in particular is designed for major fixed-asset purchases, while the 7(a) program offers flexibility for combining equipment purchase with working capital needs.
Working Capital Loans
Once a mobile imaging van is in service, many operators use a working capital loan to bridge the gap between delivering scans and collecting reimbursement from insurers or facility contracts, which can take 30 to 90 days to settle.
Business Line of Credit
A revolving business line of credit gives mobile imaging operators a flexible cushion for fuel, maintenance, insurance renewals, and staffing costs that fluctuate month to month, separate from the equipment loan itself.
By the Numbers
Mobile Medical Imaging: Key Market Statistics
$3.67B
U.S. mobile MRI services market size (2024)
700+
Rural hospitals currently at risk of closing
2,000+
Mobile clinics currently operating nationwide
6.3%
Projected 2025 growth in equipment and software investment
Who This Financing Is Best For
Mobile medical imaging van financing serves a range of operators, from solo entrepreneurs launching a single-vehicle service to established diagnostic imaging companies expanding a multi-van fleet.
- Independent radiology and imaging entrepreneurs launching a mobile X-ray or ultrasound service to contract with nursing homes, assisted living facilities, and home health agencies.
- Existing imaging centers adding a mobile unit to extend their service area without building a second brick-and-mortar location.
- Hospital systems and health networks outsourcing overflow imaging capacity or serving satellite rural communities where a fixed facility is not economically viable.
- Veterinary and specialty imaging providers who need a similar mobile diagnostic platform for animal health or specialty screenings, such as mobile mammography programs.
- Correctional and forensic imaging contractors providing diagnostic services under government or institutional contracts that require on-site imaging capability.
Key Stat: Rural hospital closures have accelerated in recent years, with more than 100 rural hospitals shutting down over the past decade and hundreds more identified as financially at risk, according to reporting from the Associated Press. Mobile imaging providers are increasingly filling the diagnostic gap left behind.
Comparing Your Financing Options
Choosing between equipment financing, leasing, and SBA lending comes down to how much you want to put down, how quickly you want to build equity in the equipment, and how important flexibility to upgrade technology is to your business model.
| Option | Typical Term | Down Payment | Best For |
|---|---|---|---|
| Equipment Financing | 5-7 years | 0-20% | Owning the van outright long term |
| Equipment Leasing | 3-5 years | Low to none | Preserving cash, upgrading tech regularly |
| SBA 7(a) / 504 | 10-20+ years | 10-15% | Larger fleets or combined facility purchases |
| Working Capital Loan | 6-24 months | None | Bridging reimbursement delays post-launch |
How Crestmont Capital Helps Mobile Imaging Businesses
Crestmont Capital works with mobile diagnostic and imaging entrepreneurs to structure financing around the realities of this niche: high equipment costs, long build lead times with specialty upfitters, and revenue that ramps up as service contracts come online rather than on day one.
Our medical equipment financing programs are built to handle the combined vehicle-and-modality structure of mobile imaging purchases, and our imaging equipment financing options extend to X-ray, ultrasound, and CT systems whether they are installed in a fixed facility or a mobile unit. For operators specifically financing portable radiography systems, our X-ray machine financing programs are designed to move quickly so your build timeline does not stall waiting on funding.
We also work with operators who are expanding from a single fixed imaging center into mobile service. If you have already read our guide on diagnostic imaging center business loans, the same underwriting philosophy applies here: we look at your referral relationships, your industry experience, and the collateral value of the equipment, not just a credit score in isolation.
We also offer business lines of credit for operators who want a flexible cushion for day-to-day costs like fuel, insurance, and staffing separate from their equipment loan.
Applications can be completed online in minutes, with most equipment financing decisions returned within 24 to 48 hours, and funding delivered directly to your manufacturer or upfitter once terms are finalized.
Build Your Mobile Imaging Fleet Faster
Whether it is your first van or your fifth, get financing structured around your service contracts and revenue timeline.
Apply Now →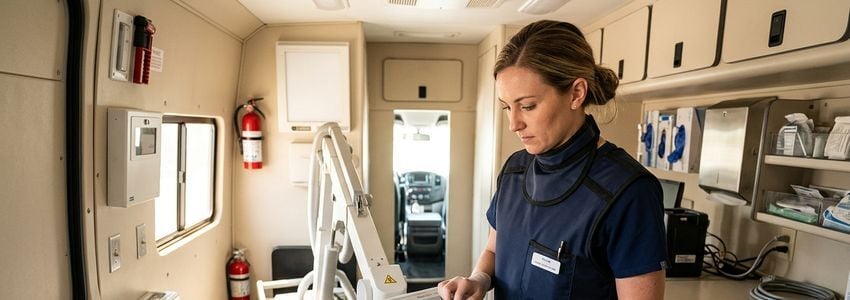
Real-World Scenarios
Scenario 1: The Solo Operator Launching a Mobile X-Ray Service. A licensed radiologic technologist with eight years of hospital experience wants to launch a mobile X-ray service targeting skilled nursing facilities in her metro area. She has signed letters of intent from three facilities but only $15,000 in savings against a $220,000 quote for a fully outfitted van. Equipment financing with a modest down payment, structured against the equipment as collateral and supported by the signed facility agreements, gets her van on the road within six weeks of approval.
Scenario 2: An Imaging Center Adding Mobile Capacity. An established diagnostic imaging center with two years of tax returns and consistent revenue wants to add a mobile ultrasound unit to serve a rural county 45 minutes away where the local hospital recently closed its imaging department. Because the business has an operating history and strong financials, it qualifies for a longer-term equipment loan with a lower rate than a brand-new operator would receive.
Scenario 3: A Regional Fleet Expansion. A mobile imaging company operating three vans wants to add a fourth unit plus a mobile CT trailer to win a hospital system contract covering four rural counties. Given the scale of the purchase, an SBA 504 loan is used to finance the CT trailer while a separate equipment loan covers the additional van, spreading risk and optimizing terms across two structures.
Scenario 4: Bridging a Reimbursement Gap. A newly launched mobile imaging provider has vans on the road and contracts signed, but insurance reimbursements are taking 60 to 90 days to process, creating a cash flow gap for payroll and fuel. A working capital loan bridges the gap until reimbursements catch up with billed volume.
Scenario 5: Upgrading Aging Equipment. An operator running a five-year-old mobile ultrasound unit needs to replace aging imaging technology that is becoming difficult to service. A lease-to-upgrade structure allows the equipment to be swapped for a newer system without a large new capital outlay, keeping the business competitive on image quality.
What Lenders Look For
Underwriting for mobile imaging van financing blends elements of standard equipment lending with a closer look at the healthcare services side of the business.
- Industry experience. Lenders weigh clinical or operational experience in radiology, imaging, or healthcare services heavily, since this reduces execution risk on a specialized business model.
- Signed contracts or letters of intent. Facility agreements with nursing homes, hospitals, or health systems demonstrate a revenue path and materially strengthen an application, especially for newer operators.
- Credit profile. Both business and personal credit are typically reviewed, though strong industry experience and contracts can offset a less-than-perfect credit history.
- Equipment specifications and vendor quotes. A detailed, itemized quote from the manufacturer or upfitter, breaking down the chassis, shielding, and imaging modality, speeds up underwriting significantly.
- Licensing and compliance. Depending on the imaging modality, state radiologic technology licensing, FDA registration for the equipment, and applicable state mobile health unit permits may be requested.
- Time in business. Established operators generally access longer terms and lower rates, though startup financing is available for qualified first-time operators with strong contracts and industry background.
The Application Process, Step by Step
Quick Guide
Financing Your Mobile Imaging Van, At a Glance
Obtain a detailed quote from your van upfitter covering the vehicle and imaging modality.
Bank statements, tax returns, licensing, and any signed facility contracts.
Apply online in minutes with your business and equipment details.
Receive your offer, review term length and payment schedule, and sign your agreement.
Funds are released to your upfitter and your van is built or delivered.
Frequently Asked Questions
Serve More Facilities. Scan More Patients.
Get your mobile imaging van financed and on the road with a lender that understands the diagnostic imaging business.
Apply Now →Next Steps
Contact your preferred mobile imaging upfitter for a detailed, itemized quote.
Bank statements, tax returns, and any signed facility agreements.
Submit your application online and get a decision in as little as 24 to 48 hours.
Conclusion
Mobile medical imaging van financing exists precisely because this industry's opportunity and its capital requirements are both unusually large. Rural hospital closures, overflow demand at urban imaging centers, and the ongoing shift toward bringing diagnostics directly to patients have created real, sustained demand for mobile imaging services. The businesses that capture that demand are the ones who can get a properly equipped van on the road without waiting years to save enough cash to buy one outright.
Whether you are launching your first mobile X-ray unit or adding a fourth vehicle to an established fleet, the right financing structure, whether that is equipment financing, leasing, an SBA loan, or a combination layered with working capital, can be the difference between a stalled business plan and a van generating revenue within weeks. Crestmont Capital works with mobile imaging operators to structure financing around the specifics of this industry, from vendor quotes to facility contracts, so you can focus on serving patients instead of chasing capital.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.








