
 (800) 949-0401
Agricultural Drone Financing: The Complete Guide for Business Owners
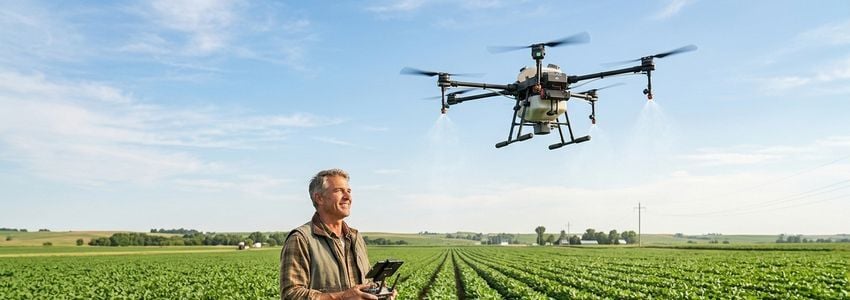
Agricultural drone financing has become one of the fastest-growing corners of farm equipment lending, and for good reason. Spray drones, crop-scouting drones, and mapping platforms are no longer a novelty on American farms. They are now a practical tool that helps growers cut labor costs, reduce chemical use, and get product on the field faster than a ground rig or a crewed aircraft ever could.
The challenge for most farm operators and ag-service businesses is not whether a drone makes sense. It is how to pay for one without draining working capital during planting season, or how to expand a small fleet of spray drones into a full commercial operation. That is where agricultural drone financing comes in.
This guide walks through everything a business owner needs to know about financing agricultural drones: what the equipment actually costs, the financing products available, who qualifies, and how Crestmont Capital helps farm operations and ag-tech service providers get funded quickly.
In This Article
- What Is Agricultural Drone Financing?
- Key Benefits of Financing an Agricultural Drone
- How Agricultural Drone Financing Works
- Types of Financing Available
- Who Agricultural Drone Financing Is Best For
- Financing vs. Buying Outright vs. Leasing
- How Crestmont Capital Helps
- Real-World Financing Scenarios
- Frequently Asked Questions
- Next Steps
- Conclusion
What Is Agricultural Drone Financing?
Agricultural drone financing is a category of equipment financing used to purchase or lease unmanned aerial systems (UAS) built for farm use. This includes spray drones for applying pesticides, herbicides, and fertilizer, crop-scouting drones equipped with multispectral cameras, seeding and cover-crop drones, and mapping drones used for yield analysis and irrigation planning.
Unlike a personal loan or a general business line of credit, agricultural drone financing is structured around the equipment itself. The drone, its batteries, ground control station, and spray or seeding attachments typically serve as collateral. That structure tends to make approval faster and more accessible than unsecured financing, because the lender has a tangible asset backing the loan.
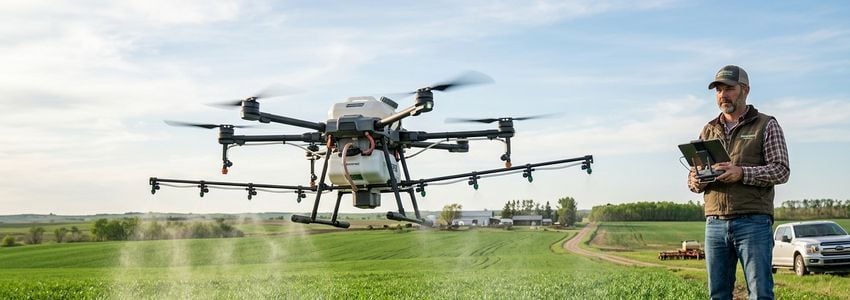
Commercial agricultural drones are not cheap. Entry-level spray drones start around $5,000 to $10,000, while high-capacity commercial spray drones with 40 to 70 liter tanks, multiple batteries, RTK positioning, and a full support kit commonly run $15,000 to $50,000 or more per unit. A farm or ag-service business scaling to a small fleet of two or three drones can easily face a $60,000 to $150,000 capital need. Financing spreads that cost into manageable monthly payments instead of one disruptive lump-sum purchase.
Industry Insight: Industry trade reporting shows U.S. drone spray acreage grew nearly 60% year over year, with well over 16 million acres treated by spray drones as adoption accelerates among row-crop and specialty-crop growers alike.
Key Benefits of Financing an Agricultural Drone
Financing an agricultural drone rather than paying cash, or waiting until a future season when the budget allows, has real operational advantages for a farm or ag-service business:
- Preserve working capital for the season: Cash tied up in a drone purchase is cash that is not available for seed, fertilizer, fuel, or payroll during a critical planting or spraying window.
- Match payments to farm cash flow: Many agricultural financing structures offer seasonal or deferred payment schedules that align with harvest income rather than a flat monthly obligation.
- Access newer technology sooner: Drone technology, battery life, payload capacity, and spray precision have all improved rapidly. Financing lets an operation upgrade every few years instead of running outdated equipment.
- Build a business credit profile: Consistent on-time payments on equipment financing help establish a stronger credit file for future borrowing, whether that is a second drone, a spray truck, or a land purchase.
- Scale a spray-service business faster: Ag-service operators who spray for multiple landowners can finance a second or third unit to take on more acreage in a single season instead of waiting years to save the cash.
- Potential tax advantages: Financed equipment used for business purposes may be eligible for depreciation deductions. Speak with a qualified tax professional to understand what applies to your specific situation.
How Agricultural Drone Financing Works
The mechanics of financing an agricultural drone are similar to financing any piece of specialized equipment, with a few nuances specific to farm operations and seasonal income.
Step 1 - Get a quote. Identify the drone platform, payload size, and any support equipment (extra batteries, generator, trailer, RTK base station) you need, and get a written quote from the dealer or manufacturer.
Step 2 - Apply for financing. Submit a simple application with basic business information, recent bank statements, and the equipment quote. Crestmont Capital's process is built to be fast, with minimal paperwork compared to a traditional bank loan.
Step 3 - Underwriting review. The lender evaluates your business revenue, time in operation, credit profile, and the value of the equipment being financed. Because the drone itself typically secures the loan, approval can move quickly even for newer operations.
Step 4 - Review your offer. You will receive terms outlining the loan or lease amount, payment schedule, term length, and any fees. Farm-focused lenders often build in seasonal payment options that reduce or defer payments during the off-season.
Step 5 - Funding and delivery. Once you accept terms and sign, funds are released so you can complete the purchase. Many operators are flying within days of approval rather than weeks.
Key Stat: According to the U.S. Small Business Administration, access to timely capital remains one of the top factors determining whether a small agricultural or service business can adopt new technology and scale operations.
Types of Agricultural Drone Financing Available
There is no single "drone loan" product. Instead, agricultural drone purchases are typically funded through one of the following options, each suited to a different situation.
Equipment Financing
Equipment financing is the most common way to fund an agricultural drone purchase. The drone and its accessories serve as collateral, which typically means faster approval and more competitive terms than unsecured financing. Loan terms usually run 24 to 60 months, matched to the useful life of the equipment.
Equipment Leasing
Equipment leasing is a strong option for operations that expect to upgrade drone technology every two to three years, since drone battery and payload technology continues to evolve quickly. Leasing keeps monthly costs lower than a purchase loan and can include an end-of-term buyout or upgrade option.
Agricultural Equipment Financing
Agricultural equipment financing programs are structured around the realities of farm income, including seasonal or harvest-timed payment schedules. This is often the best fit for row-crop and specialty-crop operations financing a drone alongside other farm equipment.
Farm Equipment Financing
Farm equipment financing covers a broad range of machinery, and many lenders will bundle a drone purchase with other equipment needs like a sprayer, planter, or irrigation upgrade into a single financing package.
Used Equipment Financing
Because drone technology moves quickly, a healthy secondary market exists for lightly used spray and mapping drones. Used equipment financing allows an operator to acquire a proven platform at a lower price point while still spreading the cost over time.
Bad Credit Equipment Financing
Newer farm operations or those with credit challenges are not automatically excluded. Bad credit equipment financing programs weigh the value of the collateral and business revenue more heavily than a personal credit score alone.
Ready to Add a Drone to Your Farm Operation?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation - apply in minutes.
Apply Now →Who Agricultural Drone Financing Is Best For
Agricultural drone financing makes sense for a wide range of operators, not just large industrial farms. Common applicants include:
- Row-crop and specialty-crop farmers who want to reduce chemical costs and improve application precision without adding a full-time equipment operator.
- Custom spray-service businesses that fly for multiple landowners and need to scale a fleet of drones to cover more acreage per season.
- Vineyard, orchard, and specialty growers using drones for targeted spraying in terrain that is difficult for ground equipment or crewed aircraft to reach efficiently.
- Cooperative and co-op operations financing shared equipment across multiple member farms.
- Ag-tech and precision agriculture consultants who use mapping and scouting drones as a core part of their service offering to farm clients.
- Ranch and livestock operations using drones for herd monitoring, fence-line inspection, and pasture assessment.
If your operation generates consistent revenue and has at least a few months of business banking history, you are likely a strong candidate for agricultural drone financing even if your credit is not perfect.
Financing vs. Buying Outright vs. Leasing
Choosing the right acquisition method depends on cash position, how quickly technology in your segment is changing, and how the drone will be used. The table below compares the three most common approaches.
| Approach | Upfront Cost | Ownership | Best For |
|---|---|---|---|
| Buying Outright (Cash) | Full purchase price | Immediate, full ownership | Operations with excess cash and no near-term upgrade plans |
| Equipment Financing | Low or no down payment | Ownership at term end | Farms and ag-service businesses that want to own the drone long-term |
| Equipment Leasing | Minimal or none | Optional buyout or upgrade | Operators who expect to upgrade drone technology every 2-3 years |
By the Numbers
Agricultural Drone Financing - Key Data Points
$5K-$50K
Typical price range for entry-level to commercial spray drones
16M+
Acres treated by spray drones in a recent season, per industry reporting
89.8%
Share of U.S. employer businesses with fewer than 20 employees, per SBA data
24-60 Mo
Typical equipment financing term for agricultural drones
How Crestmont Capital Helps Farm and Ag-Service Businesses
Crestmont Capital is the #1 business lender in the United States, and our team understands that agriculture does not run on a standard monthly billing cycle. Farm income is seasonal, capital needs are often urgent ahead of a planting or spray window, and the right lender needs to move at the pace of the growing season, not the pace of a traditional bank.
Here is what sets Crestmont Capital apart for agricultural drone financing:
- Fast decisions so you are not waiting weeks during a critical application window
- Flexible qualification criteria that weigh business revenue and equipment value alongside credit history
- A full range of products from equipment financing to agricultural equipment financing to equipment leasing
- Options for newer or credit-challenged operations through our bad credit equipment financing program
- Experience with related ag-tech and specialty farm equipment financing across the country
If you are exploring related equipment purchases alongside a drone, our team has also helped operators finance other specialized farm and agricultural technology. You may find our guides on commercial drone financing and sod farm equipment financing useful as you plan your broader equipment strategy.
Whether you need $8,000 to add your first spray drone or $150,000 to build out a multi-unit fleet for a custom application business, Crestmont Capital has a financing path that fits. Applications typically take just a few minutes to complete, with no obligation to accept an offer.
Talk to an Agricultural Equipment Financing Specialist
Crestmont Capital offers custom financing solutions for farms and ag-service businesses nationwide. No obligation - get your offer today.
Apply Now →Real-World Financing Scenarios
Scenario 1: Row-Crop Farm Adding a First Spray Drone
Dan operates a 2,400-acre corn and soybean farm and wanted to reduce reliance on a custom applicator for late-season fungicide passes. He used equipment financing to purchase a commercial spray drone with a 40-liter tank for roughly $22,000, structured with a payment schedule weighted toward the post-harvest months. The drone paid for itself within two seasons through reduced application fees.
Scenario 2: Custom Spray-Service Business Scaling to Three Units
Renee runs a custom aerial application business serving row-crop farms across a three-county area. Demand outpaced her single-drone capacity during peak spray windows. She financed two additional commercial spray drones for a combined $65,000, allowing her to cover more acreage in the same tight application window and take on new client contracts.
Scenario 3: Vineyard Financing a Mapping and Scouting Drone
A mid-size vineyard operation financed a multispectral mapping drone to monitor vine stress and irrigation needs across uneven terrain that was difficult to scout on foot. The $14,000 equipment financing package let the vineyard identify problem blocks earlier in the season, improving yield and reducing water waste.
Scenario 4: Cattle Ranch Adding a Drone for Herd and Fence Monitoring
A cattle operation spanning several thousand acres financed a rugged drone platform to check fence lines and locate cattle across difficult terrain, cutting the time staff spent on manual truck and horseback patrols. The equipment lease kept monthly costs predictable while giving the ranch flexibility to upgrade the platform in three years.
Scenario 5: Ag-Tech Consultant Building a Service Fleet
An independent precision-agriculture consultant used financing to acquire a small fleet of scouting and mapping drones to offer as a service to area farms that could not justify owning equipment themselves. The financed equipment became the foundation of a new revenue line, billed on a per-acre basis to client farms.
Frequently Asked Questions
Next Steps
Identify the drone platform and support equipment you need, and get a written quote from your dealer.
Complete our quick application at offers.crestmontcapital.com/apply-now - takes just a few minutes.
A Crestmont Capital lending specialist will walk you through your options so you can put your new drone to work this season.
Access to fast, flexible capital continues to separate growing agricultural operations from those that fall behind on technology adoption. According to Forbes Small Business coverage of equipment financing trends, businesses that establish financing relationships proactively, rather than waiting until a piece of equipment fails, are consistently better positioned to compete.
Ready to Finance Your Agricultural Drone?
Apply in minutes and get a funding decision fast. Crestmont Capital supports farms and ag-service businesses at every stage of growth.
Apply Now →Conclusion
Agricultural drone financing gives farm operators and ag-service businesses a practical way to add precision spraying, mapping, and scouting technology without disrupting cash flow during a critical season. Whether you are a row-crop farm adding your first spray drone, a custom applicator scaling to a multi-unit fleet, or a rancher looking to modernize herd and fence-line monitoring, the right financing structure can put the equipment to work now while spreading the cost over its useful life.
Crestmont Capital works with agricultural operations across the country to match the right financing product to the right equipment, with fast decisions and flexible qualification criteria built around how farm businesses actually operate. Explore your options today and see what your operation can put in the air this season.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.








