Portable MRI unit financing gives imaging center owners, mobile diagnostic companies, and healthcare entrepreneurs a way to acquire a scanner without paying $250,000 to $2 million upfront. This guide breaks down how the financing works, what it costs, and how to qualify.
In This Article
What Is Portable MRI Unit Financing?
Portable MRI unit financing is a type of equipment financing specifically structured to help businesses acquire mobile or transportable magnetic resonance imaging systems. Instead of paying the full purchase price in cash, a healthcare provider or imaging company spreads the cost of the scanner over a fixed term through a loan or lease, while the equipment itself typically serves as collateral.
Portable and mobile MRI units have become a core part of how diagnostic imaging is delivered outside of large hospital systems. New units can run well above $1 million depending on magnet strength and configuration, while refurbished systems and compact units like trailer-mounted scanners often start in the $250,000 to $500,000 range. Financing turns that large capital expense into a predictable monthly payment that can be matched against the revenue the scanner generates.
This type of financing applies to a wide range of buyers: independent diagnostic imaging centers expanding their service lines, mobile imaging companies that bring scanners to rural hospitals and clinics, orthopedic and sports medicine practices adding in-house imaging, and veterinary or research operations that need MRI capability without a fixed capital suite.
Unlike financing a standard piece of office or restaurant equipment, portable MRI financing sits at the intersection of healthcare economics and equipment lending. Lenders need to understand not just the value of the machine itself, but how diagnostic imaging revenue is generated, how reimbursement timelines work for insurance-billed scans versus cash-pay patients, and how quickly a new or expanded imaging line can reach the utilization needed to support its payment. That is why working with a lender experienced in healthcare equipment, rather than a generalist equipment lender, often produces a better outcome for both approval odds and structuring flexibility.
Key Stat: The U.S. diagnostic imaging centers industry generated an estimated $26.9 billion in revenue in 2024, with roughly 40% of all radiology volume now performed outside acute-care hospitals in outpatient and mobile settings, according to industry market research.
Key Benefits of Financing a Portable MRI Unit
- Preserve working capital. Keep cash available for staffing, marketing, and day-to-day operations instead of tying it up in a single piece of equipment.
- Match payments to revenue. A scanner generates billable scans from day one, so structured monthly payments can align with incoming reimbursement and cash-pay revenue.
- Predictable budgeting. Fixed-rate financing locks in a known monthly cost, which makes it easier to forecast margins per scan.
- Faster deployment. Approved financing can move a business from decision to delivery in weeks rather than waiting to save up a large cash reserve.
- Potential tax treatment advantages. Depending on how the equipment is financed, businesses may be able to deduct lease payments or depreciate the asset. Always confirm specifics with a qualified tax professional.
- Upgrade flexibility. Leasing structures in particular make it easier to upgrade to newer MRI technology as magnet strength and software improve, rather than being locked into aging equipment.
Ready to Add Imaging Capability?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation, apply in minutes.
Apply Now →How Portable MRI Unit Financing Works
The process for financing a portable MRI unit follows a similar path to other major medical equipment financing, with a few extra steps because of the equipment's size, specialized installation needs, and high price point.
Quick Guide
How Portable MRI Financing Works, At a Glance
Choose a new or refurbished portable MRI unit and get a vendor quote with specs and price.
Provide business financials, the equipment quote, and basic business information to the lender.
The lender reviews credit, cash flow, and the equipment's resale value to set terms and rate.
Once approved, funds are released to the vendor and installation/delivery is scheduled.
Lenders evaluating a portable MRI financing request typically look at time in business, personal and business credit history, monthly revenue or projected revenue (for a new imaging line of business), and the specific equipment being financed since MRI systems hold strong resale value compared to many other equipment categories. Terms commonly range from 24 to 84 months depending on the age and type of unit, with rates influenced by the borrower's credit profile and the lender's risk assessment.
Insurance is another piece of the underwriting picture that is easy to underestimate. Most lenders will require proof of adequate property and liability insurance covering the equipment for its full replacement value before funding, and many portable MRI units also need specialized coverage for the magnet and electronics that goes beyond a standard commercial equipment policy. Getting a quote from your insurance broker early in the process, alongside the equipment vendor quote, helps avoid delays at closing.
Because portable MRI units often require site preparation, including shielding, power supply upgrades, and in some cases a custom trailer or mobile coach, financing packages can sometimes be structured to include installation and delivery costs alongside the equipment cost itself. It is worth asking any lender directly whether "soft costs" like shielding and site prep can be rolled into the total financed amount.
Documentation requirements for a portable MRI financing application typically include at least three to six months of business bank statements, the most recent one to two years of business tax returns, a personal financial statement for any owner with 20% or more equity in the business, and a detailed equipment quote from the manufacturer or dealer. Larger financing requests, particularly those above $500,000, may also require a short business plan or revenue projection showing how the new imaging capability will be utilized, especially if the business is adding a new service line rather than replacing existing equipment.
One factor that sets MRI financing apart from financing for most other equipment categories is the strength of the collateral. Because MRI systems hold their value relatively well compared to vehicles or general machinery, and because a healthy secondary market exists for refurbished units from major manufacturers, lenders are often willing to extend more favorable terms than they would for equipment that depreciates quickly or has a thin resale market. This collateral strength can translate into lower down payment requirements and more competitive rates for qualified borrowers.
Manufacturer choice can also influence financing terms. Units from established manufacturers such as GE Healthcare, Siemens Healthineers, Philips, and Canon Medical Systems tend to hold resale value better and have more readily available parts and service networks, which lenders view favorably during underwriting. A lesser-known manufacturer or a highly customized mobile coach build may require additional documentation or a slightly larger down payment to offset the lender's uncertainty about long-term resale value.
Financing Options for Portable MRI Units
There is not a single way to finance a portable MRI unit. The right structure depends on whether the business wants to own the equipment outright, preserve flexibility to upgrade, or minimize the initial cash outlay.
- Equipment financing (term loan secured by the equipment): The business borrows the full or near-full purchase price and repays over a fixed term, building equity in the scanner as the loan is paid down. Best for businesses planning to keep the same unit for 5+ years.
- Equipment leasing: The business makes monthly lease payments and, depending on the lease structure, may have the option to purchase the unit at the end of the term for a nominal amount (capital lease) or return/upgrade it (operating lease). Leasing can lower the upfront cash requirement and simplify upgrading to newer MRI technology.
- Sale-leaseback: For a business that already owns a portable MRI unit outright, a sale-leaseback converts that owned equipment into immediate cash by selling it to a financing company and leasing it back, which can free up capital for expansion elsewhere.
- SBA-backed loans: SBA 7(a) and 504 loans can be used to finance large equipment purchases, including diagnostic imaging systems, often with longer repayment terms and competitive rates for businesses that qualify.
- Working capital loans paired with equipment financing: Some operators pair a dedicated equipment loan for the MRI unit itself with a separate working capital facility to cover staffing, marketing, and the ramp-up period before the scanner reaches full utilization.
Who Portable MRI Unit Financing Is Best For
Portable MRI financing tends to make the most sense for a specific set of buyers:
- Independent diagnostic imaging centers adding MRI capability to compete with hospital-affiliated competitors and capture referrals that would otherwise go elsewhere.
- Mobile imaging service providers that bring scanning capability to rural hospitals, surgical centers, and clinics that cannot justify a fixed MRI suite.
- Orthopedic, sports medicine, and neurology practices that want to bring imaging in-house instead of referring patients out, capturing that revenue and improving patient convenience.
- Veterinary diagnostic and research operations that need MRI capability on a smaller scale than a hospital system but still require a significant capital outlay.
- Multi-site healthcare groups expanding imaging services to a new location without disrupting cash reserves earmarked for other growth initiatives.
It is generally a poor fit for a brand-new business with no healthcare operating history and no existing patient or referral base, since lenders want to see a credible plan for how the scanner will generate enough volume to cover payments.
Utilization is the metric that matters most once the equipment is in place. A single portable MRI unit typically needs to run a minimum number of scans per week to cover its financing payment, staffing, maintenance contracts, and facility costs before it starts contributing to profit. Operators considering this type of financing should map out a realistic utilization schedule before signing any equipment quote, factoring in referral volume, scheduling software efficiency, and any seasonal variation in patient demand.
Staffing is another consideration that often gets overlooked during the financing conversation but directly affects whether a portable MRI unit becomes profitable. A scanner requires a credentialed MRI technologist to operate it, and in many markets qualified technologists are in short supply, with vacancy rates for MRI techs reaching record highs in recent years. Before financing a unit, it is worth confirming staffing availability, whether through direct hire, a staffing agency partnership, or a technologist already on staff who can be cross-trained, since an idle scanner due to a staffing gap still carries its full monthly payment.
Comparing Your Financing Options
| Option | Typical Term | Best For | Ownership |
|---|---|---|---|
| Equipment Financing | 24-84 months | Long-term ownership, building equity | Full ownership at payoff |
| Equipment Leasing | 24-60 months | Lower upfront cost, upgrade flexibility | Optional buyout or return |
| Sale-Leaseback | 24-60 months | Freeing up capital from owned equipment | Lease with repurchase option |
| SBA 7(a) / 504 | Up to 25 years | Established practices, lowest rates | Full ownership at payoff |
How Crestmont Capital Helps
Crestmont Capital works with imaging centers, mobile diagnostic companies, and medical practices to structure imaging equipment financing around the realities of the healthcare business, including high equipment costs, reimbursement timelines, and the need to move quickly when a growth opportunity appears. Our MRI machine financing programs are built specifically for diagnostic imaging buyers, whether the unit is new, refurbished, fixed, or mobile.
For practices that need broader support beyond the scanner itself, including diagnostic software, patient monitoring systems, or facility upgrades, our healthcare equipment financing and medical equipment financing programs can be structured alongside the primary MRI financing. If cash flow needs extend beyond equipment into staffing or marketing during the ramp-up period, our unsecured working capital loans and business line of credit options can fill that gap. Businesses with a strong operating history may also qualify for our SBA loan programs for longer terms and lower rates.
We also work with operators researching adjacent equipment categories, from our broader guide on financing imaging centers to our deep dive on diagnostic imaging center business loans, both of which cover complementary financing strategies for growing an imaging operation.
Let's Talk About Your Imaging Equipment Needs
Our team understands the healthcare financing landscape. Get a custom quote in minutes.
Apply Now →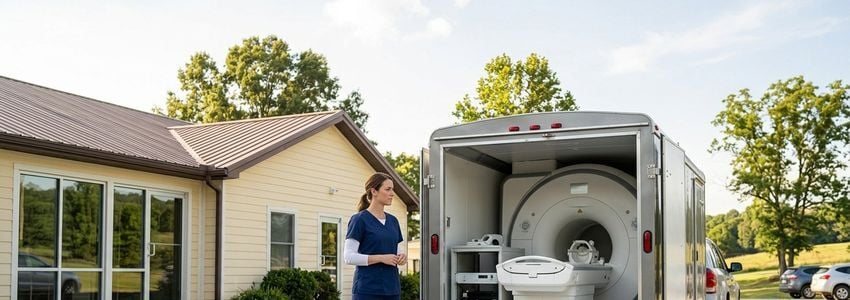
Real-World Scenarios
Scenario 1: Independent imaging center adds a second modality. An independent diagnostic imaging center that currently offers X-ray and ultrasound wants to add MRI to stop losing referrals to the hospital across town. The owner finances a refurbished 1.5T unit through a 60-month equipment loan, using projected scan volume from existing referral relationships to support the application.
Scenario 2: Mobile imaging company expands its fleet. A mobile imaging provider serving rural hospitals across three states wants to add a second trailer-mounted MRI unit to meet growing demand. Rather than depleting cash reserves, the company uses equipment leasing to acquire the new unit while keeping capital available for driver staffing and fuel costs.
Scenario 3: Orthopedic practice brings imaging in-house. An orthopedic group currently refers every MRI order to an outside imaging center, losing both revenue and control over turnaround time. The practice finances a compact extremity MRI unit through a term loan, paying it down with the revenue previously lost to outside referrals.
Scenario 4: Veterinary diagnostic center upgrades equipment. A veterinary referral hospital replaces an aging MRI unit with a newer, faster system through a sale-leaseback on the old unit combined with new equipment financing, minimizing the net cash outlay for the upgrade.
Scenario 5: Multi-site radiology group opens a new location. A radiology group opening its fourth imaging location finances the portable MRI unit for the new site through SBA 504 financing, locking in a long repayment term that matches the 20-year lease on the building itself.
Scenario 6: Sports medicine clinic adds rapid-turnaround imaging. A sports medicine clinic treating weekend-warrior athletes and local college teams wants same-day imaging instead of sending patients to an outside facility for a scan that delays treatment by days. The clinic finances a compact MRI unit through a 48-month equipment loan, marketing same-day imaging as a competitive differentiator against larger orthopedic groups in the area.
Pro Tip: Ask any equipment vendor for a written quote that separates the base unit cost from installation, shielding, and delivery. Lenders can often finance these "soft costs" alongside the equipment itself, but only if they are clearly itemized on the quote.
By the Numbers
Diagnostic Imaging Industry Snapshot
$26.9B
U.S. diagnostic imaging centers industry revenue, 2024
40%
Of radiology volume now performed outside hospitals
6,968
Diagnostic imaging facilities nationwide
5.2%
Projected average annual industry growth through 2028
Frequently Asked Questions
Get Pre-Qualified for MRI Equipment Financing
No obligation. See your options in minutes with Crestmont Capital.
Apply Now →Next Steps
Conclusion
Portable MRI unit financing makes it possible for imaging centers, mobile diagnostic companies, and healthcare practices to add high-value scanning capability without draining cash reserves on a single large purchase. Whether the right fit is equipment financing, leasing, a sale-leaseback, or an SBA-backed loan, matching the structure to how the equipment will be used and how quickly it is expected to generate revenue is the key decision point. Crestmont Capital works with healthcare and imaging businesses across the country to structure portable MRI unit financing that fits the realities of the diagnostic imaging industry.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.