Mobile x-ray equipment financing gives diagnostic imaging entrepreneurs a direct path to acquiring the portable radiography units that power a mobile X-ray business, without tying up six figures of working capital in a single purchase. Whether you are launching a solo mobile radiography practice that serves nursing homes and home health patients, or expanding an existing operation with a second or third portable DR unit, the right financing structure determines how quickly you can put equipment in the field and start billing for exams.
Demand for mobile X-ray services is accelerating. Skilled nursing facilities, assisted living communities, hospice providers, and home health agencies increasingly prefer on-site imaging over transporting medically fragile patients to a hospital or outpatient center. For entrepreneurs positioned to serve this niche, the opportunity is rarely the limiting factor. It is the $17,000 to $185,000 price tag attached to a properly equipped portable digital radiography system.
This guide walks through every financing option available to mobile X-ray business owners, how lenders underwrite these deals, what documentation to expect, and how to build an application package that gets approved quickly.
We will also cover the practical differences between equipment categories, how to decide between new and refurbished units, and real scenarios showing how other mobile imaging operators have structured their financing to win new facility contracts without straining cash flow.
In This Article
- What Is Mobile X-Ray Unit Financing?
- Key Benefits of Financing a Mobile X-Ray Unit
- How Mobile X-Ray Unit Financing Works
- Types of Mobile X-Ray Equipment and Financing Structures
- Who This Financing Is Best For
- Comparing Your Financing Options
- How Crestmont Capital Helps
- Real-World Scenarios
- Frequently Asked Questions
- Next Steps
- Conclusion
What Is Mobile X-Ray Unit Financing?
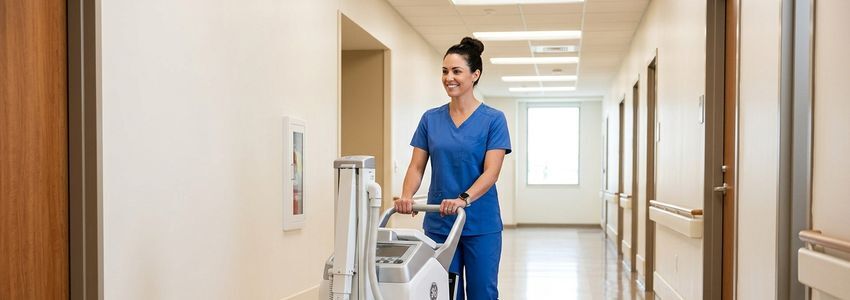
Mobile x-ray equipment financing is a funding arrangement that lets a diagnostic imaging business acquire a portable or mobile digital radiography (DR) system and pay for it over time, instead of in a single upfront purchase. This covers everything from compact handheld DR panels and battery-powered cart units to full-size mobile X-ray carts with hospital-grade generators, mounted detector arms, and wireless image transfer.
Most mobile X-ray financing is structured as an equipment finance agreement (EFA) or an equipment lease, both of which use the unit itself as collateral. Because the asset secures the loan, lenders can typically approve these deals faster and with less documentation than an unsecured loan of the same size.
Key Stat: The U.S. population aged 65 and older grew 13.0% between 2020 and 2024, far outpacing growth in every other age group, according to the U.S. Census Bureau. That demographic shift is a primary driver of demand for mobile and in-home diagnostic imaging services.
Unlike a hospital radiology department purchasing fixed-room equipment, mobile imaging operators need units built for portability, durability, and quick setup in a patient's home, a skilled nursing facility, or a vehicle. Financing structured specifically for this equipment class accounts for the shorter useful life of batteries and wireless components, and the fact that the unit will be transported and handled far more than stationary hospital equipment.
The term "mobile x-ray unit" can refer to a few different configurations in practice. Some operators use a compact, battery-powered DR panel system that a single technologist carries in a rolling case. Others run a full cart-based system with its own generator, mounted on wheels and loaded into a van or SUV between stops. The financing conversation looks slightly different depending on which configuration you are purchasing, since cart-based systems often require additional vehicle outfitting considerations that a lender may bundle into the same transaction or handle as a separate line item.
Key Benefits of Financing a Mobile X-Ray Unit
Financing a portable X-ray system instead of buying it outright preserves cash flow for the parts of the business that generate revenue: staffing, licensing, insurance credentialing, and marketing to referral sources.
- Preserve working capital: Keep cash on hand for payroll, fuel, and facility contracts instead of depleting reserves on a single asset purchase.
- Predictable monthly payments: Fixed payment schedules make budgeting simple, especially for a business billing per-exam or per-contract.
- Faster deployment: Get a unit in the field in days rather than months of saving toward a cash purchase.
- Tax advantages: Many equipment finance structures allow the full cost of the equipment to be deducted in the year it is placed in service, subject to applicable limits. Consult your tax advisor for specifics.
- Technology upgrades: Shorter lease terms let you upgrade to newer detector technology as wireless DR panels continue to improve, rather than being stuck with aging equipment.
- Scale with demand: Add a second or third unit as new facility contracts come online, without waiting to accumulate cash reserves between purchases.
Ready to Equip Your Mobile Imaging Business?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation, apply in minutes.
Apply Now →How Mobile X-Ray Unit Financing Works
The process of financing a portable X-ray system follows a similar path to other equipment financing, with a few industry-specific wrinkles around licensing and vendor selection.
Unlike financing a commodity asset such as a delivery van, mobile X-ray equipment carries regulatory requirements that lenders factor into their underwriting. State radiation control programs require registration of the equipment itself, and the operating technologist must hold an active license. Lenders experienced in healthcare equipment financing know to ask for this documentation upfront rather than discovering a licensing gap mid-process, which keeps the timeline moving instead of stalling at the finish line.
Another difference from general equipment financing is how the collateral is valued. A portable DR panel or mobile cart depreciates differently than, say, a delivery truck. Wireless detector technology changes every few years, and battery components have a finite service life. Lenders who specialize in medical equipment account for this in how they structure residual values on leases, which is why working with a lender familiar with imaging equipment, rather than a generalist, often produces better terms.
- Select your equipment and vendor. Identify the specific DR unit (new or refurbished), the manufacturer or distributor, and the total equipment cost including any accessories like wireless panels, carts, or generators.
- Submit your application. Most lenders require a one-page application for equipment financing under roughly $250,000, along with basic business information and a few months of bank statements.
- Underwriting review. The lender evaluates your time in business, personal and business credit, cash flow, and the equipment itself as collateral. Mobile imaging businesses with existing facility contracts or referral agreements often underwrite more favorably.
- Approval and terms. Once approved, you receive a term sheet outlining the payment amount, term length (typically 24 to 72 months), and any down payment or first-and-last payment requirement.
- Funding and vendor payment. The lender pays the equipment vendor directly, and the unit is shipped or delivered to your business.
- Begin payments. Monthly payments begin, typically 30 days after funding, giving you time to complete setup and training before the first payment is due.
Quick Guide
How Mobile X-Ray Financing Works, At a Glance
Select the portable DR system and vendor quote.
Submit a simple application and recent bank statements.
Receive terms often within 24 to 48 hours.
The lender pays your vendor and your unit ships or is installed.
Types of Mobile X-Ray Equipment and Financing Structures
Not every mobile X-ray business needs the same equipment tier. Understanding the categories helps you match the right unit, and the right financing structure, to your patient volume and service area.
Equipment Categories
- Handheld and compact DR panels: Battery-powered, carried by a single technologist, typically $12,000 to $65,000 depending on new versus refurbished condition. Ideal for home visits and solo operators.
- Compact mobile carts: Lightweight carts with a built-in generator and wireless panel, generally $40,000 to $90,000 refurbished or $90,000 to $185,000 new. Common in nursing home and assisted living contracts.
- Full-size hospital-grade mobile carts: Motorized, higher-output systems used for higher patient volume or hospital overflow contracts, often exceeding $100,000.
Choosing between these categories usually comes down to the patient volume you expect to serve and the facility contracts you are targeting. A solo operator seeing two or three patients a day at home health visits does not need the same throughput as an operation running a dedicated route between four skilled nursing facilities. Overbuying capacity ties up more capital than necessary, while underbuying can mean turnaway business once referral volume increases.
Financing Structures
| Structure | Typical Term | Best For |
|---|---|---|
| Equipment Finance Agreement (EFA) | 24 to 72 months | Owners who want to own the unit outright at the end of the term |
| Equipment Lease ($1 buyout or FMV) | 24 to 60 months | Operators who want lower payments or plan to upgrade technology regularly |
| Working Capital Loan | 6 to 24 months | Bundling equipment cost with licensing, insurance, or vehicle outfitting |
| SBA 7(a) Loan | Up to 10 years | Larger, multi-unit purchases with the lowest available rates |
Who This Financing Is Best For
Mobile X-ray unit financing fits a range of business models within the diagnostic imaging space.
- Independent mobile radiography technologists launching a solo practice serving home health and hospice patients.
- Mobile imaging companies adding a second or third unit to fulfill new skilled nursing facility contracts.
- Urgent care and occupational medicine clinics adding portable X-ray capability without building a dedicated radiology suite.
- Veterinary mobile practices that also perform portable radiography for large or exotic animals.
- Imaging centers that want a backup or overflow unit for off-site exams.
Lenders generally look for at least six months in business, an active state license to operate diagnostic imaging equipment, and a reasonable personal credit profile from the business owner or guarantor. Businesses with signed facility contracts in hand typically see faster underwriting and stronger terms.
This financing structure is generally a poor fit for businesses still in the planning stage with no licensing in place, or for operators looking to purchase equipment purely as an investment without an active plan to deploy it for exams. Lenders want to see a clear path to revenue generation, which is one reason signed or pending facility contracts carry so much weight during underwriting.
It is also worth noting that reimbursement structure plays a role in how quickly a new unit pays for itself. Mobile X-ray businesses that bill Medicare, Medicaid, and private insurance directly for exams typically have a longer revenue cycle than those operating under a flat per-visit contract with a skilled nursing facility. Lenders sometimes ask about your billing model during underwriting because it affects how predictable your monthly cash flow will be relative to your new equipment payment.
Comparing Your Financing Options
Choosing between buying new, buying refurbished, and financing versus paying cash comes down to how quickly you need to deploy and how your revenue is structured.
| Option | Upfront Cost | Cash Flow Impact | Ownership Timeline |
|---|---|---|---|
| Cash Purchase | 100% of cost | High, depletes reserves | Immediate |
| Equipment Financing | 0% to 10% down | Low, fixed monthly payment | End of term |
| Equipment Lease | First and last payment | Lowest monthly payment | Optional buyout |
| SBA 7(a) Loan | 10% to 20% down | Moderate, lowest rate | Immediate |
According to the U.S. Small Business Administration, access to capital remains one of the most consistently cited barriers for small business owners looking to grow or launch a new service line. Structured equipment financing exists specifically to close that gap without requiring a business to deplete its cash reserves.
The right choice also depends on how long you plan to keep the equipment in service. An owner who expects to run the same unit for seven or eight years, serving a stable set of facility contracts, is often better served by an equipment finance agreement that builds toward ownership. An owner in a fast-changing service area, where newer wireless detector technology could become a competitive differentiator within three years, may prefer a lease that keeps the door open to upgrading without a large payout.
How Crestmont Capital Helps
Crestmont Capital works with diagnostic imaging entrepreneurs to structure medical equipment financing and imaging equipment financing that fits the realities of a mobile radiography business, including new and refurbished units, bundled accessories, and seasonal cash flow.
Our underwriting team understands the difference between a hospital radiology department and a mobile imaging operator billing per visit across multiple facility contracts. We also offer working capital loans for licensing, insurance, and staffing costs that go along with standing up a new unit, and a business line of credit for ongoing operational flexibility as your contract roster grows.
For businesses planning a larger, multi-unit rollout, our SBA loan programs can provide longer terms and lower payments than conventional equipment financing. If your business also operates a vehicle fleet to transport technologists and equipment between facilities, see our related guide on mobile medical imaging van financing for financing the vehicle side of the operation.
Get Your Mobile X-Ray Unit Funded Fast
Flexible terms built for diagnostic imaging businesses. See your options with no obligation.
Apply Now →Real-World Scenarios
Scenario 1: The Solo Technologist Launching a Practice
A licensed radiologic technologist with eight years of hospital experience decides to launch an independent mobile X-ray service covering home health and hospice patients in her metro area. She has strong personal credit but limited business cash reserves. She finances a refurbished compact mobile cart for $48,000 through a 60-month equipment lease, keeping her upfront cost to the first and last payment. Within four months she signs contracts with two home health agencies and is cash-flow positive on the unit.
Scenario 2: Expanding to a Second Unit
An established mobile imaging company with one unit and steady nursing home contracts is approached by a third facility that requires faster turnaround than their single technologist can provide. The owner finances a second, new compact DR cart for $95,000 using a 48-month equipment finance agreement, allowing the business to run two routes simultaneously and take on the new contract without disrupting existing service.
Scenario 3: Urgent Care Adding Portable Imaging
An urgent care clinic wants to reduce referrals to outside imaging centers for routine fracture and chest X-rays. Rather than build a dedicated radiology room, the clinic finances a handheld DR panel system for $38,000 over 36 months, letting staff perform portable exams in any treatment room.
Scenario 4: Upgrading Aging Equipment
A mobile imaging operator running a seven-year-old CR (computed radiography) cart faces rising service costs and slower image processing compared to competitors using modern DR technology. The owner trades in the old unit and finances a new wireless DR cart for $110,000 over 60 months, improving exam turnaround time and winning a new facility contract that required faster digital image delivery.
Scenario 5: Veterinary Mobile Practice Adding Radiography
A mobile large-animal veterinary practice wants to add portable X-ray capability for field diagnostics on farms and equine facilities. The practice finances a ruggedized portable DR system for $52,000 over 48 months, structuring payments around their seasonal cash flow with lower payments in winter months.
Scenario 6: Multi-State Mobile Imaging Expansion
A regional mobile imaging company operating three units across one state is approached by a regional hospital system to extend coverage into two neighboring states. Rather than risk the entire expansion on existing cash reserves, the owner finances two additional DR carts for a combined $190,000 using a 60-month equipment finance agreement. The predictable payment structure lets the company model exact profitability per new territory before fully committing staff and vehicles to the expansion.
Frequently Asked Questions
Don't Let Equipment Cost Slow Down Your Business
Crestmont Capital has helped thousands of business owners get the equipment they need. See your rate in minutes.
Apply Now →Next Steps
Identify the specific mobile X-ray unit and total equipment cost.
Pull together recent bank statements and basic business information.
Submit your application online and get a decision quickly.
Once funded, your vendor ships or installs the equipment and you start billing.
Conclusion
Mobile x-ray equipment financing removes the single biggest barrier standing between diagnostic imaging entrepreneurs and the equipment they need to serve a growing population of patients who need on-site, convenient radiography. As the 65-and-older population continues to grow faster than any other age group, demand for mobile imaging services that keep patients out of hospital waiting rooms will only increase.
Whether you are financing your first handheld DR panel or adding a fourth mobile cart to an established route, structuring the right financing arrangement lets you deploy equipment quickly while keeping your cash flow intact. According to recent Forbes healthcare technology coverage, home-based and mobile diagnostic care continues to expand as a strategic priority across the industry, making now a strong time to invest in mobile imaging capability.
Crestmont Capital works with mobile radiography operators across the country to structure financing that fits their equipment, their contracts, and their growth plans. Reach out today to see what you qualify for.
Timing matters in this space. Facility contracts often go to whichever provider can demonstrate the capacity to start service quickly, and a financing partner who understands the specific equipment and regulatory landscape of mobile radiography can be the difference between winning a contract and watching it go to a competitor who was simply further along in securing their unit. Getting your financing conversation started before you are actively bidding on new facility business gives you the flexibility to move the moment an opportunity appears.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.