
Manufacturing Business Loans: Financing for Manufacturers & Production Companies
Manufacturing businesses operate on some of the most capital-intensive economics in small business — large equipment investments, raw material inventory purchased weeks before production, and net-30/60/90 payment terms that leave months of completed work unpaid. Crestmont Capital provides manufacturing business loans structured around how production companies actually operate: equipment financing for CNC machines and production lines, working capital for raw material inventory, invoice factoring for long-payment customers, and purchase order financing for large contracts. Fast approval, revenue-based underwriting, and product structures matched to manufacturing cycles.
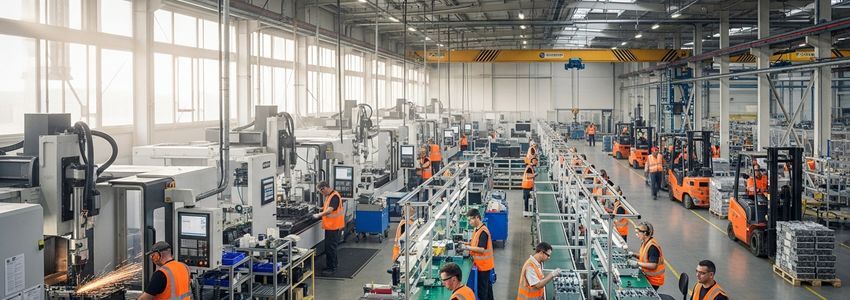
Why Manufacturers Need Specialized Financing
Manufacturing businesses face capital challenges that generic small business lenders misunderstand. The production cycle creates inherent cash flow timing problems: raw materials must be purchased and paid for before a product is manufactured, assembled, quality-tested, shipped, invoiced, and eventually paid — a cycle that can take 60-180 days from cash out to cash in.
- Raw material inventory: Manufacturers must purchase materials before production begins — often requiring $50K-$500K in upfront cash that won't return for 2-6 months
- Equipment is mission-critical and expensive: A single CNC machine breakdown stops production. Replacement or repair is urgent and costs $50K-$500K+
- Net-30/60/90 payment terms: Large customers demand extended payment terms — manufacturers finance their customers' operations for months before receiving payment
- Large contracts require upfront capital: Winning a $2M contract means spending $400K+ on materials and labor before the first invoice is paid
According to the National Association of Manufacturers, small and medium manufacturers consistently cite access to working capital as their top financial challenge. See also: equipment financing and invoice factoring.
Types of Manufacturing Business Loans
Manufacturing Equipment Financing
Equipment financing uses the purchased machinery as collateral, enabling lower rates. CNC machines $50K-$500K, injection molding $100K-$1M, laser cutting $50K-$300K, industrial robots $50K-$500K, conveyor systems $20K-$150K, forklifts $20K-$80K. Terms 3-7 years matched to equipment useful life. See our equipment financing page.
Manufacturing Working Capital Loans
Working capital loans fund raw material purchases, labor, and operating costs before a production cycle generates revenue. Short-term (3-18 months), sized to cover 1-3 production cycles.
Purchase Order Financing
PO financing provides capital to fulfill large contracts — the lender advances 50-90% of the purchase order value to cover materials and production costs. Repayment comes from the customer payment when the order is fulfilled. See our purchase order financing page.
Invoice Factoring for Manufacturers
Invoice factoring advances 80-90% of outstanding invoices immediately, eliminating the Net-30/60/90 wait. See our invoice factoring page. No credit minimum — customer credit quality is what matters.
Manufacturing Lines of Credit
A revolving business line of credit provides ongoing access to working capital — draw for raw material purchases, repay when the production run ships and invoices clear, draw again.
SBA Loans for Manufacturers
SBA 7(a) loans provide the best rates and longest terms for established manufacturers. Manufacturing is a priority sector for SBA lending due to its economic multiplier effect. Terms up to 10 years.
Long-Term Manufacturing Facility Loans
Facility acquisition, expansion, or buildout loans for manufacturers needing larger production space. Terms 5-25 years. See our long-term business loans page.
Who Qualifies?
| Requirement | Typical Threshold | Notes |
|---|---|---|
| Personal Credit Score | 620+ preferred | Equipment loans possible at 580+ with strong collateral |
| Time in Business | 2+ years | SBA loans require 2 years; equipment financing available sooner |
| Annual Revenue | $500,000+ | Scales with loan amount; production contract value also considered |
| Equipment Collateral | For equipment loans | Equipment reduces credit requirements significantly |
| Accounts Receivable | For invoice factoring | Customer credit quality matters more than borrower credit |
Rates, Fees, and Terms
| Product | Typical Rate | Term | Best Use |
|---|---|---|---|
| Equipment Financing | 6%–20% APR | 3–7 years | CNC, robots, production lines |
| Working Capital Loan | 15%–40% APR | 6–18 months | Raw materials, labor, operations |
| Purchase Order Financing | 2%–6% per 30 days | 30–120 days | Large contract fulfillment |
| Invoice Factoring | 1%–4% per 30 days | 30–90 days | Eliminate Net-30/60/90 wait |
| Business Line of Credit | 12%–35% APR | Revolving | Ongoing production cycle capital |
| SBA 7(a) Loan | Prime + 2.75–4.75% | Up to 10 years | Best rates, established manufacturers |
How It Works: Step by Step
Manufacturing Financing by Industry Sector
| Sector | Common Needs | Best Products |
|---|---|---|
| Metal Fabrication & Machining | CNC machines, raw steel, laser cutting | Equipment financing, working capital, LOC |
| Food & Beverage Processing | Processing equipment, ingredients, certifications | Equipment financing, working capital, SBA |
| Plastics & Injection Molding | Injection molding machines, resin inventory | Equipment financing, working capital |
| Electronics & Assembly | Component inventory, assembly equipment, large contracts | PO financing, invoice factoring, working capital |
| Aerospace & Defense | Specialized equipment, long production cycles | SBA loan, equipment financing, PO financing |
| Furniture & Wood Products | CNC routers, finishing equipment, lumber | Equipment financing, working capital |
| Printing & Packaging | Digital/offset presses, paper inventory | Equipment financing, working capital, LOC |
| Textiles & Apparel | Sewing machines, fabric inventory, large retail orders | PO financing, invoice factoring, working capital |
Manufacturing Cash Flow Cycle
Real-World Scenarios
CNC Machine Expansion
A precision machining shop has a 6-month backlog. A second 5-axis CNC machine at $220,000 would eliminate it and enable $1.8M in additional annual contracts. Equipment financing at 10% over 5 years = $4,680/month. The additional contracts add $150,000/month — a 32x monthly payment multiple.
Large Contract Working Capital
A food packaging manufacturer wins a $950,000 contract requiring $180,000 in materials upfront. Customer pays Net-60. A $180,000 working capital loan at 18% over 6 months = $4,200/month. The contract nets $285,000 in gross margin. Net after financing: $259,200.
Invoice Factoring for Cash Flow
A metal fabricator has $480,000 in outstanding invoices on Net-60/90 terms. Payroll is due in 10 days: $85,000. Invoice factoring at 2.5%/30 days on $480,000 = $12,000 cost. Payroll made, materials purchased, operations continue.
Equipment Emergency
An injection molding company's primary press fails mid-production on a $650,000 automotive contract. Replacement: $340,000. Equipment financing approved in 4 days. Press operational in 2 weeks. Contract delivered on time. Monthly payment $6,200 over 6 years, covered 100x by contract revenue.
How It Compares
| Product | Speed | Rate | Best For |
|---|---|---|---|
| Equipment Financing | 3–7 days | 6%–20% APR | Machinery, production equipment |
| Working Capital Loan | 2–5 days | 15%–40% APR | Raw materials, production cycles |
| PO Financing | 1–5 days | 2%–6%/30 days | Large contract fulfillment |
| Invoice Factoring | 24–72 hours | 1%–4%/30 days | Eliminate receivables wait |
| SBA 7(a) Loan | 4–8 weeks | Prime + 2.75–4.75% | Best rates, expansion |
Apply for Manufacturing Financing Today
Join manufacturers across the U.S. who chose Crestmont Capital.
Apply Today →Tips for Getting Approved
- Have contracts and POs ready: Verified purchase orders dramatically strengthen manufacturing applications by demonstrating revenue visibility.
- Know your AR aging: For invoice factoring, lenders evaluate the creditworthiness of your customers. Fortune 500 customers in your AR is highly fundable regardless of your own credit.
- Equipment quotes accelerate financing: A formal vendor quote for the specific machine speeds underwriting significantly.
- Understand your production cycle: Know your cash cycle length — 45-day production + Net-60 customer terms = 105-day cash cycle. Demonstrating this awareness strengthens applications.
- Separate business and personal banking: Commingled accounts obscure the true financial picture. Clean business banking is essential for fast underwriting.
- Consider the full capital stack: Equipment financing for machinery, PO financing for large contracts, and a line of credit for ongoing working capital each serve distinct needs more efficiently than one product trying to do everything.
Why Choose Crestmont Capital
Crestmont Capital provides manufacturing financing access across the full spectrum — equipment, working capital, PO financing, invoice factoring, SBA, and lines of credit — through a single application. We understand production cycles, contract-based revenue, and equipment collateral values.
- Manufacturing expertise: We understand production cycles, Net-30/60/90 terms, and how to read manufacturing financials correctly.
- Full product access: Equipment, working capital, PO financing, factoring, SBA, and LOC through one application.
- Fast decisions: Most manufacturing decisions in 2-5 business days; invoice factoring in 24-72 hours.
Related: equipment financing, purchase order financing, invoice factoring, SBA loans.
Frequently Asked Questions
What types of manufacturing businesses can get loans?
All manufacturing sectors: metal fabrication, food processing, plastics, electronics, aerospace, furniture, printing, textiles, and more. The key factors are annual revenue ($500K+) and documented production history.
What is purchase order financing?
PO financing advances 50-90% of a verified purchase order's value to fund material costs. When the customer pays, the advance is repaid. It turns large contract wins into capital opportunities rather than cash flow crises.
How does invoice factoring help manufacturers?
Invoice factoring advances 80-90% of outstanding invoices immediately. No credit minimum — your customer's creditworthiness drives approval. Standard in manufacturing due to Net-30/60/90 payment terms.
What credit score is needed for manufacturing loans?
620+ for most conventional products. Equipment financing at 580+ with collateral. Invoice factoring and PO financing have no credit minimum. SBA loans prefer 680+.
How much can a manufacturer borrow?
$50,000 to $5,000,000+. Equipment loans sized to equipment value (80-90% LTV). Working capital sized to 3-6 months of operating expenses. PO financing sized to individual purchase orders.
What operating history is needed to qualify?
What documentation is needed?
Core: 2 years business tax returns, 6-12 months bank statements, AR aging report (for factoring), current purchase orders (for PO financing or working capital sizing), equipment quotes (for equipment financing).
Is manufacturing considered high-risk?
Moderate risk — lower than hospitality or retail because production contracts provide revenue visibility, equipment provides collateral, and B2B customer bases are stable. Primary risks are equipment obsolescence and single-customer concentration.
Invest in Your Manufacturing Business
Fast decisions. Manufacturing expertise. Apply now with Crestmont Capital.