Locksmithing is one of the oldest skilled trades in the country, and in 2026 it is also a quietly modernizing industry. Roughly 28,000 locksmith businesses operate across the United States, generating an estimated $3 billion in annual revenue, and nearly every one of them relies on outside capital at some point to fund service vans, key-cutting machinery, automotive programming tools, and day-to-day working capital.
This report compiles the most current locksmith business financing statistics for 2026, drawing on data from the U.S. Bureau of Labor Statistics, the U.S. Census Bureau, the U.S. Small Business Administration, and industry lending benchmarks. Whether you own a mobile lockout service, a retail key shop, or a commercial security operation, the numbers below show what the industry looks like, what it costs to run, and how locksmith businesses are funding growth this year.
In This Article
- The Locksmith Industry at a Glance
- Market Size and Revenue Statistics
- Locksmith Employment and Wage Statistics
- Startup and Operating Cost Statistics
- Locksmith Business Financing Statistics
- Top Financing Options for Locksmith Businesses
- 2026 Trends Shaping Locksmith Financing
- How Crestmont Capital Helps Locksmith Businesses
- Real-World Financing Scenarios
- Frequently Asked Questions
- How to Get Started
The Locksmith Industry at a Glance in 2026
The U.S. locksmith industry is large, fragmented, and remarkably durable. Industry estimates built on U.S. Census Bureau County Business Patterns data place the number of locksmith businesses at roughly 28,000 to 29,000 nationwide, employing more than 40,000 working technicians when self-employed operators are included. The vast majority of these businesses are small, owner-operated companies with fewer than ten employees, and a significant share are mobile-only operations run from a service van rather than a storefront.
Locksmith revenue generally falls into three segments:
- Residential services: lockouts, rekeying, lock replacement, and increasingly smart lock installation for homeowners and property managers.
- Commercial services: master key systems, panic hardware, access control installation, and ongoing security contracts for offices, retail, and industrial facilities.
- Automotive services: car lockouts, transponder key programming, and key fob replacement, which now account for an estimated 35 to 40 percent of total industry revenue.
What makes locksmithing unusual among the trades is its recession resistance. People lock themselves out of homes, cars, and offices in every economy, and security upgrades tend to continue even when construction slows. That steady demand profile is one reason lenders generally view established locksmith businesses as credible borrowers.
Key Stat: The U.S. locksmith industry generates an estimated $3.0 to $3.1 billion in annual revenue, spread across roughly 28,000 businesses, with automotive key services alone accounting for an estimated 35 to 40 percent of that total.
Locksmith Market Size and Revenue Statistics
Industry analysts value the U.S. locksmith and security services market at approximately $3.0 to $3.1 billion in 2025 and 2026. Growth has been modest in raw dollar terms but meaningful in mix: traditional mechanical lock work is flat to declining, while electronic access control, smart lock installation, and automotive key programming are expanding at a double-digit annual pace.
Dividing the market across the business base yields an implied average revenue of roughly $105,000 to $110,000 per locksmith business. That average masks a wide spread. A solo mobile operator running lockout calls may gross $60,000 to $90,000 per year, while a multi-technician commercial shop with access control contracts can exceed $500,000 in annual revenue. Industry operator surveys commonly place established full-time locksmiths in the $75,000 to $150,000 revenue range, with top commercial operations well above that.
Average ticket sizes have climbed steadily:
- Standard lockout service calls: typically $85 to $250 depending on market and time of day.
- Residential rekey or lock replacement: commonly $100 to $300 per visit.
- Automotive key replacement and programming: $150 to $600 or more for proximity fobs and push-to-start systems.
- Commercial access control projects: frequently $2,500 to $25,000 per installation, with recurring service revenue attached.
The pricing power in the industry has shifted toward technicians who can handle electronic and automotive work, which is exactly the work that requires the most expensive equipment. That connection between capability and capital is the thread running through nearly all of the financing statistics later in this report.
Locksmith Employment and Wage Statistics
According to the U.S. Bureau of Labor Statistics Occupational Employment and Wage Statistics program, locksmiths and safe repairers (SOC code 49-9094) earned a median annual wage of $48,380 as of the most recent full national survey, equivalent to roughly $23.26 per hour. The BLS counts approximately 14,000 to 15,000 wage-and-salary locksmith positions, a figure that excludes the large population of self-employed mobile operators, which is why industry estimates of total working locksmiths run closer to 40,000.
Wages vary widely by specialization and employer type:
| Earnings Percentile | Hourly Wage | Annual Wage |
|---|---|---|
| 10th percentile (entry level) | ~$15.20 | ~$31,620 |
| 25th percentile | ~$18.25 | ~$37,950 |
| 50th percentile (median) | ~$23.26 | ~$48,380 |
| 75th percentile | ~$29.84 | ~$62,070 |
| 90th percentile (top earners) | ~$36.76 | ~$76,460 |
Locksmiths employed by government agencies, universities, hospitals, and large facilities operations consistently earn above the national median, frequently in the $61,000 to $63,000 range. Self-employed owners who specialize in automotive transponder work, safe and vault service, or commercial access control typically out-earn generalists, which is a major reason owners invest in advanced equipment and training.
The BLS projects flat to slightly declining employment for traditional locksmithing over the coming decade, driven by the adoption of keyless entry and smart home systems. In practice, that projection understates opportunity for shop owners: every smart lock, keypad, and access panel installed is a service call, and the technicians who can install and service electronic systems are seeing demand grow rather than shrink. For business owners, the wage data matters for another reason: hiring a qualified technician now costs $45,000 to $60,000 per year in wages alone, which makes payroll financing and working capital planning a central part of running a locksmith company.
Need Capital for Your Locksmith Business?
From key-cutting machines to service vans, Crestmont Capital funds the equipment that keeps locksmiths working. Apply in minutes.
Apply Now →Locksmith Startup and Operating Cost Statistics
One of the most searched questions in this niche is what it costs to get started. The answer depends heavily on business model, but current industry data and franchise disclosures converge on consistent ranges. A mobile-only locksmith startup typically requires $10,000 to $30,000 in initial capital, while a retail storefront operation with showroom inventory and build-out can require $40,000 to $75,000 or more.
The major cost categories break down as follows:
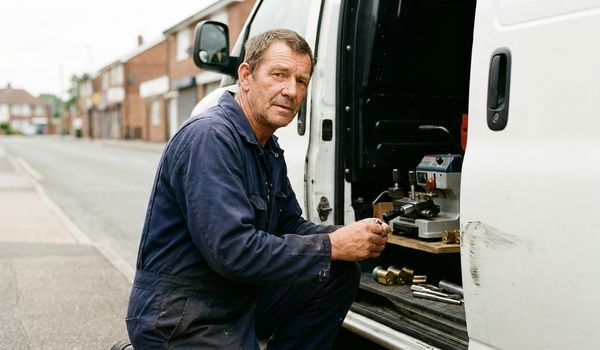
- Service vehicle: A new cargo van runs $25,000 to $45,000, while a reliable used van can be acquired for $10,000 to $25,000. The van is usually the single largest startup expense for a mobile operation.
- Key-cutting machinery: Basic key duplicators cost $1,500 to $3,000, while computerized laser key machines and decoders run $5,000 to $15,000.
- Automotive programming equipment: EEPROM programmers, transponder tools, and diagnostic interfaces for modern vehicle keys cost $3,000 to $10,000, with software subscriptions adding ongoing expense.
- Lock and hardware inventory: An opening stock of residential and commercial locks, cylinders, and hardware typically runs $2,000 to $8,000.
- Licensing, bonding, and insurance: Depending on state requirements, expect $500 to $3,000 in the first year, with commercial general liability and commercial auto policies forming the largest ongoing share.
- Working capital: Prudent owners hold two to three months of operating expenses in reserve, which for a small operation means $8,000 to $20,000.
Ongoing monthly operating costs for a one-van mobile locksmith business generally fall between $3,500 and $7,000, covering fuel, insurance, phone and dispatch software, inventory replenishment, advertising, and vehicle or equipment loan payments. Advertising deserves special mention: locksmithing is one of the most competitive local search categories in the country, and many operators report spending $1,000 to $3,000 per month on pay-per-click and local service ads just to keep call volume steady.
Pro Tip: Because the service van and key-cutting equipment are hard assets with resale value, they are the easiest startup costs to finance. Lenders routinely fund 100 percent of a van or machine purchase for qualified buyers, preserving cash for insurance, advertising, and payroll.
Locksmith Business Financing Statistics: Approval Rates, Amounts, and Terms
This is the core of the report: how locksmith businesses actually fund vehicles, equipment, and operations in 2026. The numbers below come from small business lending indexes, SBA program data, and equipment finance industry benchmarks.
Approval Rates by Lender Type
Small business loan approval rates remain split sharply by lender category. Monthly small business lending indexes have consistently shown big banks approving roughly 13 to 15 percent of small business applications, small and regional banks approving around 18 to 20 percent, and alternative and online lenders approving 28 percent or more of applicants. Equipment financing approval rates run meaningfully higher across the board because the loan is secured by a tangible asset: industry benchmarks place equipment finance approval in the 60 to 70 percent range for applicants with fair to good credit, and specialty lenders work with credit profiles banks will not touch.
For locksmith businesses specifically, approval odds benefit from three factors lenders like: an essential, recession-resistant service; hard assets (vans and machinery) that secure the debt; and transaction-level cash flow that shows up clearly in bank statements. Established locksmith businesses with two or more years of revenue history are among the more fundable categories in the service trades.
Typical Loan Amounts
Locksmith financing requests cluster into predictable bands:
- $5,000 to $15,000: key-cutting machines, automotive programming tools, and opening inventory for new mobile operators.
- $15,000 to $50,000: service van purchases, full equipment packages, and shop build-outs.
- $50,000 to $150,000: multi-vehicle fleet additions, retail location expansion, and access control division launches.
- $150,000 and above: acquisitions of established locksmith companies and multi-location rollouts.
For context, the SBA's flagship 7(a) loan program backed tens of thousands of loans in fiscal 2024 with an average size of roughly $440,000, while the SBA microloan program averaged around $13,000 to $14,000 per loan, a band that aligns closely with locksmith startup equipment packages. Most locksmith operators land somewhere between those two poles, and most fund through equipment financing or working capital products rather than full SBA loans.
Rates and Terms
Pricing depends on credit strength, time in business, and collateral, but current market ranges look like this:
- Bank and SBA loans: roughly 6 to 11 percent for well-qualified borrowers, with terms of 5 to 10 years.
- Equipment financing: factor-based pricing that typically translates to effective rates of 8 to 20 percent, with terms of 24 to 72 months matched to the useful life of the van or machine.
- Online term loans and working capital: the widest range, roughly 10 to 30 percent or more depending on credit and revenue, with terms of 6 to 24 months.
- Business lines of credit: revolving facilities commonly priced between 10 and 25 percent, drawn only as needed.
The pattern across all of these statistics is consistent: locksmith businesses pay for speed and flexibility, and the cheapest capital goes to owners with two-plus years in business, 650-plus credit, and documented revenue. Newer operators pay more but still get funded, particularly when the money is buying an asset that generates revenue directly, like a van or a laser key machine.
Top Financing Options for Locksmith Businesses
Matching the product to the purpose is where most owners either save or waste thousands of dollars. Here is how the main options compare for locksmith-specific needs:
| Financing Option | Best For | Typical Amounts | Typical Terms |
|---|---|---|---|
| Equipment financing | Key machines, programming tools, shop equipment | $5,000 to $150,000 | 24 to 72 months |
| Commercial van financing | New or used service vans and fleet vehicles | $10,000 to $60,000 | 36 to 72 months |
| Business line of credit | Payroll gaps, inventory, ad spend, slow seasons | $10,000 to $250,000 | Revolving, draw as needed |
| SBA loans | Acquisitions, real estate, large expansions | $50,000 to $5 million | 5 to 25 years |
| Working capital loans | Fast cash for marketing, hiring, or bridging receivables | $10,000 to $500,000 | 6 to 24 months |
For a deeper dive into loan structures, our complete guide to locksmith business loans walks through qualification requirements and application strategy, and our guide to locksmith van equipment financing covers vehicle funding in detail.
By the Numbers
Locksmith Business Financing - Key Statistics for 2026
$3.0B+
Estimated U.S. locksmith industry revenue
$48,380
BLS median annual wage for locksmiths and safe repairers
60-70%
Equipment financing approval rate for qualified applicants
28,000+
Locksmith businesses operating in the United States
2026 Trends Shaping Locksmith Financing
Several forces are changing what locksmith businesses buy and how they pay for it this year.
The Shift to Electronic Access Control
The fastest-growing revenue segment in the industry is electronic: smart locks, keypads, card readers, mobile credential systems, and cloud-managed access control. Commercial clients increasingly expect their locksmith to function as a security technology contractor, not just a key cutter. That shift is capital intensive. Access control inventory, test equipment, and manufacturer certifications require upfront investment, and industry data shows shops that add electronic services typically raise average tickets from the low hundreds into the thousands per job.
Automotive Complexity Keeps Raising the Equipment Bar
Modern vehicles have turned automotive locksmithing into a programming business. Replacing a proximity fob or programming a transponder on a current-model vehicle requires EEPROM-capable tools, current software subscriptions, and diagnostic interfaces that can cost more than a basic shop's entire tool chest did a decade ago. Automotive work already represents an estimated 35 to 40 percent of industry revenue, and the equipment spend required to capture it is the single most common reason locksmith businesses seek equipment financing in 2026.
Vehicle Costs Remain Elevated
Commercial van prices have stayed well above pre-2020 levels, which has pushed more locksmith operators toward financing rather than cash purchases. Lenders report continued strong volume in commercial vehicle funding across the service trades, and locksmith businesses are no exception. Financing the van preserves cash for the equipment and advertising that actually generate calls.
Lenders Are Funding Technology Upgrades, Not Just Hard Iron
A notable 2026 pattern, consistent with broader small business lending coverage from outlets like Forbes Advisor's small business loan desk: equipment lenders have broadened what counts as fundable. Software subscriptions bundled with hardware, training and certification costs tied to an equipment purchase, and even shop management platforms are increasingly financeable alongside the traditional van and key machine. For owners, that means a single financing arrangement can cover an entire capability upgrade rather than just one machine.
How Crestmont Capital Helps Locksmith Businesses
Crestmont Capital is the #1 rated business lender in the United States, and locksmith businesses are a category we fund regularly. The financing statistics above translate directly into the products our locksmith clients use most:
- Equipment financing for key-cutting machines, automotive programming tools, and shop equipment, with terms matched to the useful life of the asset and approvals that weigh the equipment's value alongside your credit.
- Commercial van financing for new and used service vehicles, including fleet additions for growing operations.
- Business lines of credit for smoothing the gap between completing commercial jobs and collecting payment, covering payroll during slow stretches, or stocking inventory ahead of a busy season.
- Working capital loans for fast-moving needs like advertising pushes, hiring a technician, or covering an unexpected expense without draining reserves.
Our application takes minutes, decisions come back fast, and funding can arrive in days rather than the weeks a bank or SBA process requires. For locksmith owners, that speed matters: when a key machine fails or a van breaks down, every day without it is lost revenue.
Fund Your Next Van, Machine, or Hire
Locksmith businesses get fast decisions and flexible terms from Crestmont Capital. See your options with a quick application.
Get Funded →Real-World Locksmith Financing Scenarios
Statistics are more useful in context. These five scenarios reflect the most common ways locksmith businesses put financing to work, based on typical deal sizes and terms in the current market.
Scenario 1: The Solo Operator Adding a Second Van
A mobile locksmith in a growing suburb has more calls than one van can handle. He finances a $32,000 cargo van and a $7,500 laser key machine on a single 60-month equipment financing arrangement. The combined payment runs roughly $800 per month, and the second van, staffed by a hired technician, generates an additional $6,000 to $9,000 per month in gross revenue within its first quarter. The financing converts a capacity ceiling into a growth step without touching his cash reserves.
Scenario 2: The Shop Owner Investing in Automotive Programming
A retail locksmith shop watches automotive key replacement calls walk out the door because it lacks EEPROM programming capability. The owner finances $9,000 in programming equipment and software over 36 months. Automotive key jobs at $150 to $600 each quickly cover the roughly $320 monthly payment, and the shop's average ticket climbs as word spreads that it handles push-to-start vehicles other shops turn away.
Scenario 3: The Career-Changer Launching a Mobile Business
A newly certified locksmith leaves a facilities job to start a mobile lockout service. With limited business history, a bank loan is out of reach, but a $25,000 startup package covering a used van, a duplicator, and opening inventory funds through a specialty equipment lender based on the asset values and his personal credit. He keeps his remaining $12,000 in savings as a working capital buffer while call volume builds.
Scenario 4: The Established Shop Expanding into Access Control
A three-technician commercial locksmith company wins a property management contract that requires access control installation. It uses a $75,000 term loan to buy access control inventory, test equipment, and manufacturer certifications. Commercial project tickets jump from the hundreds into the $5,000 to $20,000 range, and the recurring service agreements attached to each installation create predictable monthly revenue that more than services the debt.
Scenario 5: The Emergency Service Smoothing Cash Flow
A 24/7 emergency lockout company has strong revenue but lumpy timing: commercial clients pay net-30 while technicians are paid weekly. The owner secures a $50,000 business line of credit, drawing against it to cover payroll during collection gaps and repaying it when invoices clear. Interest accrues only on the drawn balance, and the facility removes the cash-flow anxiety that used to dictate which jobs he could accept.
Frequently Asked Questions
How much does it cost to start a locksmith business in 2026? +
A mobile-only locksmith startup typically requires $10,000 to $30,000, covering a used or financed van, key-cutting machinery, opening inventory, licensing, and insurance. A retail storefront operation runs $40,000 to $75,000 or more once build-out and showroom inventory are included. Financing the van and equipment preserves most of that capital as working reserve.
How much do locksmiths make per year? +
The BLS reports a median annual wage of $48,380 for locksmiths and safe repairers, with entry-level positions near $31,620 and top earners above $76,460. Self-employed owners who specialize in automotive programming or commercial access control frequently earn more, and owner income scales with business revenue rather than an hourly wage.
What is the average revenue of a locksmith business? +
With industry revenue near $3 billion across roughly 28,000 businesses, the implied average is about $105,000 to $110,000 per business. Solo mobile operators often gross $60,000 to $90,000, established full-time shops commonly land in the $75,000 to $150,000 range, and multi-technician commercial operations can exceed $500,000 annually.
Can a locksmith business get an SBA loan? +
Yes. Locksmith businesses qualify for SBA 7(a) and microloan programs like any other eligible small business. SBA loans offer the lowest rates and longest terms but require strong credit, solid documentation, and patience: the process typically takes several weeks. Many locksmith owners use SBA loans for acquisitions or major expansions and faster products for equipment and working capital.
What credit score do you need for locksmith equipment financing? +
Most equipment lenders look for scores of 650 or higher for their best pricing, but approvals happen well below that threshold because the equipment itself secures the loan. Borrowers in the 550 to 650 range routinely get funded at higher rates, particularly when the equipment is a revenue-producing asset like a service van or key machine.
How much can a locksmith business borrow? +
Borrowing capacity tracks revenue and purpose. Small equipment deals start around $5,000, van and equipment packages commonly run $15,000 to $50,000, and established operations fund expansions of $75,000 to $150,000 or more. Acquisitions of existing locksmith companies can reach into seven figures through SBA or commercial financing structures.
What interest rates do locksmith business loans carry? +
Well-qualified borrowers see bank and SBA pricing around 6 to 11 percent. Equipment financing typically translates to effective rates of 8 to 20 percent depending on credit and asset type. Online term loans and working capital products range from roughly 10 to 30 percent or more, trading higher cost for speed and easier qualification.
Is it hard for a locksmith to get a business loan? +
It depends on the lender. Big banks approve only about 13 to 15 percent of small business applications, so a bank denial is common and not disqualifying. Alternative and specialty lenders approve a much higher share, and equipment financing approval rates run 60 to 70 percent for applicants with fair to good credit because the loan is asset-backed. Locksmithing's essential-service demand profile works in the borrower's favor.
What equipment can a locksmith business finance? +
Virtually everything in the trade: key duplicators and laser cutting machines, EEPROM and transponder programming tools, diagnostic interfaces, safe and vault equipment, service vans, and shop machinery. Many lenders now also fund software subscriptions, training, and certification costs when bundled with an equipment purchase.
How long are typical terms on locksmith equipment loans? +
Equipment financing terms usually run 24 to 72 months, matched to the expected useful life of the asset. Vans commonly finance over 36 to 72 months, key machines over 36 to 60 months, and smaller tool packages over 24 to 36 months. Longer terms lower the monthly payment but increase total interest paid.
Do locksmiths need a license to get business financing? +
Licensing rules vary by state, and lenders do not typically require a locksmith license itself. What they do require is a registered business entity, a business bank account, and documentation of revenue. Being properly licensed and insured strengthens an application indirectly by demonstrating a legitimate, established operation.
Can a brand-new locksmith business get financing with no revenue history? +
Yes, primarily through equipment financing. Because the van or machine secures the debt, specialty lenders will fund startups based on personal credit, a down payment, and the asset's value. Unsecured working capital without revenue history is much harder, so most new operators finance assets first and add credit lines once they have six to twelve months of bank statements.
What is the best way to finance a locksmith service van? +
Commercial vehicle financing is purpose-built for this. Terms of 36 to 72 months keep payments manageable, the van itself serves as collateral, and qualified buyers can finance 100 percent of the purchase price. For used vans or buyers with credit challenges, equipment lenders who specialize in service-trade vehicles offer the most flexible approvals.
How fast can a locksmith business get funded? +
Online and specialty lenders routinely deliver decisions within 24 hours and funding within one to three business days for equipment and working capital. Bank and SBA loans take considerably longer, often four to eight weeks from application to funding. For an urgent need like a broken key machine or a down van, speed-focused lenders are the practical choice.
How does a business line of credit work for a locksmith company? +
A line of credit gives you an approved pool of capital you draw from as needed and repay on a revolving basis, with interest charged only on the outstanding balance. Locksmith businesses typically use lines of $10,000 to $250,000 to cover payroll during collection gaps, replenish inventory, fund advertising pushes, or handle seasonal slowdowns without reapplying for a new loan each time.
Ready to Put These Numbers to Work?
Join the thousands of trade businesses funded by the #1 business lender in the U.S. Fast decisions, flexible terms, real people.
Apply Now →How to Get Started
Complete our quick application at offers.crestmontcapital.com/apply-now - takes just a few minutes.
A Crestmont Capital advisor will review your needs and match you with the right financing option for your locksmith business.
Receive your funds and put them to work - often within days of approval.
Conclusion
The locksmith business financing statistics for 2026 describe an industry that is stable at its core and modernizing at its edges. A $3 billion market, 28,000-plus businesses, median wages near $48,000, and an accelerating shift toward electronic and automotive work create steady demand for capital, and lenders have responded with equipment financing, vehicle loans, lines of credit, and working capital products matched to how locksmiths actually operate.
For owners, the playbook is consistent: finance revenue-producing assets like vans and key machines, keep a credit line for cash-flow gaps, and reserve the cheapest capital, whether bank or SBA, for the big moves. Crestmont Capital funds locksmith businesses at every stage, from the first used van to multi-vehicle expansions and access control division launches.
The data points in this report will be updated as new BLS, Census Bureau, and SBA figures are released throughout 2026. Bookmark this page, and when you are ready to fund your next step, our team is here to help.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.

Allan Garfinkle
Allan Garfinkle is the Chief Revenue Officer at Crestmont Capital, where he has spent more than a decade leading revenue strategy, business development, and operational growth. With 28 years of experience building and advising startups and small businesses, Allan has helped more than 10,000 business owners navigate financing decisions, growth opportunities, and changing economic conditions. He earned a Bachelor of Science in Economics and an MBA with a concentration in Finance from Northeastern University, as well as a Juris Doctor from New England Law, where his studies focused on contracts and business law. His writing draws on extensive practical experience in small-business lending, equipment financing, business credit, and commercial finance.