
 (800) 949-0401
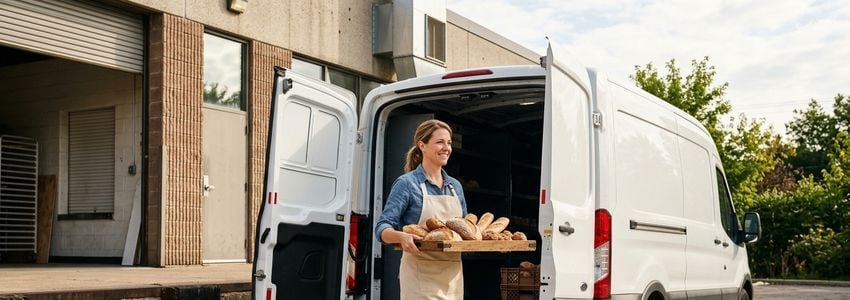
Commercial Van Financing for Bakery Delivery Fleets: The Complete Guide for Bakery Owners
Commercial van financing is the fastest and most practical way for bakery owners to fund cargo vans, sprinter vans, and box trucks used for wholesale routes, catering runs, and retail deliveries without draining working capital.
A growing bakery rarely fails because the ovens stop working. It fails because the bread, cakes, and pastries never make it out the door and into the hands of grocery buyers, cafe accounts, and catering clients. Once a bakery lands its first few wholesale or subscription accounts, a single delivery vehicle stops being a convenience and becomes the backbone of the business. Missed delivery windows mean lost accounts, spoiled product, and a reputation that is hard to rebuild in a tight-knit food service community.
This guide breaks down exactly how commercial van financing works for bakery delivery fleets, which vehicles make sense for different stages of growth, what lenders look for, and how to compare financing against leasing or a line of credit. Whether you are buying your first refrigerated cargo van or expanding a six-vehicle wholesale delivery fleet, the goal is the same: get the right vehicle on the road without disrupting cash flow.
In This Article
What Is Commercial Van Financing?
Commercial van financing is a type of business loan or lease designed specifically to fund the purchase of vans, sprinter vans, cargo vans, and light-to-medium box trucks used for business operations. Instead of paying the full sticker price for a delivery vehicle out of pocket, a bakery owner borrows the funds (or leases the vehicle) and repays the lender over a fixed term, typically with a monthly payment that is structured around predictable cash flow.
For a bakery, this usually means financing a vehicle that will be used to transport bread, cakes, pastries, and other perishable goods from the commercial kitchen to grocery stores, coffee shops, restaurants, farmers markets, or directly to residential and corporate catering clients. The vehicle itself typically serves as collateral for the loan, which is one reason approval standards for commercial van financing are often more flexible than an unsecured working capital loan.
Unlike a general-purpose business loan, van financing is tied directly to a specific asset. That structure benefits both the lender, who has collateral to secure the loan, and the bakery owner, who often qualifies for better rates and terms than they would with unsecured credit.
Key Stat: Small businesses make up the overwhelming majority of commercial fleet operators in the United States, and industry research shows the large majority of these fleets run fewer than 10 vehicles, according to fleet industry data. That means most bakery delivery operations are financing one, two, or a handful of vehicles at a time, not a massive corporate fleet, and lenders who specialize in small business vehicle financing are built to serve exactly that scale.
Key Benefits of Commercial Van Financing for Bakery Owners
Financing a delivery van or box truck rather than paying cash preserves the working capital a bakery needs for ingredients, payroll, rent, and unexpected repairs. It also lets a growing bakery scale its delivery capacity in step with new accounts, rather than waiting until enough cash has been saved to buy a vehicle outright.
- Preserves working capital. Cash stays available for flour, dairy, packaging, and payroll instead of being tied up in a single vehicle purchase.
- Predictable monthly payments. Fixed-rate financing makes it easy to budget delivery costs against wholesale and catering revenue.
- Faster fleet expansion. A bakery that lands three new grocery accounts in the same month does not have to wait to save up for a second van.
- Access to newer, more reliable vehicles. Financing often makes it possible to buy a newer or better-equipped van than a bakery could afford in cash.
- Flexible terms for used or new vehicles. Many lenders will finance both new and used cargo vans, sprinter vans, and box trucks.
- Builds business credit. On-time payments on a commercial vehicle loan can strengthen a bakery's credit profile for future financing needs.
Ready to Get Your Next Delivery Van on the Road?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation, apply in minutes.
Apply Now →How Commercial Van Financing Works
The process of financing a bakery delivery vehicle follows a fairly consistent path regardless of which lender a business owner chooses, though timelines and documentation requirements vary between traditional banks and specialty commercial lenders.
1. Identify the vehicle and its cost. Most bakeries start by identifying whether they need a compact cargo van for local retail drop-offs, a sprinter van for larger wholesale routes, or a box truck for high-volume catering and grocery distribution. The purchase price, whether new or used, determines the loan amount needed.
2. Submit a financing application. Applications typically require basic business information, the vehicle details (make, model, year, mileage for used vehicles), and financial documentation. Specialty commercial lenders often streamline this into a short online application.
3. Underwriting and approval. The lender reviews the bakery's time in business, revenue, credit profile, and the vehicle itself. Because the vehicle secures the loan, approval decisions can move faster than unsecured lending products.
4. Down payment and terms. Many commercial van financing deals require a down payment, though the amount varies significantly by lender, vehicle age, and borrower credit profile. Loan terms commonly range from 36 to 72 months, with some lenders extending to longer terms for higher-value box trucks.
5. Funding and delivery. Once approved, funds are typically disbursed directly to the dealer or seller, and the bakery takes possession of the vehicle, often within days rather than weeks.
6. Repayment. The bakery makes fixed monthly payments over the loan term. At the end of the term (for a loan structure), the bakery owns the vehicle outright.
By The Numbers
Commercial Vehicle Financing — Key Industry Statistics
$24.5B
Estimated size of the U.S. commercial vehicle financing market
70%
Share of small business fleets that operate fewer than 10 vehicles
60%+
Share of recent truck and van financing deals involving used vehicles
60 Mo.
Most common commercial vehicle financing term length
Vehicle Types for Bakery Delivery Fleets
Not every bakery needs the same delivery vehicle. The right choice depends on route length, order volume, whether goods need temperature control, and how many stops a driver makes per shift.
Cargo Vans
Compact cargo vans are the entry point for most bakeries just starting wholesale or catering delivery. They are affordable to finance, easy to maneuver in urban delivery zones, and sufficient for a bakery making a handful of daily stops to local cafes or farmers markets.
Sprinter Vans
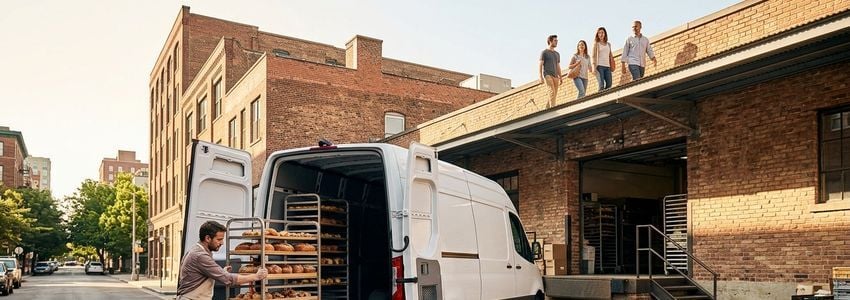
Sprinter-style vans offer significantly more interior cargo space and, in many configurations, standing height for the driver. They are a popular choice for bakeries that need shelving systems to organize trays of bread, cakes, and pastries across a longer multi-stop wholesale route.
Box Trucks
For bakeries supplying grocery chains, large catering operations, or multiple retail accounts on a single route, a box truck provides the cargo volume needed to move high order quantities efficiently. Box trucks are also the more practical option for bakeries that need built-in refrigeration units to keep dairy-based fillings, cream cakes, or perishable ingredients at safe temperatures.
Refrigerated Conversions
Some bakeries finance a standard cargo van or box truck and then add a refrigerated conversion afterward, while others finance a vehicle that already includes temperature-controlled cargo space. Either approach can typically be rolled into the same financing package, depending on the lender.
Who Commercial Van Financing Is Best For
Commercial van financing tends to make the most sense for bakery owners in a few specific situations.
- Bakeries adding their first wholesale or catering delivery route and need a dedicated vehicle instead of relying on a personal car.
- Growing bakeries that have outgrown a single small van and need a second vehicle or a larger box truck to keep up with new accounts.
- Bakeries replacing an aging delivery vehicle that has become unreliable or too costly to maintain.
- Multi-location bakery operators who need to move product between commissary kitchens, retail locations, and wholesale clients.
- Seasonal bakery businesses gearing up for high-volume periods like holidays or wedding cake season, when delivery capacity becomes a bottleneck.
It is generally a poor fit for a bakery that only needs occasional, low-volume deliveries and can manage with an existing personal vehicle, since the fixed monthly payment only makes financial sense when the vehicle is generating consistent business value.
Bakery owners should also weigh where the business is heading over the next year, not just where it stands today. A bakery that just signed its first grocery chain contract, for example, is likely to add more retail locations to that same route within a matter of months. Financing a vehicle with enough cargo capacity and route flexibility to absorb that near-term growth is usually more cost-effective than financing a smaller van now and having to finance a second vehicle again soon after.
Financing vs. Leasing vs. Other Options
Bakery owners generally have three realistic paths to getting a delivery vehicle on the road: a commercial van loan, a vehicle lease, or drawing on a business line of credit. Each comes with different tradeoffs around ownership, monthly cost, and flexibility.
| Feature | Van Financing (Loan) | Vehicle Leasing | Business Line of Credit |
|---|---|---|---|
| Ownership at end of term | Yes, vehicle is owned outright | No, unless a buyout option is exercised | Yes, if used to purchase the vehicle |
| Monthly payment | Fixed, based on loan amount and term | Often lower than loan payments | Variable, based on draw amount |
| Best for | Long-term fleet ownership | Businesses that upgrade vehicles frequently | Flexible, smaller or unplanned purchases |
| Mileage restrictions | None | Often yes, with overage fees | None |
For most bakeries planning to keep a delivery vehicle for the long haul and rack up significant delivery mileage, financing typically makes more sense than leasing, since bakery delivery routes often involve heavy daily mileage that can trigger lease overage penalties. A business line of credit can work well as a bridge for a smaller, lower-cost used vehicle, but a dedicated vehicle loan is usually the more structured and predictable path for a primary delivery van or box truck.
How Crestmont Capital Helps Bakery Owners Finance Delivery Vehicles
Crestmont Capital works with bakery owners to structure commercial van financing around the realities of a food delivery business, including seasonal revenue swings, tight margins, and the need to move quickly when a new wholesale account requires additional delivery capacity.
Whether a bakery needs financing for a single cargo van or a small fleet of box trucks, Crestmont's commercial vehicle financing programs are built to accommodate both new and used vehicle purchases. For bakeries that also need to fund ovens, mixers, or refrigeration equipment alongside a delivery vehicle, bakery equipment financing can often be structured together with vehicle financing to simplify the process into a single application.
Crestmont's underwriting process looks beyond a simple credit score, considering a bakery's overall revenue trends, time in business, and the practical value of the vehicle as collateral. That approach allows many bakery owners, including those with less-than-perfect credit or a relatively short operating history, to access financing that a traditional bank might decline.
Pro Tip: If your bakery is financing its first delivery vehicle, consider sizing the van or truck for your anticipated route volume in 12 to 18 months, not just current demand. Refinancing or adding a second vehicle later is possible, but starting with a vehicle that has some growth room can reduce the need for a second financing round soon after the first.
Real-World Scenarios
Scenario 1: The New Wholesale Account. A small artisan bakery lands its first grocery store wholesale contract, requiring daily deliveries of fresh bread six days a week. The owner finances a used cargo van rather than depleting cash reserves needed for the increased flour and packaging orders that come with the new account.
Scenario 2: Replacing an Unreliable Vehicle. A bakery's aging delivery van breaks down twice in one month, causing a missed delivery to a key catering client. The owner finances a newer sprinter van with a warranty, eliminating the unpredictable repair costs that were eating into margins.
Scenario 3: Scaling to a Multi-Stop Route. A bakery that started with a single cargo van for local cafe deliveries grows to serve twelve accounts across a metro area. The single van route now takes too long, so the owner finances a second, larger sprinter van to split the route and improve delivery windows.
Scenario 4: Adding Refrigerated Capacity. A bakery that specializes in custom cakes with perishable fillings needs to ensure product safety during transport in summer months. The owner finances a box truck with a built-in refrigerated cargo area instead of risking spoilage in an unrefrigerated van.
Scenario 5: Seasonal Volume Surge. A bakery experiences a major spike in orders during the holiday season and wedding cake season. Rather than renting vehicles short-term at a premium, the owner finances an additional van that will continue serving the business year-round.
Grow Your Bakery's Delivery Capacity Today
See how much you could qualify for on your next cargo van, sprinter van, or box truck. No obligation.
Apply Now →Frequently Asked Questions
How to Get Started
Complete our quick application at offers.crestmontcapital.com/apply-now, it takes just a few minutes.
A Crestmont Capital advisor will review your bakery's delivery needs and match you with the right vehicle financing option.
Once approved, your funds can go directly toward your cargo van, sprinter van, or box truck, often within days.
Conclusion
A reliable delivery vehicle is one of the most important operational investments a growing bakery can make, and commercial van financing gives bakery owners a way to fund cargo vans, sprinter vans, and box trucks without pulling cash out of the business at a critical growth moment. Whether the goal is replacing an aging van, adding refrigerated capacity, or scaling a wholesale route into a small delivery fleet, structured financing keeps working capital available for ingredients, staffing, and everything else that keeps a bakery running.
Bakery owners considering their next delivery vehicle should compare financing against leasing and other funding tools, factor in expected route mileage and cargo needs, and work with a lender that understands the seasonal and operational realities of a food business. With the right commercial van financing in place, a bakery can keep its delivery fleet dependable and focus on what matters most: getting fresh product to customers on time.
According to the U.S. Small Business Administration, access to reliable, affordable financing remains one of the most consistently cited growth barriers for small businesses, including food producers that depend on dependable transportation to reach customers. Data from the U.S. Census Bureau's County Business Patterns program also shows bakeries remain a significant and resilient category within the broader food manufacturing and retail sector, underscoring the ongoing need for practical financing tools like commercial van financing. For general guidance on comparing small business loan products, resources like Forbes Advisor's business loan guides can help bakery owners understand the broader financing landscape before choosing a lender.
Bakery owners can also read more about related equipment financing options in Crestmont Capital's guides to box truck financing and sprinter van financing, both of which go deeper into vehicle-specific financing considerations that apply directly to bakery delivery fleets.
Ultimately, the right financing decision comes down to matching the vehicle, the loan structure, and the repayment term to how the bakery actually operates day to day. A bakery running a tight, high-frequency local route has very different vehicle and cash flow needs than one shipping wholesale orders across a multi-county region once or twice a week. Taking the time to map out delivery volume, route distance, and seasonal peaks before applying for financing helps ensure the vehicle purchased today still fits the business a year or two down the road, rather than becoming a bottleneck the bakery has to finance its way out of again.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.








