
 (800) 949-0401
Commercial Ice Cream Batch Freezer Financing: The Complete Guide for Business Owners
Ice cream batch freezer financing is the fastest way for ice cream shops, gelaterias, and frozen dessert manufacturers to acquire the specialized production equipment that turns a simple recipe into a scalable, profitable business. A commercial batch freezer is one of the largest single equipment purchases most ice cream businesses ever make, and financing it correctly can mean the difference between opening on schedule and watching a launch date slip by months.
In This Article
What Is a Commercial Ice Cream Batch Freezer?
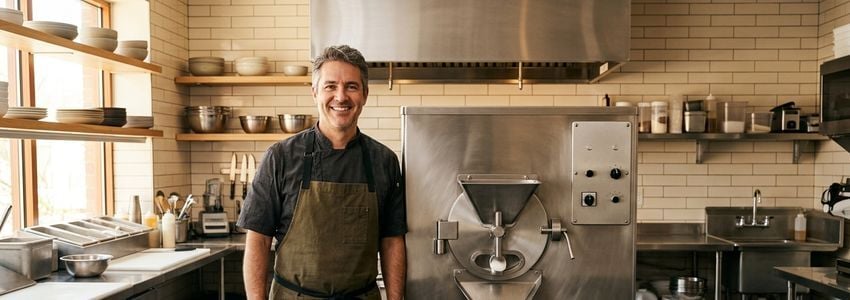
A commercial batch freezer is the workhorse machine that transforms a liquid ice cream, gelato, or sorbet base into a finished frozen product in a single production run, or "batch." Unlike a soft serve or continuous freezer, which churns product on demand for immediate service, a batch freezer produces a fixed quantity of finished product that is then hardened, stored, and scooped or packaged later. This makes batch freezers the standard choice for scoop shops, gelaterias, artisanal creameries, and small-batch wholesale producers who want tight control over texture, overrun, and flavor consistency.
Batch freezers range from small countertop units producing a few quarts per cycle, suitable for a single storefront location, to large floor-standing production models capable of turning out hundreds of gallons per shift for a growing wholesale or multi-location operation. Pricing reflects that range dramatically. A compact commercial batch freezer for a single-location scoop shop can run from roughly $8,000 to $20,000, while a production-scale unit designed for wholesale distribution, grocery accounts, or multi-unit franchise supply can easily exceed $60,000 to $150,000 once refrigeration, compressors, and ancillary equipment are included.
Because this piece of equipment sits at the center of the entire production workflow, most owners cannot simply wait and save up. Financing allows a business to install a properly sized batch freezer on day one, matched to current volume and built to handle growth, rather than settling for an undersized unit that gets outgrown within a year.
The batch freezing process itself matters as much as the machine's price tag. During each cycle, air is whipped into the base while it freezes, a process that determines "overrun," or how much the finished product expands in volume. Premium ice cream makers typically target lower overrun for a denser, richer product, while higher-volume operations may run higher overrun to control ingredient costs. The mixing paddles, refrigeration compressor, and freezing cylinder all need to be sized correctly for the viscosity and volume of product a business plans to run, which is why a generic entry-level machine often is not the right fit for a business with specific quality or throughput goals.
Most batch freezers on the market fall into a few broad categories: countertop or benchtop units for very small operations, mid-size floor models for a single busy retail location, and large-capacity production models built for wholesale, catering, or multi-location supply. Some manufacturers also offer combination units that pair a batch freezer with an integrated hardening cabinet, which can simplify both the buying decision and the financing application since it is often quoted and financed as a single package.
Beyond the freezer itself, most businesses also need to budget for supporting infrastructure: adequate electrical service, floor drains in some configurations, ventilation for the compressor, and enough refrigerated storage to hold finished product before it reaches the display case or delivery truck. A knowledgeable equipment vendor or contractor can help estimate these ancillary costs up front, and many lenders will finance them alongside the freezer itself if they are included on the same vendor invoice.
The batch freezing process itself matters as much as the machine's price tag. During each cycle, air is whipped into the base while it freezes, a process that determines "overrun," or how much the finished product expands in volume. Premium ice cream makers typically target lower overrun for a denser, richer product, while higher-volume operations may run higher overrun to control ingredient costs. The mixing paddles, refrigeration compressor, and freezing cylinder all need to be sized correctly for the viscosity and volume of product a business plans to run, which is why a generic entry-level machine often is not the right fit for a business with specific quality or throughput goals.
Most batch freezers on the market fall into a few broad categories: countertop or benchtop units for very small operations, mid-size floor models for a single busy retail location, and large-capacity production models built for wholesale, catering, or multi-location supply. Some manufacturers also offer combination units that pair a batch freezer with an integrated hardening cabinet, which can simplify both the buying decision and the financing application since it is often quoted and financed as a single package.
Key Benefits of Financing a Batch Freezer
Choosing to finance rather than pay cash for a commercial batch freezer offers several advantages that go beyond simply spreading out the cost.
- Preserve working capital. Cash stays available for ingredients, payroll, marketing, and the inevitable surprises that come with running a seasonal food business.
- Match payments to revenue. Monthly financing payments can be structured to align with cash flow, which matters enormously for a business with strong summer months and slower winter demand.
- Access newer, more efficient equipment. Financing makes it possible to buy the right-sized machine today instead of a smaller, cheaper unit that limits output.
- Faster time to revenue. Equipment financing can often be approved and funded in days rather than the weeks or months it can take to save enough cash.
- Potential tax advantages. Many financing structures allow a business to deduct equipment costs under standard business expense rules, though every business should confirm specifics with its own accountant.
- Build business credit. Making consistent, on-time payments on an equipment loan or lease helps establish a payment history that can make future financing easier to obtain.
- Bundle related equipment. Many lenders allow a batch freezer to be financed alongside a hardening cabinet, refrigeration upgrade, or display case in a single application, simplifying paperwork and often improving overall terms.
These advantages compound for food businesses in particular, where margins can be tight and seasonality creates real cash flow pressure. A shop that spends $60,000 in cash on a production-scale batch freezer right before its slow season may find itself short on funds for payroll or rent just a few months later. Structuring that same purchase as a financed monthly payment, sized to a percentage of typical monthly revenue, keeps the business in a far more resilient position.
Ready to Equip Your Ice Cream Business?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation, apply in minutes.
Apply Now →How Batch Freezer Financing Works
Ice cream batch freezer financing generally follows the same core mechanics as any other piece of commercial equipment financing, with a few industry-specific wrinkles worth understanding before you apply.
Unlike financing for general office equipment, lenders who work regularly with food and beverage businesses tend to understand seasonality, perishable inventory cycles, and the fact that a scoop shop's busiest quarter might generate far more revenue than its slowest one. That familiarity often translates into more realistic underwriting and, in some cases, payment structures built around a business's actual sales pattern rather than a flat payment every single month regardless of season.
- Get a quote from your equipment vendor. Most lenders finance a specific piece of equipment, so you will need a vendor invoice or quote showing the model, price, and any installation costs before applying.
- Submit a financing application. This typically requires basic business information, time in business, revenue figures, and recent bank statements. Established equipment lenders can often turn around a decision within 24 to 48 hours.
- Receive terms and select a structure. Depending on the lender, you may be offered a term loan, an equipment lease, or a lease-to-own structure, each with different down payment, term length, and end-of-term ownership implications.
- Sign and fund. Once terms are accepted, the lender typically pays the vendor directly (or reimburses you if equipment was already purchased), and the freezer ships or is installed.
- Begin repayment. Monthly payments start, usually on a fixed schedule, and the equipment itself typically serves as collateral, which is one reason equipment financing tends to have more flexible qualification standards than unsecured working capital loans.
Because the batch freezer itself secures the financing in most structures, approval decisions often lean more heavily on the value and useful life of the equipment than on a business owner's personal credit alone, which opens the door for newer ice cream businesses that might not qualify for a large unsecured loan.
Financing Options to Consider
There is no single "right" way to finance a batch freezer. The best structure depends on how long you plan to keep the equipment, how your cash flow moves throughout the year, and whether ownership at the end of the term matters to you.
- Equipment loans. You borrow a fixed amount, make fixed monthly payments over a set term (commonly 24 to 72 months), and own the batch freezer outright once the loan is repaid. This is the most straightforward option for owners who want to build equity in the equipment.
- Equipment leasing. Monthly payments are typically lower than a loan, and at the end of the lease you can often return the unit, renew, or purchase it for a predetermined buyout amount. Leasing can make sense for businesses anticipating rapid growth or technology upgrades.
- Lease-to-own agreements. A hybrid structure where regular payments build toward eventual ownership, often with a smaller final payment required, blending some benefits of both loans and leases.
- SBA-backed loans. SBA 7(a) loans can be used to finance equipment purchases with long repayment terms, sometimes stretching to the useful life of the equipment, and competitive rates for borrowers who qualify. The tradeoff is a longer application and underwriting timeline compared to direct equipment financing.
- Working capital loans. Some businesses prefer to pair a smaller equipment loan with a working capital facility to cover installation, electrical upgrades, staff training, or initial ingredient inventory that accompanies a new production line.
- Business lines of credit. A revolving line can supplement equipment financing by covering unexpected costs, such as a compressor upgrade or extra refrigeration capacity discovered during installation.
By the Numbers
Ice Cream Batch Freezer Financing - Key Statistics
$7.4B
Size of the U.S. ice cream shop industry
12,781
Ice cream shop businesses operating in the U.S.
78-84%
Approval rate for equipment financing at specialty lenders
24-72 Mo.
Typical batch freezer equipment loan term
Key Stat: According to the U.S. Census Bureau, food service and drinking establishments make up one of the largest segments of small business activity in the country, and equipment upgrades are consistently cited as a top driver of new financing applications in the sector.
Who This Financing Is Best For
Ice cream batch freezer financing tends to make the most sense for a specific set of business situations.
- New scoop shops and gelaterias opening their first location and needing to equip a full production kitchen without draining startup capital reserved for rent, buildout, and initial inventory.
- Existing shops upgrading capacity because their current freezer can no longer keep pace with demand, especially heading into peak spring and summer season.
- Multi-location operators standardizing equipment across stores or adding a central commissary kitchen to supply several retail locations.
- Wholesale and private-label producers scaling from a single-store operation into grocery, restaurant, or foodservice distribution, which typically requires higher-capacity production equipment.
- Seasonal businesses that want financing payments structured around cash flow, taking advantage of seasonal or step-up payment plans some lenders offer for businesses with predictable slow months.
Batch Freezer Financing vs. Other Funding Options
It helps to see how equipment-specific financing stacks up against the other funding paths a business owner might consider for a purchase like this.
| Funding Option | Typical Term | Speed to Fund | Best For |
|---|---|---|---|
| Equipment Loan | 24-72 months | 1-5 days | Owners who want to build equity and own the freezer outright |
| Equipment Lease | 12-60 months | 1-5 days | Businesses expecting to upgrade or scale equipment often |
| SBA 7(a) Loan | Up to 10 years | 2-8 weeks | Established businesses that can wait for lower long-term rates |
| Working Capital Loan | 3-24 months | 1-3 days | Covering installation, training, or ancillary startup costs |
| Business Line of Credit | Revolving | 1-3 days | Flexible, ongoing needs beyond the initial equipment purchase |
How Crestmont Capital Helps
Crestmont Capital works with ice cream shops, gelaterias, and frozen dessert manufacturers across the country to structure financing around the realities of a seasonal, equipment-intensive business. Rather than a one-size-fits-all loan, Crestmont starts with the equipment itself, the vendor quote, and the business's actual cash flow pattern to recommend a structure that fits.
For businesses that also need to cover other kitchen needs alongside a batch freezer, Crestmont's equipment financing programs can bundle multiple pieces of equipment into a single application, and its broader restaurant equipment financing options extend to walk-in freezers, refrigeration, and other kitchen infrastructure that often accompanies a new or expanded ice cream operation. Businesses that need working capital in addition to equipment can also explore SBA loan options through Crestmont for longer-term, lower-rate structures when timing allows.
Many ice cream business owners researching this topic also compare batch freezer financing to financing for the related equipment covered in Crestmont's guides on ice cream machine financing and soft serve machine financing, since many shops end up financing more than one type of production equipment as they grow. Gelato-focused operators may also find it useful to review Crestmont's guide on gelato shop business loans, which covers broader startup and expansion financing beyond equipment alone.
Scale Your Production Without Draining Cash Reserves
Crestmont Capital helps food and beverage businesses finance the equipment they need, fast. Apply in minutes, no obligation.
Apply Now →Real-World Scenarios
Scenario 1: The first-time shop owner. A first-time entrepreneur signs a lease for a small storefront and needs a full production kitchen, including a batch freezer, hardening cabinet, and display case. Rather than depleting the cash set aside for the first three months of rent and payroll, she finances the $18,000 batch freezer over 48 months, keeping her opening-day cash cushion intact.
Scenario 2: The seasonal upgrade. A ten-year-old ice cream shop is turning away wholesale orders because its aging batch freezer cannot keep pace with demand during peak summer months. The owner finances a larger production-capacity unit in early spring, timing the delivery so the new equipment is fully operational before the busy season begins, and structures payments to be lower in the winter off-season.
Scenario 3: The wholesale expansion. A gelato maker selling at farmers markets lands a deal to supply three local grocery stores. Meeting that volume requires a production-scale batch freezer costing $85,000. An equipment loan, secured primarily by the machine itself, allows the business to take on the contract without needing to bring in outside investors.
Scenario 4: The multi-location standardization. An operator with two existing locations wants a matching batch freezer at a third new location to standardize training and product consistency. Financing lets the business replicate its proven kitchen setup without waiting to save enough cash between openings.
Scenario 5: The equipment replacement emergency. A shop's batch freezer compressor fails during the busiest week of summer. Rather than losing weeks of peak-season revenue while saving for a replacement, the owner secures fast equipment financing and has a new unit installed within days.
Frequently Asked Questions
Don't Let Equipment Costs Slow You Down
Get the batch freezer your business needs today and pay over time. Apply now with no obligation.
Apply Now →Next Steps
Contact your equipment supplier for a written quote on the batch freezer model you need.
Pull together recent bank statements and time-in-business information.
Apply online with Crestmont Capital and receive a decision, often within 24 to 48 hours.
Once approved and funded, your equipment ships or is installed, and production can begin.
Conclusion
Ice cream batch freezer financing gives shop owners, gelato makers, and frozen dessert producers a practical path to acquiring essential production equipment without draining the cash reserves a growing food business needs to stay resilient. Whether you are opening your first storefront, upgrading aging equipment before peak season, or scaling into wholesale distribution, matching the right financing structure to your batch freezer purchase can help you move faster and grow with more confidence. According to industry data from the U.S. Census Bureau, food service businesses remain one of the most active segments applying for equipment financing each year, and Forbes reporting on 2026 commercial lending trends confirms that equipment financing approval rates and funding speed continue to improve for well-prepared applicants. Crestmont Capital works with ice cream and frozen dessert businesses nationwide to structure financing that fits real seasonal cash flow, not just a generic repayment schedule.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.








