
E-Commerce Business Financing: Loans for Online Stores & Digital Retailers
Running a successful e-commerce business means constantly juggling cash flow — purchasing inventory weeks before you see a sale, paying Amazon or Shopify fees before revenue hits your account, funding ad campaigns to drive traffic during peak seasons, and managing warehouse or 3PL costs that don't wait for your customers to click "Buy Now." The gap between spending and earning is where most online retailers struggle, and where the right financing partner makes all the difference.
At Crestmont Capital, we've been helping e-commerce businesses secure the working capital they need since 2015. Whether you're an Amazon FBA seller stocking up for Q4, a Shopify store owner bridging a cash flow gap, a DTC brand scaling ad spend, or a subscription box company preparing holiday inventory, we offer e-commerce business loans from $10,000 to $2,000,000 — with approvals in as little as 24 hours.
Unlike traditional banks that look skeptically at online-only revenue or require years of brick-and-mortar history, Crestmont Capital understands the unique financial rhythms of digital commerce. We evaluate your actual sales data, marketplace performance, and cash flow patterns — not just your credit score — to deliver financing solutions built for the way e-commerce actually works.
According to the U.S. Census Bureau, e-commerce now accounts for over 16% of all U.S. retail sales and continues growing at a double-digit annual pace. Yet many online sellers still lack access to the capital infrastructure that traditional retailers take for granted. That's the gap Crestmont Capital was built to fill.
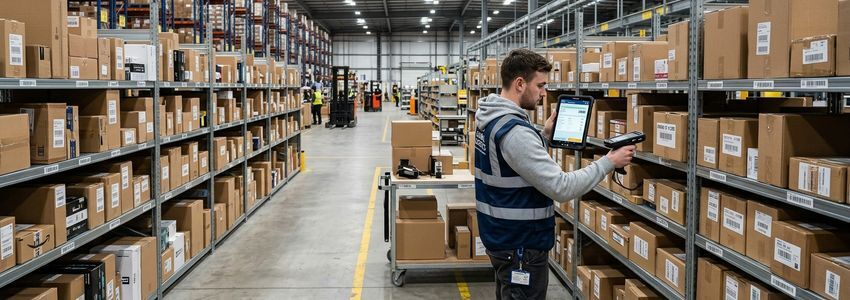
Why E-Commerce Businesses Need Specialized Financing
E-commerce operates on a fundamentally different financial timeline than traditional retail. When you sell through Amazon, Shopify, or your own DTC website, money doesn't flow in the same predictable patterns that banks expect. Here's why specialized financing is critical for online sellers:
The Inventory-to-Revenue Gap
You pay suppliers 30–90 days before products sell. For Amazon FBA sellers, that means purchasing inventory, shipping to fulfillment centers, waiting for products to be received, and then waiting for customer sales — all before you see a dollar. This gap can stretch to 120 days or more during peak season when Amazon's receiving queues back up. Inventory financing bridges this exact gap, letting you purchase product now and repay as sales come in.
Seasonal Revenue Spikes Demand Upfront Capital
Q4 — October through December — can represent 40–60% of annual revenue for many e-commerce sellers. But to capture that revenue, you need to purchase inventory in July, August, and September. Without capital, you either miss the season or drain your operating reserves. According to Forbes, online retailers who adequately capitalize for Q4 see revenue 3–5x higher than under-capitalized competitors who run out of stock during peak demand periods.
Ad Spend Requires Upfront Investment
Pay-per-click advertising on Google, Meta, and Amazon requires you to spend money before you earn it. A successful ad campaign might deliver a 3:1 or 5:1 ROAS (return on ad spend), but you still have to front the advertising budget — sometimes tens or hundreds of thousands of dollars — before you see results. Revenue-based financing and working capital loans allow DTC brands to scale proven ad campaigns without running out of cash.
Marketplace Fee Timing Creates Cash Flow Crunches
Amazon holds payouts for 14–21 days after delivery, Shopify processes payments within 2–5 business days, and many payment processors hold reserves for new merchants. Meanwhile, Amazon charges monthly storage fees, fulfillment fees per unit, and advertising costs that debit immediately. The mismatch between when you pay fees and when you receive revenue creates structural cash flow gaps that working capital loans are designed to address.
3PL and Fulfillment Costs Scale With Volume
Third-party logistics providers (3PLs) charge per-unit receiving, storage, pick-and-pack, and shipping fees. As your volume grows, so do these costs — and they're due before or concurrent with sales, not after. Managing 3PL relationships and scaling fulfillment operations requires reliable working capital.
Traditional Banks Don't Understand Online Revenue
Many banks still treat online sales skeptically, requiring multiple years of tax returns, brick-and-mortar collateral, and stellar personal credit scores. Crestmont Capital's approach is fundamentally different: we look at your actual business performance — sales volume, conversion rates, account health scores — to make lending decisions that reflect your real business, not an outdated template.
Types of E-Commerce Business Loans
Crestmont Capital offers multiple financing structures designed for different e-commerce scenarios. Understanding which type fits your situation helps you choose the fastest path to capital.
Working Capital Loans
The most flexible option for e-commerce businesses, working capital loans provide a lump sum that you repay over a fixed term through daily or weekly payments. Use working capital for any business purpose — inventory, advertising, staffing, software subscriptions, or general cash flow. Loan amounts from $10,000 to $500,000 with terms from 3 to 24 months. Ideal for sellers who need capital quickly without restrictions on how it's used.
Inventory Financing
Inventory financing is purpose-built for online retailers who need to purchase stock before it sells. The inventory itself serves as collateral, which can result in better terms than unsecured loans. This is particularly valuable for Amazon FBA sellers buying Q4 inventory, Shopify stores scaling for promotional events, and wholesale distributors managing large product volumes. Financing amounts from $25,000 to $2,000,000 based on inventory value and sales velocity.
Business Lines of Credit
A business line of credit gives you revolving access to capital up to your approved limit. Draw funds when you need them, repay, and draw again — without reapplying each time. This is ideal for e-commerce businesses with fluctuating capital needs, such as monthly inventory purchases, seasonal ad spend, or managing the timing gaps between marketplace payouts and supplier invoices. Lines from $10,000 to $250,000 with flexible draw and repayment terms.
Revenue-Based Financing
Revenue-based financing (RBF) aligns repayment with your actual sales performance. Instead of fixed monthly payments, you repay a percentage of daily or weekly revenue until the advance plus a flat fee is repaid. During slow periods, payments automatically decrease; during peak seasons, you pay more and clear the balance faster. RBF is particularly well-suited for DTC brands with strong but seasonally variable revenue. Advances from $25,000 to $1,000,000.
Short-Term Business Loans
Short-term business loans provide quick capital with terms from 3 to 18 months. They're ideal for bridging specific, time-sensitive opportunities — like a supplier offering a bulk discount, a flash sale opportunity requiring rapid inventory increase, or covering a cash flow gap caused by marketplace payment delays. Faster to obtain than traditional term loans, with streamlined underwriting based on recent business performance.
Fast Business Loans / Same-Day Funding
When opportunity knocks with a 24-hour window — a limited-time supplier deal, a viral product moment, or a sudden inventory shortage during peak season — fast business loans from Crestmont Capital deliver. With approval in as little as 4 hours and same-day or next-day funding available for qualified applicants, we help you move at the speed of e-commerce. Available from $10,000 to $500,000 for businesses with at least 6 months of operating history and consistent revenue.
Merchant Cash Advances
For e-commerce businesses processing significant credit card or marketplace sales volume, a merchant cash advance (MCA) provides capital based on future receivables. The advance is repaid as a small percentage of daily card transactions or marketplace deposits, making repayment seamless and automatic. MCAs are available even for businesses with less-than-perfect credit, with approvals based primarily on sales volume. Advances from $10,000 to $750,000.
Who Qualifies for E-Commerce Business Financing?
Crestmont Capital works with a wide range of online sellers. Here are the general qualification criteria for our most popular programs:
| Requirement | Minimum Threshold | Notes |
|---|---|---|
| Time in Business | 6+ months | Operating history and documented revenue are required. Product-specific eligibility requirements apply. |
| Monthly Revenue | $10,000+ | Higher revenue unlocks larger loan amounts and better rates |
| Credit Score | 500+ (owner) | We work with all credit profiles; score affects rate, not eligibility |
| Business Type | Any legal e-commerce entity | LLC, S-Corp, C-Corp, sole prop accepted |
| Marketplace Platform | Any (Amazon, Shopify, eBay, Etsy, WooCommerce, etc.) | API-connected data can accelerate underwriting |
| Bank Statements | 3 most recent months | Demonstrates cash flow patterns; marketplace dashboards also accepted |
| Collateral | Not always required | Inventory financing uses inventory as collateral; most working capital loans are unsecured |
Ready to Fund Your E-Commerce Growth?
Apply in minutes. Get approved in as little as 24 hours. Funding for Amazon, Shopify, DTC, and more.
Apply Now — It's FreeRates, Fees, and Terms
We believe in transparent pricing. Below are representative ranges for our most popular e-commerce financing products. Your specific offer will depend on your revenue, credit profile, time in business, and loan type.
| Product | Amount Range | Term | Factor Rate / APR Range | Funding Speed |
|---|---|---|---|---|
| Working Capital Loan | $10K–$500K | 3–24 months | 1.09–1.49 factor rate | 24–48 hours |
| Inventory Financing | $25K–$2M | 3–18 months | 8%–24% APR equivalent | 2–5 business days |
| Business Line of Credit | $10K–$250K | Revolving | 15%–40% APR (draw-based) | 24–72 hours |
| Revenue-Based Financing | $25K–$1M | Until repaid | 1.10–1.50 factor rate | 24–72 hours |
| Short-Term Business Loan | $10K–$350K | 3–18 months | 1.12–1.45 factor rate | 24–48 hours |
| Fast / Same-Day Loan | $10K–$500K | 3–12 months | 1.15–1.50 factor rate | Same day or next day |
| Merchant Cash Advance | $10K–$750K | Until repaid | 1.10–1.49 factor rate | 24–48 hours |
How It Works — Getting Your E-Commerce Loan in 5 Steps
Complete our secure online application at offers.crestmontcapital.com/apply-now. Provide basic business information, monthly revenue figures, and your desired loan amount. No lengthy paperwork, no in-person meetings required. The application takes approximately 10 minutes.
Upload your 3 most recent business bank statements and any relevant marketplace account data (Amazon Seller Central reports, Shopify dashboard exports, etc.). For inventory financing, a basic inventory valuation or purchase order may be requested. Our team will contact you promptly if additional documentation is needed.
Our underwriting team analyzes your cash flow, sales patterns, marketplace performance, and overall business health — typically within a few hours to one business day. You'll receive a personalized offer with clear terms: loan amount, factor rate or APR, repayment schedule, and funding timeline. No hidden surprises.
Review your offer carefully. If you have questions, our dedicated e-commerce financing specialists are available to walk through the terms. Once you're satisfied, sign electronically — no notary, no branch visit. Accept your offer and confirm your business bank account for deposit.
Funds are deposited directly to your business bank account, often within 24 hours of signing — sometimes the same business day for qualified applicants. Use your capital immediately for inventory purchases, ad campaigns, 3PL payments, or any business need. Repayment begins per your agreed schedule, with no prepayment penalties for early payoff.
E-Commerce Financing by Business Type
Different e-commerce business models have different capital needs. Here's how Crestmont Capital's financing solutions map to each model:
| Business Type | Common Capital Needs | Best Financing Products | Typical Loan Sizes |
|---|---|---|---|
| Amazon FBA Sellers | Q4 inventory purchases, IPI score improvements, new product launches, reorder cycle gaps, Amazon advertising (Sponsored Products/Brands) | Inventory Financing, Working Capital Loan, Revenue-Based Financing | $50K–$500K |
| Shopify Stores | Seasonal inventory, marketing campaigns, app/tech investments, fulfillment upgrades, flash sale preparation | Working Capital Loan, Line of Credit, Short-Term Loan | $25K–$250K |
| DTC Brands (Direct-to-Consumer) | Paid social ad spend (Meta, TikTok, Google), influencer partnerships, product development, packaging, PR campaigns | Revenue-Based Financing, Working Capital Loan, Line of Credit | $50K–$1M |
| Wholesale Distributors | Large bulk purchase orders, seasonal inventory builds, supplier payment terms, warehouse capacity expansion | Inventory Financing, Working Capital Loan | $100K–$2M |
| Dropshippers | Marketing budget scaling, platform fees, supplier relationship building, cash flow during payout delays | Working Capital Loan, Merchant Cash Advance, Line of Credit | $10K–$150K |
| Multi-Channel Retailers | Inventory allocation across channels (Amazon + Shopify + eBay + Walmart), cross-platform advertising, unified fulfillment | Working Capital Loan, Inventory Financing, Revenue-Based Financing | $75K–$750K |
| Subscription Box Businesses | Monthly box curation inventory, Q4 holiday edition builds, customer acquisition marketing, packaging and fulfillment costs | Working Capital Loan, Revenue-Based Financing, Short-Term Loan | $25K–$300K |
E-Commerce Industry: By the Numbers
U.S. E-Commerce at a Glance (2024–2025)
Sources: U.S. Census Bureau, Marketplace Pulse, Adobe Analytics, eMarketer
Don't Let Capital Hold Back Your E-Commerce Growth
From Amazon FBA inventory to DTC ad spend — we fund it all. Apply now and get your offer in 24 hours.
Get My E-Commerce LoanReal-World E-Commerce Financing Scenarios
Here's how online sellers across different business models have used Crestmont Capital financing to solve real problems and capture real opportunities.
Scenario 1: Amazon FBA Seller — $80,000 Q4 Inventory Purchase
A home goods Amazon FBA seller based in Texas had a breakout summer, generating $45,000/month in revenue. By August, he knew he needed to triple his inventory for the Q4 holiday rush, but his margins were tight and he'd already reinvested profits into new product development. His supplier required a $80,000 payment to secure priority production slots and guaranteed delivery before the October FBA cut-off date.
With a 90-day bank loan application timeline, traditional financing wasn't an option. He applied to Crestmont Capital, submitted 3 months of Seller Central reports alongside bank statements, and received a $80,000 working capital loan with a 12-month term within 48 hours. He secured his inventory, sold through 85% of stock during Q4, generated $175,000 in revenue that quarter, and repaid the loan in full ahead of schedule. Net result: his best quarter ever, funded by smart capital deployment.
Scenario 2: DTC Skincare Brand — $150,000 for Ad Spend + Inventory Scaling
A direct-to-consumer skincare brand based in Miami had cracked a winning Meta ad formula — a 4.2x ROAS on their hero product. The problem: their ad account spend cap was limited by available cash flow, and every dollar they could put into ads returned four dollars. They needed to scale ad spend from $25,000/month to $75,000/month while simultaneously building inventory to handle the increased order volume.
Crestmont Capital provided a $150,000 revenue-based financing facility, with repayment structured as a percentage of daily sales deposits. As sales scaled, repayment scaled proportionally. The brand deployed $90,000 into inventory and $60,000 into Meta advertising, grew monthly revenue from $120,000 to $310,000 within 90 days, and repaid the advance in full within 4 months — well ahead of the projected 8-month payback window.
Scenario 3: Shopify Store — $45,000 Working Capital Bridge
A specialty outdoor gear Shopify store in Colorado was in the middle of its busiest season when its primary payment processor placed a 21-day hold on $38,000 in accumulated sales — a common occurrence for newer merchants seeing unusual sales velocity spikes. With supplier invoices due and a restock needed immediately to keep pace with demand, the owner faced a frustrating but all-too-common e-commerce cash flow crunch.
A $45,000 short-term working capital loan from Crestmont Capital arrived within 24 hours of application. The owner restocked critical SKUs, fulfilled all pending orders on time, and avoided the negative reviews and lost sales that would have resulted from stockouts. When the processor released the held funds 21 days later, she used a portion to make an early loan payment, reducing her overall cost of capital.
Scenario 4: Subscription Box Company — $60,000 Holiday Inventory Build
A monthly subscription box company specializing in artisan food products had 3,800 active subscribers by October. The holiday season offered a massive opportunity: their subscriber count historically spiked 60–80% in November and December as gift subscriptions surged. But to fulfill holiday orders for both existing subscribers and projected new sign-ups, they needed to pre-purchase $60,000 in specialty food items — most from small-batch producers requiring advance payment and 4–6 week lead times.
Crestmont Capital approved a $60,000 inventory financing facility in 72 hours. The company placed orders immediately, received product in time for November fulfillment, successfully onboarded 1,400 new holiday subscribers, and generated their highest-revenue quarter to date. The loan was repaid using December subscription revenue, with interest costs representing a small fraction of the incremental revenue generated.
How E-Commerce Financing Compares: Crestmont Capital vs. Alternatives
| Financing Option | Approval Speed | E-Commerce Friendly? | Min. Requirements | Amounts | Best For |
|---|---|---|---|---|---|
| Crestmont Capital | 24–72 hours | ✓ Yes — built for it | 6 mo. in business, $10K/mo revenue | $10K–$2M | All e-commerce models |
| Traditional Bank Loan | 30–90 days | ✗ Often skeptical of online-only | 2+ years, 680+ credit, collateral | $50K–$5M | Established businesses with assets |
| Amazon Lending | 1–5 days (invite only) | ✓ Amazon-only | Invitation required; Amazon sellers only | $1K–$750K | Amazon-only sellers who receive offers |
| Shopify Capital | 2–5 days (invite only) | ✓ Shopify-only | Invitation required; Shopify merchants only | $200–$2M | Shopify-only merchants who receive offers |
| SBA Loan | 60–120 days | ~ Limited | Strong credit, collateral, extensive docs | Up to $5M | Long-term growth capital for established businesses |
| Personal Credit Cards | Instant (if pre-approved) | ~ Technically yes | Personal credit score | $5K–$50K | Small, short-term needs; high-cost option |
| Venture Capital / Angel | 3–18 months | ~ Selective | High-growth potential, equity stake required | $250K–$10M+ | Established businesses with documented revenue |
The key advantage of Crestmont Capital over marketplace-specific programs like Amazon Lending and Shopify Capital is that you don't need an invitation, you're not restricted to a single platform, and you can use funds across your entire business operation — including advertising, staffing, technology, and inventory for any channel.
Compare Your Options — Then Choose Crestmont
No invitation needed. No platform restrictions. E-commerce financing built for multi-channel sellers.
Apply in 10 MinutesTips for Getting Approved for E-Commerce Business Financing
Improve your chances of approval — and secure better rates — with these practical steps:
1. Keep Business and Personal Finances Separate
Lenders need to see your business cash flow clearly. If business income and expenses are mixed with personal accounts, underwriting becomes complicated and can result in lower offers or denials. Open a dedicated business checking account and run all business transactions through it — at minimum, for the 3 months before you apply.
2. Demonstrate Consistent Monthly Revenue
Lenders favor consistency over spikes. If your revenue is highly variable, be prepared to explain seasonal patterns and provide context. Average monthly revenue calculations weight recent months more heavily, so a strong recent 3-month performance can outweigh an older slow period. Document your seasonal patterns with year-over-year sales data if available.
3. Optimize Your Marketplace Account Health
For Amazon FBA sellers, your Inventory Performance Index (IPI) score, Order Defect Rate (ODR), and account standing directly impact how lenders view your business stability. A suspended or at-risk account will significantly complicate financing applications. Maintain excellent account health by monitoring these metrics proactively.
4. Prepare Documentation in Advance
Gather your 3 most recent months of business bank statements, recent marketplace payout reports, and a brief summary of how you plan to use the capital before applying. Organized applicants get faster decisions. For inventory financing, having supplier quotes or purchase orders ready can accelerate the process significantly.
5. Know Your Numbers
Be ready to explain your average order value, monthly units sold, inventory turnover rate, and gross margin. Lenders who specialize in e-commerce (like Crestmont Capital) understand these metrics and use them to assess your ability to repay. Knowing your numbers instills confidence and can lead to better loan terms.
6. Be Honest and Accurate on Your Application
Inconsistencies between your application and your bank statements or marketplace data are the fastest way to delay or kill a loan application. Provide accurate revenue figures, honest assessments of your business history, and realistic capital deployment plans. Our underwriting team reviews everything — and honesty builds the trust that leads to long-term lending relationships.
Why Choose Crestmont Capital for E-Commerce Financing?
Since 2015, Crestmont Capital has been one of the most trusted names in alternative business lending for U.S. small businesses — and we've built specific expertise in the e-commerce sector. Here's what sets us apart:
✓ Deep E-Commerce Expertise
We've financed hundreds of online sellers across Amazon, Shopify, eBay, Etsy, WooCommerce, and proprietary DTC websites. Our team understands the unique cash flow patterns of digital commerce — marketplace payout delays, seasonal inventory cycles, ad spend timing, and 3PL cost structures. We speak your language and structure financing around your actual business realities.
✓ Fast Approvals — Because E-Commerce Doesn't Wait
Supplier deals, viral product moments, and seasonal windows don't wait for 60-day bank approval processes. Crestmont Capital delivers preliminary decisions within hours and funding within 24–72 hours of approval. When speed matters, we deliver.
✓ Flexible Loan Structures for Every Model
Whether you need a one-time inventory purchase loan, a revolving line of credit for ongoing capital needs, or revenue-based financing that flexes with your sales volume, Crestmont Capital has a product designed for your situation. We don't force-fit every borrower into the same product.
✓ No Prepayment Penalties
We encourage responsible capital management. If your Q4 revenue comes in ahead of expectations and you want to pay off your loan early, there are no prepayment penalties. Pay it off early, save on costs, and come back when you need capital again.
✓ Transparent Terms — No Hidden Fees
Your offer letter spells out exactly what you'll repay, your payment frequency, and your total cost of capital. No origination fee surprises buried in page 14 of a contract. No floating rates that change after you sign. What you see is what you pay.
✓ Dedicated Account Support
From application through final repayment, you have access to a dedicated Crestmont Capital advisor who understands your business. Questions about your loan structure, early payoff options, or refinancing opportunities? Your advisor has answers — not an automated phone tree.
✓ Repeat Financing Programs
Many of our best client relationships start with a first loan and evolve into ongoing capital partnerships. As you repay and grow, your credit profile with Crestmont Capital improves, often unlocking larger amounts and better rates for future financing rounds. We're not just a transaction — we're a long-term capital partner built for your growth trajectory.
Frequently Asked Questions About E-Commerce Business Financing
How much can I borrow for my e-commerce business?
Do I need perfect credit to qualify?
How fast can I get funding for my e-commerce business?
Can I use the funds for Amazon advertising or paid social ads?
I'm an Amazon FBA seller. Can I use my Seller Central data to apply?
What's the difference between a working capital loan and inventory financing?
Are there any restrictions on which e-commerce platforms I can use?
How does repayment work?
Is there a prepayment penalty if I pay off early?
Can I get a second loan while still repaying my first?
What documentation do I need to apply?
What if my business is seasonal and revenue varies dramatically by month?
Does Crestmont Capital report to business credit bureaus?
E-Commerce Financing Is One Application Away
From $10,000 to $2,000,000 — working capital, inventory loans, lines of credit, and more. Built for Amazon sellers, Shopify stores, DTC brands, and every online retailer in between. Crestmont Capital has been funding e-commerce growth since 2015.