
 (800) 949-0401
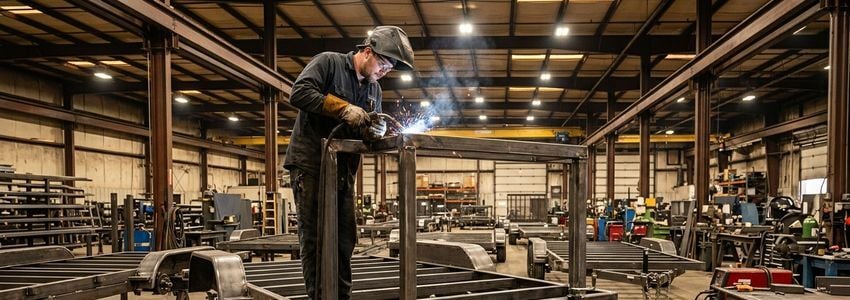
Trailer Manufacturing Equipment Financing: The Complete Guide for Business Owners
Trailer manufacturing equipment financing gives trailer builders a way to add welding stations, plasma cutters, press brakes, and paint lines without draining working capital. Whether you are replacing worn-out equipment or scaling up to handle a larger order book, the right financing structure can get new machinery on your shop floor in days rather than months.
In This Article
What Is Trailer Manufacturing Equipment Financing?
Trailer manufacturing equipment financing is a business loan or lease specifically structured to fund the purchase of machinery used to design, cut, weld, assemble, and finish trailers. This includes utility trailer, cargo trailer, horse trailer, equipment trailer, and semi-trailer manufacturers, as well as shops that build custom or specialty trailers for niche markets.
Unlike a general business loan, equipment financing is typically secured by the equipment itself. That collateral reduces risk for the lender, which often translates into faster approvals, more competitive rates, and less reliance on outside collateral like real estate. For a trailer manufacturer, this means a $150,000 robotic welding cell or a $40,000 CNC plasma table does not have to come entirely out of cash reserves.
Because trailer fabrication is capital equipment intensive from day one, most shops use some form of financing at multiple points in their growth, whether that is the first manual welding station, a mid-size press brake, or a full automated production line years later.
Key Benefits of Financing Your Equipment
- Preserve working capital. Keep cash available for materials, payroll, and day-to-day operations instead of tying it up in a single equipment purchase.
- Match payments to revenue. Monthly payments spread the cost of a machine over the years it will actually be in use, rather than requiring a lump sum upfront.
- Faster approval than traditional bank loans. Because the equipment secures the loan, underwriting can move quickly, often within a day or two for straightforward requests.
- Potential tax advantages. Many businesses structure equipment purchases to take advantage of applicable business expense deductions. Speak with your accountant about what applies to your specific situation.
- Stay competitive on bids. Modern cutting and welding equipment increases throughput, which can help you take on larger contracts or shorten lead times for customers.
- Flexible terms. Loan and lease terms can be matched to the expected useful life of the equipment, from a few years for smaller tools to a decade or more for major capital equipment.
Ready to Add Capacity to Your Fabrication Floor?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation, apply in minutes.
Apply Now →How It Works
The process for financing manufacturing equipment is more straightforward than many business owners expect. Lenders that specialize in equipment financing, including Crestmont Capital, have streamlined the application to reduce paperwork and turnaround time.
Once you identify the machine you want to purchase, whether it is a plasma cutting table, a hydraulic press brake, or a robotic welding cell, you get a formal quote from the vendor. That quote, combined with basic financial documentation from your business, is typically enough for a lender to begin underwriting.
Underwriters look primarily at time in business, monthly revenue, and cash flow trends rather than requiring years of audited financial statements. This is part of why equipment-secured financing tends to move faster than unsecured products or traditional term loans through a bank.
Quick Guide
How Trailer Manufacturing Equipment Financing Works — At a Glance
Choose the plasma cutter, press brake, welder, or paint line and get a vendor quote.
Submit basic business details and the equipment quote. Most applications take minutes.
Underwriting reviews cash flow and time in business. Many approvals happen within 24 to 48 hours.
Funds go to the vendor, equipment ships or installs, and you start building trailers on it.
Types of Equipment You Can Finance
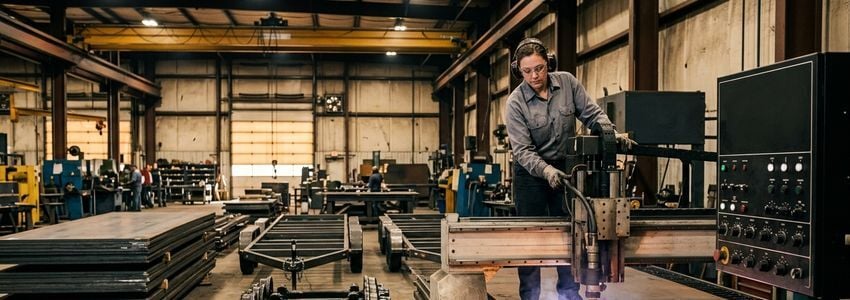
Trailer manufacturing covers a wide range of processes, and financing is available for nearly every stage of production. Common equipment categories include:
- Cutting equipment: CNC plasma tables, laser cutters, and band saws used to cut steel plate and tubing to spec.
- Forming equipment: Hydraulic press brakes, tube and pipe benders, and rollers used to shape frame rails, fenders, and structural components.
- Welding equipment: MIG and TIG welding stations, robotic welding cells, and automated seam welders for consistent, high-volume production.
- Axle and suspension tooling: Axle presses, torsion axle installation equipment, and suspension assembly jigs.
- Finishing equipment: Sandblasting cabinets, powder coating lines, and paint booths used for corrosion protection and finish quality.
- Material handling: Overhead cranes, forklifts, and jib cranes used to move steel stock and completed trailer frames around the shop.
- Assembly line equipment: Jigs, fixtures, and conveyor systems that support higher-volume, repeatable production runs.
Financing can cover new equipment from major manufacturers or used equipment purchased from a dealer or another shop, which is often a practical way to add capacity at a lower upfront cost.
Who This Financing Is Best For
Trailer manufacturing equipment financing tends to make the most sense for a few common situations. Established shops replacing aging or unreliable equipment often see an immediate return through reduced downtime and fewer scrapped parts. Growing manufacturers that have outgrown manual welding or cutting processes use financing to automate and take on larger contracts.
It is also a strong fit for shops adding a second production line or a new product category, such as moving from utility trailers into heavier equipment trailers, which typically requires larger presses, stronger welding equipment, and different tooling.
Key Stat: Small manufacturers make up 98% of all U.S. manufacturing firms and employ roughly 4.8 million workers, according to the SBA Office of Advocacy, yet many operate with equipment that is a decade or more old.
Financing Comparisons
Equipment financing is not the only path to acquiring new machinery. Understanding how it compares to other common options can help you choose the right fit for your shop's specific situation.
| Financing Option | Best For | Typical Term | Ownership |
|---|---|---|---|
| Equipment Loan | Buying a plasma cutter, press brake, or welder outright | 2 to 7 years | You own it once paid off |
| Equipment Lease | Preserving cash flow, easier future upgrades | 1 to 7 years | Lease, purchase, or return at end of term |
| SBA 7(a) Loan | Larger equipment purchases with longer runway | Up to 10 years for equipment | You own it once paid off |
| Business Line of Credit | Flexible needs beyond a single machine purchase | Revolving | N/A, not asset-specific |
For most single-machine purchases, an equipment loan or lease is the fastest and most straightforward option. SBA loans are worth exploring for larger, multi-machine expansions where the longer application timeline is worth the extended repayment term and potentially lower rate. A business line of credit is better reserved for working capital needs that go beyond a specific piece of equipment.
How Crestmont Capital Helps
Crestmont Capital works with trailer manufacturers across the country to structure financing for both individual machines and full production line upgrades. Our manufacturing equipment financing program is built around the realities of a fabrication shop, including seasonal order flow and the need to move quickly when a vendor has equipment ready to ship.
If your shop is adding cutting or forming capacity, our fabrication equipment financing options cover plasma tables, press brakes, and tube benders. For shops upgrading their welding department, whether that is a single new MIG station or a welding equipment financing package for a full robotic cell, we structure terms around the useful life of the machine.
We also offer general equipment financing for shops that need to bundle multiple types of machinery, such as a new paint booth alongside a material handling upgrade, into a single application and funding event. For larger, longer-term expansions, our team can also walk you through SBA loan options where they make sense.
Business owners researching this space may also find it useful to read our guide on financing welding equipment and industrial fabrication tools, or our overview of semi-trailer financing and leasing if your shop also operates its own delivery fleet.
Turn Down a Bigger Order With the Wrong Equipment?
Crestmont Capital helps trailer manufacturers finance the machines that win larger contracts. See your options today.
Apply Now →Real-World Scenarios
Scenario 1: Replacing a failing plasma cutter. A mid-size cargo trailer manufacturer was losing production days to breakdowns on an aging plasma table. Financing a new CNC plasma cutter allowed the shop to replace the machine without disrupting cash reserves needed for steel purchases, and the faster cut times reduced labor hours per unit almost immediately.
Scenario 2: Adding a robotic welding cell. A utility trailer builder fielding growing order volume could not keep up with manual welding alone. Financing a robotic welding cell let the shop increase output per shift without adding a second full welding crew, paying for the equipment through the additional units it enabled the shop to produce each month.
Scenario 3: Expanding into heavier equipment trailers. A shop that primarily built light utility trailers wanted to enter the equipment trailer market, which required a larger press brake and heavier-duty axle press. Equipment financing covered both machines in a single application, letting the shop start quoting larger jobs within weeks.
Scenario 4: Upgrading the finishing line. A horse trailer manufacturer financed a new powder coating line to replace outsourced finishing work. Bringing the process in-house shortened lead times for customers and gave the shop tighter quality control over the final product.
Scenario 5: Starting a second shift. A growing trailer manufacturer used equipment financing to duplicate a welding and cutting station setup, allowing the business to run a second production shift without waiting to save up capital for the new equipment first.
Pro Tip: Get a written quote from your equipment vendor before applying. Lenders move faster and can often issue a preliminary approval within a day when the make, model, and price are already documented.
Frequently Asked Questions
Get Pre-Qualified in Minutes
Talk to Crestmont Capital about financing for your next welder, press brake, or paint line. No obligation.
Apply Now →Next Steps
If your shop is ready to add capacity, replace aging equipment, or expand into new trailer categories, the next step is simple.
Conclusion
Trailer manufacturing equipment financing gives fabrication shops a practical way to acquire the welders, cutters, press brakes, and finishing equipment needed to grow without depleting working capital. Whether you are replacing a single aging machine or building out a full production line, matching the right financing structure to the equipment's useful life keeps payments manageable and your shop competitive. Crestmont Capital works with trailer manufacturers to structure financing that fits the pace of their business, from a single welding station to a complete facility upgrade.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.








