
 (800) 949-0401
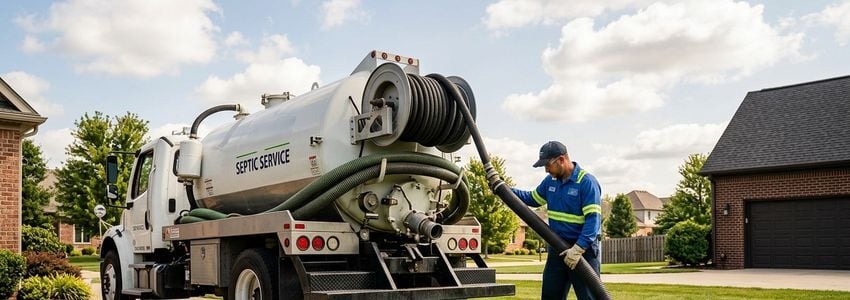
Septic Pumping Truck Financing: The Complete Guide for Business Owners
Septic truck financing is the fastest way for septic service companies, portable sanitation operators, and wastewater haulers to acquire a new or used pumping truck without draining cash reserves. Whether you are replacing an aging vacuum truck, expanding your fleet to take on more residential and commercial routes, or launching a new septic service division, the right financing structure can put a fully equipped truck to work within days rather than months.
This guide walks through exactly how septic pumping truck financing works, what it costs, which structures make the most sense for different business situations, and how to qualify even if your credit profile is less than perfect. By the end, you will understand how to evaluate lenders, compare financing versus leasing, and move forward with confidence.
In This Article
- What Is Septic Pumping Truck Financing?
- Key Benefits of Financing a Septic Pumping Truck
- How Septic Truck Financing Works
- Types of Septic Pumping Trucks You Can Finance
- Who Septic Truck Financing Is Best For
- Financing vs. Leasing vs. Paying Cash
- How Crestmont Capital Helps Septic Businesses
- Real-World Scenarios
- FAQ
- Next Steps
What Is Septic Pumping Truck Financing?
Septic pumping truck financing is a business loan or equipment lease structured specifically to help septic service, portable sanitation, and liquid waste hauling companies purchase vacuum trucks, honey wagons, and combination jetter-vac units. Instead of paying the full purchase price of a truck up front, which can range from $60,000 for a used unit to well over $250,000 for a new heavy-duty combination truck, a business spreads the cost across fixed monthly payments over two to seven years.
The truck itself typically serves as collateral, which is why lenders can offer competitive rates even to businesses without years of financial history. Because the equipment holds real resale value, financing companies view septic trucks as bankable assets, similar to how they treat dump trucks, box trucks, or other specialty commercial vehicles.
This distinction matters more than most first-time borrowers realize. Unsecured business loans rely almost entirely on the borrower's credit history and cash flow to determine approval odds and pricing. Equipment financing shifts a large portion of that risk calculation onto the asset itself. A vacuum truck with a well-maintained tank, functioning pump system, and documented service history holds resale value in a fairly liquid secondary market, which gives lenders confidence even when a business is young or has had a rough financial stretch. That is precisely why septic and vacuum truck financing tends to be more accessible than general working capital financing for many operators.
It also means the financing conversation is different from a typical bank loan application. Instead of an extended review of years of tax returns and a lengthy business plan, most septic truck financing applications focus on three things: the truck being purchased, recent business bank activity, and how long the company has been operating. This streamlined approach is one of the main reasons septic operators turn to equipment-specific financing instead of a traditional term loan when a truck purchase is on the table.
Key Stat: According to the U.S. Census Bureau, more than 20 percent of American households rely on a septic system rather than a municipal sewer connection, creating steady, recurring demand for pumping and maintenance services nationwide.
Key Benefits of Financing a Septic Pumping Truck
Financing a septic pumping truck instead of paying cash preserves working capital for payroll, fuel, insurance, and unexpected repairs. Most septic service owners find that keeping cash on hand is more valuable than owning a truck outright, especially during the early growth years of the business.
Septic and liquid waste hauling is a capital-intensive business. Between fuel costs, disposal facility fees, insurance premiums for commercial vehicles, and routine equipment maintenance, operators already carry significant fixed and variable overhead before a single truck payment is added. Committing $80,000 to $150,000 or more in cash to a single truck purchase can leave a business without the cushion it needs to handle a slow month, a compliance fee increase at the disposal facility, or an unexpected repair on a different piece of equipment. Financing spreads that cost over time so a single purchase decision does not put the rest of the operation at risk.
There is also a strategic growth argument for financing even when a business technically has the cash available. Every dollar spent on a truck in cash is a dollar that cannot be redeployed toward hiring a technician, marketing to new commercial accounts, or bidding on a larger municipal contract that requires upfront mobilization costs. Businesses that finance equipment while directing available cash toward growth initiatives tend to scale faster than those that pay cash for every asset, simply because they are not constantly waiting to rebuild reserves after each purchase.
- Preserve working capital: Keep cash available for fuel, payroll, disposal fees, and emergency repairs instead of tying it up in one large purchase.
- Predictable monthly payments: Fixed-rate structures make budgeting simple and protect against interest rate volatility.
- Faster fleet expansion: Add a second or third truck to cover more routes and take on larger commercial or municipal contracts sooner.
- Tax-friendly structures: Many equipment financing agreements qualify for accelerated depreciation treatment, which your accountant can factor into year-end planning.
- Access to newer, more reliable equipment: A newer vacuum truck means fewer breakdowns, less downtime, and a more professional appearance for customer-facing routes.
- Approval speed: Equipment-secured financing often closes in a matter of days, not weeks, letting you seize seasonal demand spikes.
Ready to Add a Truck to Your Fleet?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation, apply in minutes.
Apply Now →How Septic Truck Financing Works
The financing process for a septic pumping truck follows a straightforward path from application to delivery. Understanding each step helps you prepare the right documentation and avoid delays.
1. Application. You submit basic business information, the truck you intend to purchase (or the dealer quote), and financial details such as time in business and estimated annual revenue.
2. Documentation review. Lenders typically request a recent equipment quote or invoice, a few months of bank statements, and in some cases a personal guarantee from the business owner. Established businesses may qualify for streamlined "app-only" approval on smaller transactions.
3. Underwriting and approval. The lender evaluates the truck's collateral value, the business's cash flow, and credit history. Because the truck secures the loan, approval decisions often come back within 24 to 48 hours.
4. Rate and term selection. Once approved, you choose your term length (commonly 36 to 72 months), down payment amount, and whether you prefer a loan (you own the truck immediately) or a lease (lower payments, option to buy at the end).
5. Funding and delivery. The lender pays the dealer or seller directly, and the truck is released to your business. Many septic operators go from signed application to a truck on the lot within a week.
It is worth understanding what happens behind the scenes during underwriting, because it explains why some applications move faster than others. Lenders typically pull a business credit report and, in many cases, a personal credit report for the primary owner, since most equipment financing agreements include a personal guarantee for businesses under a certain revenue threshold. They will also look at time in business, average bank balance, and whether there have been any recent overdrafts or non-sufficient funds incidents. None of these factors need to be perfect, but wild swings in bank balances or a very short operating history can shift a deal from an automatic approval to one that requires additional documentation, such as a signed contract with a commercial customer or a letter explaining a temporary cash flow dip.
Sellers and dealers who regularly work with financed buyers can also speed up the process considerably. An equipment dealer that is used to providing a clean, itemized invoice with the truck's VIN, tank capacity, pump specifications, and any recent refurbishment work will get funding released faster than a private-party seller who cannot produce documentation. If you are buying from a private seller, ask them to provide maintenance records and recent photos of the tank interior and pump assembly. Lenders may request these directly, and having them ready in advance avoids a delay at the final step.
Types of Septic Pumping Trucks You Can Finance
Financing is available for the full range of equipment septic and liquid waste businesses rely on, whether new, used, or custom-built on a chassis you already own.
- Vacuum trucks (honey wagons): The core workhorse for residential septic tank pumping, ranging from 1,000 to 4,000-gallon capacities.
- Combination jetter-vac trucks: Units that combine high-pressure water jetting with vacuum extraction, popular for municipal and commercial line cleaning contracts.
- Portable restroom service trucks: Smaller vacuum trucks fitted with freshwater tanks for servicing portable toilets at construction sites and events.
- Grease trap pumping trucks: Specialized vacuum equipment for restaurant and commercial kitchen grease trap service routes.
- Slide-in vacuum tank units: Tank-and-pump systems mounted onto a chassis cab you already own, a lower-cost path to adding vacuum capacity.
- Used and refurbished trucks: Pre-owned vacuum trucks are financeable in most cases as long as the tank and pump system pass inspection, making them a lower entry-cost option for new operators.
By the Numbers
Septic Pumping Truck Financing — Key Statistics
20%+
Of U.S. households rely on a septic system (Census Bureau)
$60K-$250K+
Typical price range for used vs. new vacuum trucks
24-48 Hrs
Typical time to financing approval decision
36-72 Mo
Common repayment terms for equipment financing
What Drives the Cost of Financing a Septic Truck
Several factors influence the interest rate and terms a septic operator will be offered, and understanding them helps you negotiate a better deal or plan around a weaker credit profile.
- Age and condition of the truck: New trucks and late-model used trucks with low hours typically qualify for the best rates because they carry stronger resale value as collateral.
- Tank and pump inspection results: A truck with a documented recent pump rebuild or tank recoat will often qualify for better terms than one with an unknown maintenance history.
- Business time in operation: Businesses operating for two or more years generally receive more competitive rates than brand-new startups, though startups are still commonly approved with a larger down payment or shorter term.
- Personal and business credit history: Stronger credit profiles unlock lower rates and higher approval amounts, but equipment-secured financing remains accessible across a wide credit spectrum because the truck itself backs the loan.
- Down payment size: A larger down payment reduces the lender's risk exposure and can meaningfully lower the interest rate offered.
- Term length: Shorter terms typically carry lower rates but higher monthly payments; longer terms lower the monthly payment but increase total interest paid over the life of the loan.
Who Septic Truck Financing Is Best For
Septic truck financing works well across a wide range of business situations, not just one type of operator.
- Established septic companies replacing aging equipment: When a truck's pump system or tank starts requiring frequent repairs, financing a replacement avoids costly downtime.
- Growing operators adding a second or third route: Businesses that are turning away calls due to truck capacity limits can finance additional units to capture more revenue.
- New septic service entrepreneurs: Operators launching a new business can finance a used truck to control startup costs while still delivering professional service.
- Portable sanitation companies: Event and construction site service providers who need dedicated vacuum trucks separate from their residential septic fleet.
- Municipal and commercial contractors: Businesses bidding on grease trap, lift station, or municipal line cleaning contracts that require jetter-vac combination units.
Pro Tip: If your current truck is down for repairs more than once a quarter, run the numbers on financing a replacement. The cost of a missed service call or an unhappy commercial customer often exceeds a monthly truck payment.
Financing vs. Leasing vs. Paying Cash
Choosing the right acquisition structure depends on your cash position, growth plans, and how long you intend to keep the truck.
| Option | Best For | Ownership | Cash Impact |
|---|---|---|---|
| Equipment Loan | Long-term ownership, building equity | Immediate | Down payment + fixed monthly payment |
| Equipment Lease | Lower payments, flexibility to upgrade | Optional buyout at term end | Little to no down payment |
| Cash Purchase | Businesses with strong reserves and no growth urgency | Immediate, no debt | Full purchase price up front |
Most growth-focused septic businesses choose financing or leasing to keep cash available for operations while still getting a reliable truck on the road immediately.
The decision between a loan and a lease often comes down to how long you expect to run the same truck. Vacuum trucks and combination jetter-vac units are durable pieces of equipment that can remain in active service for a decade or longer with proper maintenance, which is why many established operators prefer a loan structure that builds toward full ownership. A lease can make more sense for a business that anticipates upgrading equipment every few years to stay current with newer tank technology, emissions requirements, or a growing service territory that calls for larger tank capacity down the road.
Another consideration is how the truck will be used. A truck purchased for a long-term residential route business, where the same territory and customer base will be served for years, is typically a strong candidate for a loan. A truck acquired to fulfill a defined-length municipal or commercial contract might be better suited to a lease with an end-of-term option, giving the business flexibility to either buy out the truck if the contract renews or return it if the work does not continue.
How Crestmont Capital Helps Septic Businesses
Crestmont Capital works with septic service companies, portable sanitation operators, and liquid waste haulers across the country to structure financing that matches their cash flow and growth plans. Our commercial truck financing programs cover new and used vacuum trucks, combination jetter-vac units, and slide-in tank systems, with approval decisions that move fast enough to keep a growing operation on schedule.
For businesses that need a broader vehicle solution, our business vehicle financing and heavy truck financing options extend beyond a single unit to help build out an entire route fleet. If you are buying a pre-owned vacuum truck to control costs, our used truck financing program is built specifically for that scenario.
Beyond the truck itself, many septic operators also lean on a working capital loan or a business line of credit to cover fuel, disposal fees, and payroll during seasonal demand swings. Businesses that are further along in growth sometimes explore SBA loan options for larger, longer-term capital needs. If you are still weighing your options, our team can walk through the numbers with no obligation.
Septic operators looking to compare their broader financing landscape may also find it useful to read our guide on septic service business loans, or our post on emergency septic and wastewater system repair financing for unplanned equipment failures.
Keep Your Routes Running
Fast approval decisions on truck financing so a breakdown never turns into lost customers.
Apply Now →Real-World Scenarios
Scenario 1: The aging fleet replacement. A septic company running two 15-year-old vacuum trucks was losing service days each month to pump repairs. Financing a new combination unit let the owner retire the least reliable truck immediately, cutting missed appointments and improving customer reviews within the first quarter.
Scenario 2: The new route expansion. A single-truck operator was consistently booked two weeks out and turning away same-day emergency calls. Financing a second used vacuum truck allowed the business to hire a second technician and immediately capture the overflow demand it had been losing to competitors.
Scenario 3: The commercial contract win. A portable sanitation company won a bid for a large construction site contract that required a dedicated jetter-vac unit. Equipment financing let the business acquire the specialized truck without disrupting cash flow needed to staff the new contract.
Scenario 4: The startup entrepreneur. A former septic technician decided to start an independent business after years working for someone else. With limited startup capital, financing a well-maintained used vacuum truck let him launch with professional equipment while preserving cash for insurance, licensing, and marketing.
Scenario 5: The seasonal surge. A grease trap pumping business saw demand spike heading into a busy restaurant season. Rather than turning down new commercial accounts, the owner financed an additional grease trap truck with a 48-month term, matching payments to the steady monthly revenue those new contracts generated.
Scenario 6: The multi-generational family business transition. A septic company that had operated for over 30 years under one owner was preparing to transition management to the next generation. Part of that transition plan included modernizing the aging fleet. Rather than draining the business's cash reserves right before a leadership change, the family financed two replacement trucks over a 60-month term, allowing the new leadership to inherit a modern, reliable fleet without inheriting a depleted bank account.
Scenario 7: The disposal facility relocation. When a regional disposal facility a septic company relied on closed, the business had to expand its service radius to reach the next-closest facility, adding significant drive time and fuel costs per load. The owner used equipment financing to acquire a larger-capacity vacuum truck, reducing the number of trips required per day and offsetting the added drive time with fewer, larger loads per route.
Frequently Asked Questions
Don't Let Truck Capacity Cap Your Growth
Get a fast financing decision and put a new or used vacuum truck to work this month.
Apply Now →Next Steps
Identify the new or used vacuum truck, jetter-vac unit, or slide-in system you want to purchase and get pricing from the dealer or seller.
Share basic business details along with the equipment quote to start the underwriting process.
Compare loan versus lease terms and choose the structure that fits your cash flow and growth plans.
Once approved, funding goes directly to the seller and your new truck is ready to start generating revenue.
Conclusion
Septic pumping truck financing gives septic service, portable sanitation, and liquid waste hauling businesses a practical way to acquire the equipment they need without a large upfront cash outlay. Whether you are replacing an aging vacuum truck, adding a second route, or launching a new business, structured financing keeps cash available for the day-to-day costs of running a service fleet while getting reliable equipment on the road fast.
The septic and liquid waste industry is not going away. As long as homes and businesses rely on septic systems, grease traps, and portable sanitation, there will be steady, recurring demand for pumping and maintenance services. The businesses positioned to capture that demand are the ones with reliable equipment, enough truck capacity to say yes to new customers, and the financial flexibility to keep growing rather than getting stuck maintaining an aging fleet. Structured financing is how most successful septic operators build that capacity without putting the rest of their business at risk.
With approval decisions often available within 24 to 48 hours, septic truck financing remains one of the quickest paths to growing capacity and taking on more business. Whether your next step is replacing a single aging truck or building out a multi-truck fleet to cover a larger territory, the right financing structure lets you make that move on your timeline rather than waiting until you have saved enough cash to pay outright.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.








