
 (800) 949-0401
Commercial Kayak Manufacturing Equipment Financing: The Complete Guide for Business Owners
Kayak manufacturing equipment financing gives boat builders and paddlesports manufacturers a way to acquire rotational molding machines, layup tooling, trimming stations, and finishing equipment without draining working capital. With U.S. paddlesports participation now topping 34 million people annually and the outdoor recreation economy reaching a record $1.3 trillion in 2024, demand for kayaks has never been stronger. For small and mid-size manufacturers trying to keep pace with orders from dealers, rental fleets, and direct-to-consumer buyers, the right financing structure can be the difference between turning down business and scaling to meet it.
In This Article
What Is Kayak Manufacturing Equipment Financing?
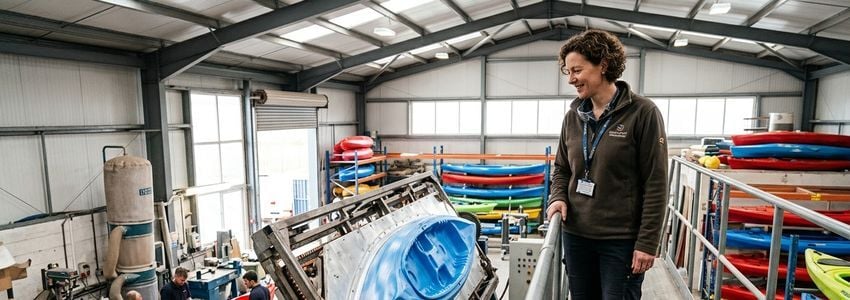
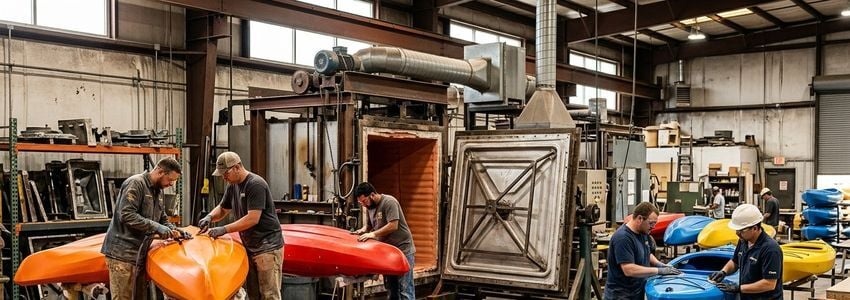
Kayak manufacturing equipment financing is a category of commercial equipment lending built for businesses that design, mold, assemble, and finish kayaks, canoes, and related paddlecraft. It covers the full range of capital equipment a manufacturer needs to run production: rotational molding ovens and arm machines, blow molding systems, thermoforming presses, mold tooling, trimming and deflashing stations, hardware installation jigs, paint and graphics booths, and material handling equipment used to move finished hulls through the plant.
Unlike a general business loan, equipment financing is typically structured around the asset being purchased. The machine itself often serves as collateral, which allows lenders to offer longer terms and more competitive rates than an unsecured product. This structure matters in kayak manufacturing because the core production equipment, particularly rotational molding systems, can represent a six-figure investment that would otherwise take years to save for out of cash flow alone.
Industry Insight: More than 34 million Americans participated in paddlesports in 2025, and recreational kayaking alone accounted for over 15 million participants. Manufacturers who can scale production to meet dealer and rental-fleet demand are positioned to capture a growing share of a market that keeps setting new participation records.
Most kayak hulls sold in the U.S. market are produced using rotational molding (rotomolding), a process where powdered polyethylene is heated and rotated inside a mold to form a seamless hull. Higher-end and performance kayaks may use thermoformed ABS sheet or composite layup construction instead. Each production method requires a distinct equipment set, and financing programs are typically flexible enough to cover new equipment, used equipment purchased from a closing or downsizing manufacturer, or a combination of both as a shop scales up.
Key Benefits of Equipment Financing for Kayak Manufacturers
Manufacturers who finance their production equipment rather than paying cash upfront gain several strategic advantages that directly affect their ability to grow and compete.
- Preserve working capital: Keep cash available for raw polyethylene resin, hardware components, packaging, freight, and payroll instead of tying it up in a single equipment purchase.
- Match payments to revenue: Structure loan or lease terms around your seasonal production cycle, since most kayak sales are concentrated in the spring and summer months.
- Scale production capacity quickly: Add a second rotomolding arm machine or a larger oven to fulfill a new dealer contract without waiting years to accumulate cash reserves.
- Access newer, more efficient equipment: Modern rotomolding systems and multi-arm carousels reduce cycle time and energy costs compared to older equipment, improving unit economics on every hull produced.
- Potential tax advantages: Equipment purchases financed through a loan may qualify for accelerated depreciation treatment; consult your CPA for guidance specific to your business.
- Build owned assets: Financing (as opposed to leasing) allows you to build equity in equipment that has resale value if you later upgrade or close a production line.
Ready to Expand Your Production Line?
Get fast, flexible financing from the #1 business lender in the U.S. Equipment loans, working capital, and leasing options available for manufacturers. No obligation to apply.
Apply Now →Types of Financing Available for Kayak Manufacturing Equipment
Kayak manufacturers have access to several financing products depending on the equipment involved, the size of the purchase, and their credit and revenue profile.
Equipment Financing (Term Loans)
This is the most common option for purchasing rotomolding machines, molds, and finishing equipment. The equipment serves as collateral, and terms typically run from 24 to 84 months depending on the useful life of the asset. Crestmont Capital's equipment financing program covers new and used manufacturing equipment from $10,000 into the millions of dollars for larger production line buildouts.
Equipment Leasing
Rather than owning the machine outright, equipment leasing lets manufacturers use production equipment for a fixed monthly payment. This is useful when a shop wants to preserve capital, test a new production method before committing to ownership, or plans to upgrade equipment again within a few years as demand or technology changes.
Working Capital Loans
Unsecured working capital loans provide cash for resin purchases, hardware components, seasonal payroll, and other operating costs that surge before the spring selling season. These loans do not require collateral and can fund within 24 to 48 hours of approval.
Business Line of Credit
A business line of credit gives manufacturers a revolving pool of capital to draw from as raw material orders and production schedules fluctuate. You only pay interest on what you use, making it a strong fit for the peaks and valleys of a seasonal manufacturing calendar.
Small Business Administration (SBA) Loans
SBA loans offer the lowest available interest rates for qualifying small manufacturers, with terms up to 10 years for equipment and 25 years for real estate. The SBA 7(a) program is commonly used to fund larger production equipment purchases and facility buildouts. The application process is more document-intensive than alternative lending, but the cost savings can be significant over the life of the loan.
Commercial Equipment Lines of Credit
For manufacturers who regularly purchase molds, tooling upgrades, and smaller finishing equipment throughout the year, a revolving equipment line of credit provides pre-approved access to capital that can be drawn on repeatedly without reapplying for each purchase.
By the Numbers
Kayak Manufacturing and Paddlesports - Key Statistics
$1.3T
U.S. outdoor recreation economy contribution, 2024
34M+
Americans who participated in paddlesports in 2025
603K+
Small business manufacturers in the U.S.
98%
Share of U.S. manufacturing firms that are small businesses
How the Financing Process Works
Financing production equipment for a kayak manufacturing business follows a straightforward path when you work with an experienced lender like Crestmont Capital. Here is what the process typically looks like from application to funded equipment on your shop floor.
Provide basic business information, the equipment vendor quote or invoice, and 3-6 months of business bank statements.
A lending specialist reviews your revenue history, time in business, and the equipment's value and useful life to determine terms.
You get a clear offer detailing loan amount, rate, term, and monthly payment, often within 24 hours for most equipment financing requests.
Once you accept the offer, funds are released directly to the equipment vendor or into your account, and installation can begin.
Pro Tip: Get a written quote from your equipment vendor before you apply. Lenders can move faster when the exact make, model, and price of the rotomolding machine, oven, or tooling is already documented, and it often improves your approval odds.
Comparing Financing Options Side by Side
Each financing product serves a different purpose. Use this comparison to identify which structure fits your next equipment purchase.
| Financing Type | Best For | Typical Terms | Collateral Required | Speed to Fund |
|---|---|---|---|---|
| Equipment Financing | Rotomolding machines, ovens, tooling | 24-84 months | Equipment itself | 2-5 days |
| Equipment Leasing | Preserving capital, upgrading later | 12-60 months | Equipment itself | 3-7 days |
| Working Capital Loan | Resin, hardware, seasonal payroll | 3-36 months | None (unsecured) | 24-48 hours |
| Business Line of Credit | Fluctuating material and production costs | Revolving / 12-24 months | Sometimes required | 1-3 days |
| SBA Loan | Large production line buildouts | Up to 10-25 years | Usually required | 30-90 days |
How Crestmont Capital Helps Kayak Manufacturers
Crestmont Capital is a nationally recognized alternative lender rated #1 in the U.S. for small business financing. We specialize in fast, flexible funding designed for manufacturers who cannot afford to wait weeks or months for a bank decision while a production window closes.
For kayak and paddlecraft manufacturers, we offer equipment financing for rotational molding systems, ovens, molds, trimming and finishing stations, and material handling equipment. We also provide working capital loans for resin and hardware purchases ahead of the busy spring season, plus lines of credit for ongoing operational flexibility. Our underwriting team evaluates your actual business performance and order pipeline, not just your credit score, which matters for seasonal manufacturers whose revenue is naturally uneven throughout the year.
Manufacturers who have been in business for at least 6 months and generate consistent monthly revenue are often strong candidates for our programs. Many clients receive approval decisions within 24 hours and have equipment funded within days, not months.
Our financing programs for kayak and paddlesports manufacturers include:
- Equipment financing for new and used rotomolding systems, ovens, and tooling
- Equipment leasing for manufacturers who want to preserve capital
- Unsecured working capital loans for resin, hardware, and seasonal payroll
- Business lines of credit for flexible, reusable capital
- SBA loan programs for long-term, low-rate financing on larger buildouts
If your shop is also exploring general manufacturing equipment financing beyond kayak-specific tooling, or fabrication equipment for custom mold work, our fabrication equipment financing programs can be structured alongside your production equipment loan.
Scale Your Kayak Production This Season
Crestmont Capital has funded thousands of small manufacturers across the U.S. Apply in minutes and get a decision fast, with no obligation required.
Get Funded Now →How to Qualify for Kayak Manufacturing Equipment Financing
Qualification requirements vary by lender and financing type. Here is a general overview of what most lenders, including Crestmont Capital, consider when evaluating an equipment financing application for a kayak or paddlecraft manufacturer.
Time in Business: Most lenders prefer at least 6-12 months of business history. SBA loans typically require 2 or more years. Alternative lenders like Crestmont Capital often work with younger manufacturing businesses, particularly when the equipment being financed has strong resale value.
Monthly or Seasonal Revenue: Lenders review revenue trends rather than expecting flat monthly numbers, since kayak manufacturing is naturally seasonal. Demonstrating consistent year-over-year order volume during peak months strengthens an application even if winter months are slower.
Credit Score: Credit score matters but is not the only factor. Many alternative lenders approve manufacturing equipment financing for borrowers with scores as low as 600, especially when the equipment itself provides strong collateral value. SBA loans typically require a 650+ personal credit score.
Equipment Vendor Quote: Having a formal quote or invoice from your rotomolding equipment manufacturer or dealer speeds up underwriting significantly, since it confirms exactly what is being financed and its fair market value.
Business Financial Documentation: For larger purchases, such as a full rotomolding line or facility buildout, lenders may request profit and loss statements, tax returns, and a brief description of your production plan and expected order volume.
Key Takeaway: Even if you have been turned down by a bank, you may still qualify for alternative equipment financing through Crestmont Capital. We evaluate the full picture of your manufacturing business, including seasonal revenue patterns and the value of the equipment itself, not just a credit score.
Real-World Financing Scenarios for Kayak Manufacturers
To illustrate how equipment financing works in practice, here are six realistic scenarios kayak and paddlecraft manufacturers face regularly.
Scenario 1 - Adding a Second Rotomolding Arm Machine: A small manufacturer running a single-arm rotomolding machine lands a new regional dealer contract that would double order volume. To meet the production schedule, they need a second arm machine costing $180,000. They secure equipment financing through Crestmont Capital, approved within 48 hours, with a 60-month term that keeps monthly payments manageable during the ramp-up period.
Scenario 2 - Replacing an Aging Oven: An outdated rotomolding oven is causing inconsistent wall thickness and increasing scrap rates. The manufacturer finances a new, more energy-efficient oven for $95,000 over 72 months, and the reduction in scrap and energy costs offsets a meaningful portion of the monthly payment within the first year.
Scenario 3 - Seasonal Resin Purchasing: Ahead of the spring selling season, a manufacturer needs to place a large bulk order for polyethylene resin to lock in favorable pricing and guarantee supply. A $60,000 working capital loan covers the purchase, repaid over 9 months as summer sales revenue comes in.
Scenario 4 - New Mold Tooling for a Product Line Expansion: A manufacturer wants to launch a new fishing kayak model to capture growth in that fast-growing category. New mold tooling costs $140,000. Equipment financing spreads the cost over 48 months, allowing the new SKU to generate revenue well before the tooling is paid off.
Scenario 5 - Facility Expansion for Increased Capacity: A growing manufacturer outgrows its current shop floor and needs to lease a larger facility with room for a second production line. An SBA loan funds leasehold improvements and additional equipment, with a 10-year term that matches the long-term nature of the investment.
Scenario 6 - Material Handling and Finishing Upgrade: To speed up trimming, deflashing, and hardware installation, a manufacturer invests $45,000 in updated finishing stations and an overhead hoist system for moving hulls through the shop. A business line of credit funds the purchase, drawn down as each piece of equipment arrives.
How to Get Started
Complete our quick application at offers.crestmontcapital.com/apply-now. It takes just a few minutes and requires no commitment.
A Crestmont Capital advisor reviews your application, discusses your equipment needs, and matches you with the right financing product for your production plan.
Receive your funds and put them to work, whether that means a new rotomolding machine, mold tooling, or resin inventory. Most equipment financing decisions arrive within 24-48 hours.
Start Your Application Today
No obligation and no hard credit pull to check your options. Get matched with the right financing product for your manufacturing business in minutes.
Apply Now →Conclusion
Kayak manufacturing equipment financing gives boat builders the capital they need to compete in one of the fastest-growing segments of the outdoor recreation economy. Whether you need to add a rotomolding arm machine to meet new dealer demand, replace an aging oven, invest in new mold tooling for a product launch, or manage seasonal resin purchasing, the right financing structure can transform your production capacity without draining your cash reserves.
Crestmont Capital specializes in fast, flexible equipment financing designed for manufacturers who cannot afford to wait on a bank decision while orders pile up. With a streamlined application process, same-day decisions on most products, and equipment funded within days, we make it simple to secure the capital your production line needs.
Apply today at offers.crestmontcapital.com/apply-now and discover what kayak manufacturing equipment financing can do for your business.
Frequently Asked Questions
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.








