
 (800) 949-0401
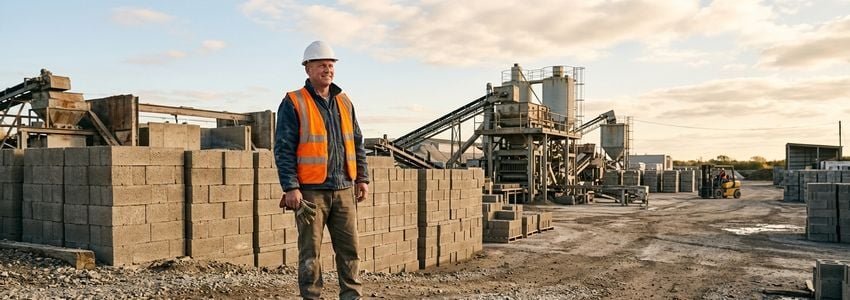
Concrete Block Manufacturing Equipment Financing: The Complete Guide for Business Owners
Running a concrete block plant means constant pressure to keep up with local construction demand while your machinery ages, breaks down, or simply cannot keep pace with larger orders. Concrete block manufacturing equipment financing gives block producers, masonry supply yards, and precast operators a way to acquire block making machines, batching systems, and curing equipment without tying up the cash reserves needed to run daily operations.
Whether you are replacing an aging static block machine, adding an automated egg-layer system, or building out a new production line to serve a growing regional builder base, financing turns a six-figure capital expense into a predictable monthly payment. This guide walks through exactly how it works, what it costs, who qualifies, and how to get funded.
In This Article
- What Is Concrete Block Manufacturing Equipment?
- Key Benefits of Financing
- Types of Equipment You Can Finance
- How Financing Works
- How Much Does This Equipment Cost?
- Loan vs Lease Compared
- Who Qualifies?
- How Crestmont Capital Helps
- Real-World Scenarios
- Financing vs Other Options
- Frequently Asked Questions
- Next Steps
- Conclusion
What Is Concrete Block Manufacturing Equipment?
Concrete block manufacturing equipment covers the full range of machinery used to produce concrete masonry units (CMUs), pavers, retaining wall blocks, and related precast products. This is not one machine, but an entire production system that moves raw material from a batching plant through molding, curing, and finished-goods handling.
Core categories of equipment used in block manufacturing include:
- Block Making Machines: Static, semi-automatic, or fully automatic "egg-layer" machines that vibrate and compress concrete into molds to form finished blocks.
- Batching and Mixing Systems: Aggregate bins, conveyors, and mixers that measure and combine sand, cement, aggregate, and water to a precise mix design.
- Curing Systems: Curing racks, kilns, or autoclaves that harden freshly molded blocks to the strength required by ASTM standards before they can be shipped or stacked.
- Material Handling Equipment: Forklifts, pallet handlers, cubing and de-cubing equipment, and conveyor systems that move blocks through the plant and onto delivery trucks.
- Mold Sets and Tooling: Interchangeable molds for standard 8x8x16 CMU, split-face block, retaining wall units, pavers, and specialty shapes.
A plant's production capacity, block quality consistency, and labor costs are all directly tied to the equipment on the floor. Outdated or undersized machinery is one of the most common reasons small and mid-size block manufacturers lose bids to larger regional producers.
Key Benefits of Financing Block Manufacturing Equipment
Most block plant owners do not have hundreds of thousands of dollars sitting idle to pay cash for a new production line. Financing lets you get the equipment you need now while spreading the cost over the useful life of the machine.
Preserve Working Capital
Cement, aggregate, fuel, and payroll all require consistent cash flow. Financing your block machine or curing system means you are not draining the reserve you need to cover raw materials and keep crews on the payroll during slower months.
Upgrade to Higher Output Immediately
Financing makes it possible to install an automated egg-layer system or a larger batching plant right away instead of limping along with a manual machine that caps your daily block count. Higher output lets you bid on larger commercial and municipal contracts you would otherwise have to turn down.
Match Payments to Revenue
Construction demand is seasonal in many regions. Lenders that understand the building materials industry, including Crestmont Capital, can structure payment schedules around your busy and slow seasons so payments do not strain cash flow during winter shutdowns.
Build Business Credit
An on-time equipment financing history strengthens your business credit profile, making it easier to secure financing for the next expansion, whether that is a second plant location or a fleet of delivery trucks.
Keep Pace With Competitors
Regional block producers with newer, faster, more automated equipment can produce more units per labor hour and win price-sensitive bids. Financing closes that competitive gap without requiring a cash reserve most independent plants simply do not have.
Key Stat: The U.S. concrete block market was valued at approximately $9.8 billion in 2024, and the vast majority of manufacturers producing that supply are small, family-owned operations rather than national conglomerates.
Ready to Expand Your Block Production Line?
Get the machinery you need without draining your working capital. Apply in minutes with no obligation.
Apply Now →Types of Equipment You Can Finance
Financing is available for both new and used equipment across every stage of block production. Understanding your options helps you plan the right financing amount and structure.
Static and Stationary Block Machines
Entry-level static machines are the most affordable starting point for a small plant or a producer expanding into block for the first time. These machines produce one pallet of blocks at a time and are well suited to lower-volume regional demand.
Egg-Layer and Mobile Block Machines
Egg-layer machines move across a paved yard, laying freshly molded blocks directly onto the ground to cure, eliminating the need for pallets and racking. This equipment increases throughput significantly and is a common upgrade path for growing producers.
Fully Automated Production Lines
High-volume plants run fully automated lines that integrate batching, molding, cubing, and curing into a continuous process with minimal manual labor. These systems represent a major capital investment but dramatically reduce per-unit labor cost.
Curing and Kiln Systems
Steam curing chambers, autoclaves, and covered curing racks speed up strength development and allow plants to turn inventory faster, which is critical during peak building season.
Material Handling and Yard Equipment
Forklifts, cubers, de-cubers, and yard trucks that move finished block from the curing area to inventory and onto customer trucks are frequently bundled into the same financing package as the primary block machine.
Mold Sets and Attachments
Specialty mold sets for retaining wall block, pavers, or architectural split-face units can also be financed, either as part of a new machine purchase or as a standalone add-on to expand your product line.
How Concrete Block Manufacturing Equipment Financing Works
Financing production equipment follows a straightforward process designed to get machinery on your plant floor quickly.
- Application: Complete a one-page application with basic business details (time in business, annual revenue, entity type) and information about the equipment you want to purchase, including the vendor and price.
- Documentation Review: For financing requests under roughly $250,000, the application alone is often sufficient. Larger equipment purchases, such as a full automated line, may require recent bank statements or financial statements.
- Credit Decision: The lender reviews your business and personal credit profile, time in business, and cash flow. Because the equipment itself serves as collateral, approval decisions often come back within hours.
- Funding and Delivery: Once you accept the offer and sign, the lender pays your equipment vendor directly. Your new block machine, batching system, or curing equipment is delivered and installed, and monthly payments begin.
From application to funded equipment, the process typically takes just a few business days, which matters when you need to fulfill a contract deadline or replace a failed machine before your plant sits idle.
How Much Does Concrete Block Manufacturing Equipment Cost?
Pricing varies widely based on automation level, output capacity, and whether you buy new or used equipment.
- Used or Refurbished Static Machines: Entry-level static block machines can range from $15,000 to $60,000 depending on condition, capacity, and included molds.
- New Semi-Automatic Machines: Mid-range semi-automatic block machines with hydraulic vibration and multiple mold configurations typically run $75,000 to $250,000.
- Egg-Layer and Mobile Machines: Mobile egg-layer systems generally fall between $150,000 and $400,000 depending on output rate and mold flexibility.
- Fully Automated Production Lines: A complete automated line, including batching plant, block machine, cubing system, and conveyors, commonly runs $500,000 to over $2 million for high-volume operations.
- Curing Systems: Steam curing chambers and covered curing racks range from $20,000 to $150,000 depending on chamber size and automation.
Remember to factor in freight, site preparation, electrical work, and installation labor when requesting your financing amount. Many lenders, including Crestmont Capital, allow these soft costs to be rolled into the total financed amount so you have one payment covering the entire project.
Loan vs Lease: Which Fits Your Block Plant?
The two most common ways to finance block manufacturing equipment are equipment loans and equipment leases. The right choice depends on how long you plan to run the machine and how you want to manage cash flow.
| Feature | Equipment Loan | Equipment Lease |
|---|---|---|
| Ownership | You own the block machine from day one; lender holds a lien until paid off. | The leasing company owns the equipment; you pay to use it for a set term. |
| End of Term | You own the equipment outright once the final payment posts. | Buy it out, renew, or upgrade to newer production technology. |
| Monthly Payment | Generally higher since you are financing the full equipment value. | Often lower because you are only paying for depreciation during the term. |
| Best For | Plants planning to run the same machine for 10+ years and build equity. | Producers who want to upgrade to faster, more automated systems every few years. |
| Upfront Cost | May require a 10-20% down payment on larger equipment. | Often just first and last payment, preserving more cash upfront. |
For plants planning to run the same static or semi-automatic machine for a decade or more, an equipment loan that builds ownership equity is often the better long-term value. Producers who expect automation technology to keep improving may prefer equipment leasing to stay current without being locked into aging machinery.
Who Qualifies for Concrete Block Manufacturing Equipment Financing?
Because the equipment itself acts as collateral, qualification requirements for block manufacturing financing tend to be more accessible than a traditional bank loan.
Key Qualification Factors
- Credit Score: A personal or business credit score of 620 or above is a strong starting point, though programs exist for lower scores.
- Time in Business: Most lenders prefer at least one to two years of operating history, though startup plants backed by an experienced operator may still qualify.
- Annual Revenue: Lenders want to see revenue sufficient to comfortably support the new monthly payment on top of existing obligations.
- Industry Experience: Experience running or managing a concrete, masonry, or precast operation strengthens an application significantly.
- Down Payment: Many programs require little to no money down, though offering 10-20% can improve approval odds and rate for larger equipment purchases.
Even producers with less-than-perfect credit or a shorter operating history should still apply. Lenders who specialize in equipment financing for building materials manufacturers understand seasonal cash flow patterns common in the construction supply chain. The U.S. Small Business Administration also offers general guidance on preparing a strong loan application for capital-intensive manufacturing businesses.
How Crestmont Capital Helps Concrete Block Manufacturers
As a top-rated U.S. business lender, Crestmont Capital specializes in fast, flexible financing built around the real capital needs of manufacturing and building materials businesses. We understand that a down block machine means lost production days and missed delivery windows, which is why we prioritize speed without sacrificing flexibility.
Our Core Financing Products
- Equipment Financing: Our equipment financing program covers new and used block machines, batching systems, and curing equipment with terms up to 72 months and financing up to 100% of equipment cost.
- Equipment Leasing: Our equipment leasing options provide lower monthly payments and end-of-term flexibility to upgrade to newer, more automated machinery.
- Working Capital Loans: Beyond machinery, our working capital loans can cover raw material purchases, payroll, or facility improvements alongside your equipment purchase.
- Business Line of Credit: A business line of credit gives seasonal producers flexible access to cash for material costs during your busiest production months.
The Crestmont Capital Advantage
- Speed: Apply online in minutes with decisions often returned same day.
- Flexibility: Programs designed around varying credit profiles and seasonal manufacturing cash flow.
- Bundled Financing: Combine your block machine, forklift, curing system, and mold sets into a single application and payment.
- Industry Understanding: Our team works with construction materials manufacturers regularly and structures financing around how your plant actually generates revenue.
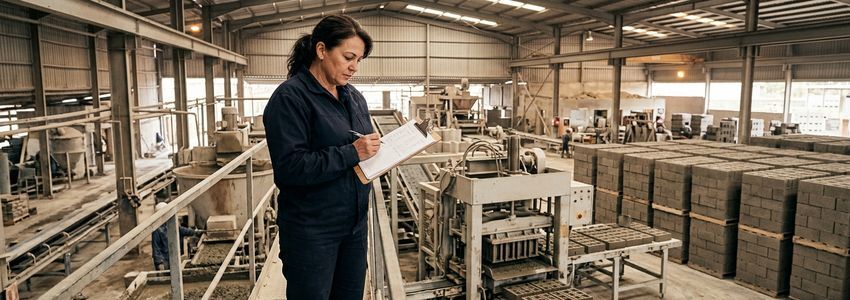
See What You Qualify For
Our financing specialists understand concrete manufacturing equipment. Get a free, no-obligation quote today.
Get Your Quote →Real-World Scenarios
The following scenarios illustrate how block manufacturing equipment financing supports plants at different stages of growth.
1. The Family-Owned Block Plant Replacing Aging Machinery
Scenario: A second-generation block plant is running a 30-year-old static machine that breaks down monthly, causing missed delivery windows.
Challenge: A replacement semi-automatic machine costs $120,000, more than the plant wants to pull from cash reserves during a slow season.
Solution: The owner finances the machine with a 60-month equipment loan. Reduced downtime alone recovers the monthly payment within the first two months, and reliability improves customer retention.
2. The Growing Producer Adding an Egg-Layer Line
Scenario: A regional producer is turning away large commercial bids because their static machine cannot hit volume deadlines.
Challenge: A mobile egg-layer system costs $220,000, a major jump from their current equipment.
Solution: Financing spreads the cost over 60 months. The higher output lets the plant win two new commercial contracts in the first year, more than covering the new payment.
3. The Startup Block Manufacturer Entering the Market
Scenario: An experienced plant manager leaves a large producer to start an independent block operation serving a underserved rural market.
Challenge: Limited startup capital makes a $90,000 used semi-automatic machine feel out of reach.
Solution: Leveraging strong personal credit and 15 years of industry experience, the owner secures financing with a modest down payment, launching operations within six weeks of incorporation.
4. The Precast Producer Adding a Curing Chamber
Scenario: A precast retaining wall manufacturer needs faster strength development to keep pace with landscaping contractor demand during peak season.
Challenge: A $65,000 steam curing chamber would strain cash flow if paid upfront during the busiest production months.
Solution: Equipment leasing keeps monthly payments low, and faster curing turnaround lets the plant ship inventory two days sooner, increasing monthly output capacity by 20%.
5. The Multi-Location Operator Standardizing Equipment
Scenario: An operator running two block plants wants to standardize on the same automated machine at both locations for parts and training consistency.
Challenge: Buying two new automated lines for $850,000 combined would require significant outside investment.
Solution: The operator finances both machines under a single master financing agreement, simplifying administration and locking in consistent terms across both facilities.
6. The Municipal Supplier Upgrading for Compliance
Scenario: A block producer supplying municipal infrastructure projects needs to upgrade batching accuracy to meet updated ASTM specification requirements.
Challenge: The required computerized batching system costs $95,000, an unplanned but necessary expense to retain municipal contract eligibility.
Solution: Fast-tracked equipment financing gets the new batching system installed within three weeks, preserving the company's status as an approved municipal supplier.
Pro Tip: Many block plant owners bundle a new block machine with a forklift, curing rack system, or delivery truck into a single financing package. This means one application, one approval, and one predictable monthly payment instead of juggling multiple loans.
Concrete Block Manufacturing Financing vs Other Options
Financing vs. Paying Cash
Paying cash for a $150,000 block machine avoids interest but ties up capital that could otherwise cover raw material purchases, payroll during a slow month, or an unexpected repair on other plant equipment. Financing lets the new equipment's increased output help pay for itself over time.
Financing vs. a Business Line of Credit
A business line of credit is useful for revolving material and payroll costs but is not ideal for a single large equipment purchase. A structured equipment loan typically carries a lower fixed rate and a clear payoff schedule matched to the equipment's useful life.
Financing vs. Buying Used With a Personal Loan
Some owners consider a personal loan to buy used equipment. This mixes personal and business liability and often carries a higher rate than a dedicated commercial equipment loan, which is secured by the machinery itself rather than personal assets.
Did You Know? According to the SBA, small businesses make up roughly 98% of all U.S. manufacturers, meaning nearly every concrete block plant in the country is competing for the same regional contracts as a small business, not a mega-corporation.
By the Numbers
The U.S. Concrete Block Industry
$9.8B
Estimated U.S. concrete block market value in 2024
98%
Share of U.S. manufacturers that are small businesses (SBA)
1.36M
U.S. housing starts in 2025, a core demand driver for block (Census)
24-72
Typical financing term length in months for block plant machinery
Don't Wait to Grow Your Plant
The right block making equipment pays for itself in new contracts. Apply today and get funded fast.
Apply for Financing →Frequently Asked Questions
Next Steps: How to Apply for Financing
Ready to put new production equipment on your plant floor? Getting started with Crestmont Capital takes just a few minutes.
Submit Your Application
Complete a simple one-page online application. You will need basic business details and information about the block making equipment you want to purchase.
Review Your Financing Offer
A financing specialist contacts you, often within hours, to walk through approved amount, rate, term, and monthly payment options.
Get Your Equipment Installed
Once you sign, we pay your equipment vendor directly. Your new block machine or plant equipment ships and gets installed so you can start production.
Conclusion
A concrete block plant is only as productive as the equipment running on its floor. Aging static machines, undersized batching systems, and slow curing capacity all cap the volume you can produce and the contracts you can bid on. Strategic concrete block manufacturing equipment financing removes that ceiling without forcing you to drain the working capital your operation needs day to day.
Whether you are replacing a failing machine, adding an automated egg-layer line, or building out an entirely new plant, the right financing partner can get equipment installed and producing revenue in days, not months. Contact Crestmont Capital today to see how fast, flexible funding can help your block manufacturing business grow.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.








