
 (800) 949-0401
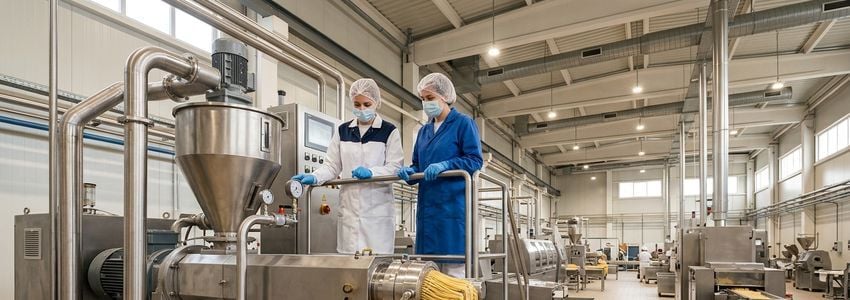
Commercial Pasta Making Equipment Financing: The Complete Guide for Pasta Producers
Commercial pasta making equipment financing gives pasta producers, artisan pasta shops, and wholesale manufacturers a practical way to acquire extruders, sheeters, dryers, and packaging lines without draining working capital. Whether you are scaling a small-batch fresh pasta operation into a regional wholesale supplier or replacing an aging dryer that is slowing your production line, the right financing structure can mean the difference between a stalled expansion and a fully operational plant. This guide breaks down how commercial pasta making equipment financing works, what equipment qualifies, who it is best suited for, and how to choose the right funding path for your pasta business.
In This Article
What Is Commercial Pasta Making Equipment Financing?
Commercial pasta making equipment financing is a funding structure that lets a pasta business acquire production machinery, such as extruders, mixers, sheeters, dryers, and packaging systems, by spreading the cost over fixed monthly payments instead of paying the full purchase price upfront. Lenders typically use the equipment itself as collateral, which often makes approval faster and terms more accessible than an unsecured business loan.
This type of financing exists because commercial pasta equipment is expensive and highly specialized. A single industrial extruder can cost anywhere from $30,000 to well over $250,000 depending on output capacity, and a full production line with mixing, extrusion, cutting, and drying components can easily run into six or seven figures. Very few pasta producers, especially independent and family-owned operations, can pay that cost in cash without disrupting day-to-day operations.
Instead of tying up cash reserves, pasta producers use financing to preserve liquidity for payroll, ingredients, packaging supplies, and marketing while still gaining immediate access to the equipment they need to grow production volume. The equipment starts generating revenue the same month it is installed, which is the core logic behind financing production machinery rather than saving up to buy it outright.
Key Stat: Investment in equipment and software across U.S. industries was projected to rise by more than 6 percent in 2025, with manufacturing businesses driving a significant share of that growth as they modernize production lines and expand domestic output.
Key Benefits of Financing Pasta Production Equipment
Pasta producers choose financing over cash purchases for several reasons that go beyond simply not having enough capital on hand. The benefits compound as a business scales, particularly for operations moving from small-batch retail sales into wholesale, grocery, or foodservice distribution.
- Preserves working capital. Cash stays available for flour, semolina, eggs, packaging, and payroll instead of being locked into a single capital purchase.
- Predictable monthly payments. Fixed payment schedules make it easier to forecast cash flow and plan production growth around a known expense.
- Faster equipment access. Financing approval is often faster than saving up cash reserves, letting a producer capture new wholesale contracts or seasonal demand sooner.
- Potential tax advantages. Many financing structures allow businesses to deduct equipment costs or lease payments as ordinary business expenses, though every business should confirm specifics with a qualified accountant.
- Upgrade flexibility. Leasing structures in particular make it easier to upgrade to newer, higher-capacity equipment as your pasta business grows without being stuck with outdated machinery.
- Builds business credit. Consistent, on-time payments on equipment financing help establish and strengthen a business credit profile for future funding needs.
Ready to Scale Your Pasta Production?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation, apply in minutes.
Apply Now →How Pasta Equipment Financing Works
The process of financing commercial pasta making equipment follows a fairly standard sequence, though the exact requirements vary by lender and the size of the equipment purchase. Understanding each step helps producers move through the process with fewer surprises.
First, a producer identifies the specific equipment needed, whether that is a single-screw extruder, a new sheeter for fresh pasta sheets, a continuous dryer, or a full packaging and portioning line. Having a vendor quote in hand at the time of application speeds up underwriting significantly, since the lender can evaluate the exact asset being financed rather than an estimated range.
Next, the producer submits a financing application along with basic business documentation. This typically includes time in business, recent bank statements, and in some cases a simple equipment list or vendor invoice. Because the equipment itself secures the financing, approval decisions can often be made within one to two business days for standard equipment amounts.
Once approved, the lender funds the vendor directly or reimburses the business for a recent purchase, depending on the structure. The pasta producer then begins making fixed monthly payments over the agreed term, commonly ranging from 24 to 72 months depending on the equipment type and useful life.
Quick Guide
How Commercial Pasta Equipment Financing Works, At a Glance
Get a vendor quote for the extruder, sheeter, dryer, or packaging line you need.
Provide basic business details and recent bank statements alongside the equipment quote.
Because the equipment secures the financing, decisions often come back within one to two business days.
The vendor is paid, equipment is installed, and you begin producing pasta while making fixed monthly payments.
Types of Pasta Equipment You Can Finance
Commercial pasta making equipment financing covers the full range of machinery used across dry, fresh, and stuffed pasta production. Lenders generally finance any equipment with a clear resale value and defined useful life, which includes most standard pasta production assets.
- Extruders. Single-screw and twin-screw extruders that shape dry pasta such as penne, rigatoni, fusilli, and spaghetti through metal or bronze dies.
- Sheeters and roll formers. Equipment used for fresh pasta sheets, lasagna, fettuccine, and other flat-cut pasta shapes.
- Ravioli and stuffed pasta formers. Machines that portion, fill, seal, and cut stuffed pasta shapes like ravioli, tortellini, and agnolotti.
- Mixers and dough kneaders. Industrial mixers that combine flour, semolina, water, and eggs into consistent dough for downstream shaping.
- Dryers. Continuous or batch dryers that reduce moisture content in dry pasta products to extend shelf life and meet food safety standards.
- Pasteurizers and cooking lines. Equipment used for par-cooked or fully cooked pasta products sold refrigerated or frozen.
- Packaging and portioning equipment. Flow wrappers, weigh-fill systems, bagging machines, and case packers used to prepare finished pasta for retail or wholesale shipment.
- Cold storage and refrigeration. Walk-in coolers, blast chillers, and freezers used for fresh, refrigerated, or frozen pasta products.
- Delivery and distribution vehicles. Refrigerated vans and trucks used to move finished product to restaurants, grocery accounts, or farmers markets.
New and used equipment can both typically be financed, which matters for pasta producers looking at refurbished Italian-made extruders or previously owned dryers as a lower-cost entry point into higher production volumes.
Qualification Requirements and Typical Rates
Qualification standards for commercial pasta making equipment financing are generally more accessible than standard unsecured business loans because the equipment itself acts as collateral, which reduces the lender's risk. Most lenders look at a combination of time in business, revenue consistency, and personal or business credit history rather than requiring years of pristine financials before approving a deal.
Typical baseline requirements include at least six months to one year in business, monthly revenue that comfortably supports the new payment, and a business or personal credit score in the fair-to-good range or better. Established manufacturers with strong revenue and longer operating history generally qualify for the most competitive rates and the largest financed amounts, while newer producers may still qualify but with a higher rate or a required down payment.
Rates on equipment financing vary based on the borrower's credit profile, time in business, the age and type of equipment, and the overall size of the deal. Newer equipment with strong resale value and a well-qualified borrower typically receives the most favorable rates, while older used equipment or a thinner credit file can result in a higher rate to offset the added risk to the lender. Getting an accurate rate quote requires submitting an application with your specific equipment details, since generic rate ranges rarely reflect what an individual pasta producer will actually be offered.
Lenders that specialize in food manufacturing and restaurant equipment, rather than general-purpose commercial lenders, often better understand the resale value and useful life of pasta production machinery. That specialization can translate into more accurate underwriting and, in many cases, better terms than a generalist lender unfamiliar with extrusion or drying equipment.
Who This Financing Is Best For
Commercial pasta making equipment financing tends to make the most sense for a specific set of pasta businesses at particular growth stages, rather than being a universal fit for every producer.
Artisan pasta makers moving from farmers market and direct-to-consumer sales into wholesale grocery or restaurant accounts are strong candidates, since that transition almost always requires higher-capacity extrusion and drying equipment than a small kitchen operation can support. Established dry pasta manufacturers replacing aging or failing equipment also benefit, particularly when downtime from an old dryer or extruder is directly costing production hours and revenue.
Restaurants and foodservice operators building an in-house pasta program, such as an Italian restaurant group producing fresh pasta for multiple locations, are another strong fit, since dedicated equipment can reduce per-unit food cost compared to buying pre-made pasta. Co-packers and private label pasta manufacturers scaling capacity to serve new retail clients also frequently use equipment financing to add production lines without waiting on a new contract's first payment cycle.
This financing is generally a weaker fit for businesses still validating product-market fit with no consistent sales history, since lenders want to see enough operating history and revenue to support the new payment obligation. Businesses in that early stage are often better served by starting with a smaller, lower-cost piece of equipment and building a track record before financing a larger production line.
Seasonal producers, such as those supplying holiday-specific stuffed pasta or gift baskets, can also benefit from equipment financing structured around their revenue cycle, with some lenders offering seasonal or step payment options that align larger payments with peak selling months rather than a flat payment every month of the year.
Financing vs. Leasing vs. Cash Purchase
Pasta producers generally choose between three paths when acquiring production equipment: an equipment loan, an equipment lease, or an outright cash purchase. Each has tradeoffs worth understanding before committing capital or credit.
| Option | Upfront Cost | Ownership | Best For |
|---|---|---|---|
| Equipment Loan | Low to none | You own the equipment once paid off | Producers who plan to keep the equipment long-term |
| Equipment Lease | Very low, sometimes $0 down | Lessor owns it; option to buy out or upgrade at term end | Producers who want to upgrade equipment frequently |
| Cash Purchase | Full purchase price | Immediate full ownership | Businesses with large cash reserves and no urgent liquidity needs |
Pro Tip: If you expect pasta extrusion technology or packaging automation to change meaningfully in the next 3 to 5 years, a lease with an upgrade option can be more cost-effective long-term than tying up cash in equipment that may need replacing sooner than expected.
How Crestmont Capital Helps Pasta Producers
Crestmont Capital works with pasta producers, artisan food manufacturers, and restaurant groups to structure food equipment financing around the realities of running a production kitchen or manufacturing facility, not a generic lending template. Our team understands that a fresh pasta operation and a dry pasta wholesale manufacturer have very different equipment needs, seasonal cash flow patterns, and growth timelines.
For producers financing extruders, sheeters, dryers, or full production lines, our commercial kitchen equipment financing programs are built to move quickly, often with same-week funding once documentation is submitted. We also offer used equipment financing for producers looking at refurbished extrusion equipment as a lower-cost path to higher production capacity.
Beyond equipment-specific funding, Crestmont Capital's working capital loans and business line of credit options help pasta businesses smooth out ingredient cost spikes, seasonal demand swings around holidays, and the gap between fulfilling a new wholesale order and receiving payment. For producers who qualify, our SBA loan programs can offer longer terms and competitive rates for larger equipment and facility investments.
If you already operate a bakery alongside your pasta line, or you are evaluating financing for a broader restaurant equipment upgrade, our guides on bakery equipment financing and restaurant equipment financing cover adjacent equipment categories that many food producers finance together.
Let's Get Your Production Line Funded
Whether you need an extruder, a dryer, or a full packaging line, Crestmont Capital can structure financing around your production schedule.
Apply Now →Real-World Scenarios
The following scenarios illustrate how pasta producers commonly use commercial pasta making equipment financing in practice. These examples are illustrative and not based on specific Crestmont Capital clients.
Scenario 1: The Farmers Market Producer Going Wholesale
An artisan fresh pasta maker who built a following at weekend farmers markets lands her first grocery chain account, which requires ten times her current weekly output. She finances a commercial sheeter and a larger mixer, allowing her to fulfill the new account's volume requirements within six weeks of signing the contract, without draining the cash she needs for ingredients and labor during the ramp-up period.
Scenario 2: The Dry Pasta Manufacturer With an Aging Dryer
A regional dry pasta manufacturer's twelve-year-old continuous dryer starts causing inconsistent moisture levels, leading to quality complaints from a major distributor. Rather than risk losing the account, the company finances a new dryer with a 60-month term, keeping monthly payments manageable while restoring consistent product quality within two weeks of installation.
Scenario 3: The Restaurant Group Building an In-House Pasta Program
A four-location Italian restaurant group decides to produce fresh pasta in-house across all locations instead of buying from a third-party supplier. They finance a central production kitchen buildout including an extruder, sheeter, and packaging equipment, reducing their per-plate pasta cost while improving quality control across the group.
Scenario 4: The Co-Packer Adding a Second Production Line
A private label pasta co-packer signs a new retail client that requires additional capacity beyond their current single-line output. They finance a second complete extrusion and packaging line, allowing them to serve both existing and new clients without disrupting current production schedules or delivery commitments.
Scenario 5: The Stuffed Pasta Specialist Automating Production
A small ravioli and tortellini producer currently hand-forming product decides to automate with a commercial ravioli former to meet growing demand from local restaurants. Financing the equipment lets them multiply daily output several times over while reducing labor costs per unit, with the equipment paying for itself well within the financing term.
Frequently Asked Questions
Your Next Production Upgrade Starts Here
Talk to Crestmont Capital about financing the pasta equipment your business needs to grow.
Apply Now →Next Steps
List the specific extruder, sheeter, dryer, or packaging equipment your production line requires, and get a vendor quote if possible.
Have recent bank statements and basic business information ready to speed up the underwriting process.
Submit your application online and get a funding decision quickly, often within one to two business days.
Once funded, get your new equipment installed and running so it starts contributing to revenue right away.
Conclusion
Commercial pasta making equipment financing gives pasta producers a way to acquire extruders, sheeters, dryers, and packaging equipment without the cash strain of an outright purchase. Whether you are scaling from farmers markets into wholesale distribution, replacing aging equipment, or adding a second production line to serve a new client, financing structures exist to match your specific growth stage and equipment needs. Crestmont Capital works with pasta producers and food manufacturers across the country to structure financing that fits real production timelines, not generic lending templates.
According to industry data from the U.S. Small Business Administration, small businesses continue to rely heavily on financing to fund equipment and growth, with SBA-guaranteed lending reaching tens of billions of dollars in the most recent fiscal year. Food manufacturing categories tracked by the U.S. Census Bureau under the pasta and dry mix manufacturing classification represent a meaningful and active segment of the broader food production economy, and financing plays a direct role in helping these businesses modernize and expand. As the broader small business financing landscape continues to evolve toward faster, more flexible funding structures, pasta producers are well positioned to take advantage of financing options built specifically around equipment-heavy manufacturing operations.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.








