
Business Financing for Sporting Goods Stores
Sporting goods retailers face massive seasonal swings and high equipment costs - the right financing partner turns those challenges into competitive advantages.
Why Sporting Goods Stores Need Business Financing
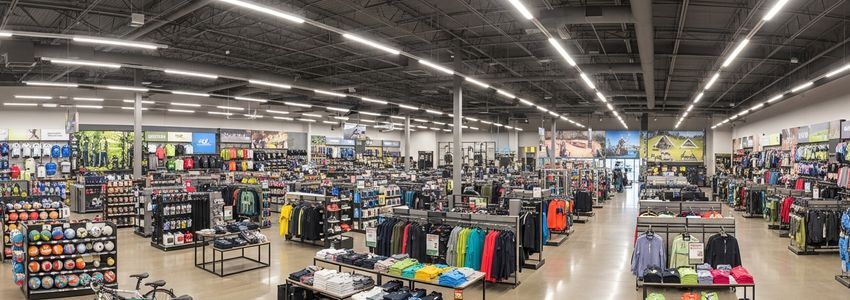
Sporting goods retail is one of the most capital-intensive segments of the retail industry. Store owners must carry a wide range of high-ticket items - bicycles priced at $500 to $5,000 each, ski equipment sets costing $800 to $2,500, treadmills and weight equipment in the $1,500 to $4,000 range - all of which must be purchased wholesale before a single customer walks through the door. This inventory-heavy model creates constant cash flow pressure that only strategic financing can address.
According to the U.S. Census Bureau, sporting goods stores generate over $52 billion in annual sales in the United States - a figure that grew significantly during and after the pandemic fitness boom. However, this industry also sees pronounced seasonality: ski shops generate 70% of annual revenue in 4 months, while water sports and cycling retailers peak sharply in spring and summer. Managing cash flow across these fluctuations requires access to flexible capital.
Beyond inventory, sporting goods store owners face substantial demands for capital in other areas. Fitness equipment showrooms require regular floor model updates to stay current with new product lines. Team sports dealers must maintain large stock of uniforms, equipment, and accessories for school and youth league contracts. Outdoor gear retailers need seasonal merchandise cycles that may include camping, hiking, hunting, and fishing across multiple peak seasons. All of these demand proactive financing strategies.
E-commerce competition from giants like Dick's Sporting Goods online, REI, and Amazon has put additional pressure on independent stores to differentiate through service, local expertise, and unique product selection. Competing effectively requires investment in customer experience, knowledgeable staff, and diversified inventory. A well-structured business line of credit or small business financing package gives independent sporting goods retailers the ammunition to compete.
Repair and rental services are also an increasingly important revenue stream for sporting goods shops, particularly in ski, bike, and paddle sports categories. Setting up these service centers requires capital investment in tools, equipment, and trained technicians. Financing these investments from cash flow alone can take years; strategic debt financing can compress that timeline to weeks.
Fund Your Sporting Goods Store Today
Pre-qualify in minutes with no impact to your credit score. Funding available in as little as 24 hours for qualifying applicants.
Apply Now - Free and FastTypes of Financing Available for Sporting Goods Stores
Crestmont Capital offers a comprehensive range of financing products designed to meet the unique needs of sporting goods retailers - from small neighborhood shops to multi-location regional chains.
Working Capital Loans
Unsecured working capital loans are ideal for sporting goods retailers who need capital quickly and do not want to pledge collateral. These loans provide lump-sum financing from $10,000 to $500,000 that can be used for any business purpose - buying pre-season inventory, bridging cash flow gaps, covering payroll, or launching marketing campaigns. Terms typically run 6 to 24 months with fixed daily or weekly payments.
Inventory Financing
Inventory financing is purpose-built for retailers like sporting goods stores that carry significant merchandise value. Using your existing or incoming inventory as collateral, you can access lines of credit up to $300,000 to fund large seasonal buys. As inventory sells, you repay the line - creating a natural rhythm that aligns financing with your business cycle.
Equipment Financing
Sporting goods stores themselves rely heavily on equipment: repair stands and tools for bike shops, boot fitting machines for ski shops, custom uniform printing equipment, and POS systems with inventory management capabilities. Equipment financing lets you acquire these tools with the equipment serving as its own collateral, preserving working capital for merchandise.
Business Line of Credit
A revolving business line of credit is particularly valuable for sporting goods stores that face multiple peak seasons throughout the year. Draw funds before each peak season to stock up, then pay down during high-revenue periods. This revolving structure means you always have access to capital without having to reapply each time.
SBA Loans
For sporting goods store owners planning major expansions - adding a new location, purchasing a building, or acquiring a competitor - SBA loans offer the most favorable terms available to small businesses: amounts up to $5 million, terms up to 25 years, and competitive interest rates. Crestmont Capital is an experienced SBA lending partner.
Fast Business Loans
When a vendor offers a steep discount on a bulk buy that expires in 72 hours, or a lease renewal deadline is looming, fast business loans deliver capital in as little as 24 hours. Minimal documentation, fast decisions, and immediate funding make these ideal for time-sensitive opportunities.
Who Qualifies for Sporting Goods Store Financing
Crestmont Capital works with sporting goods retailers across all business stages and financial profiles. Here are the qualification ranges for our key products:
| Loan Product | Min. Time in Business | Min. Monthly Revenue | Min. Credit Score | Max Loan Amount |
|---|---|---|---|---|
| Working Capital Loan | 6 months | $10,000 | 550+ | $500,000 |
| Business Line of Credit | 12 months | $15,000 | 580+ | $250,000 |
| Inventory Financing | 12 months | $12,000 | 560+ | $300,000 |
| Equipment Financing | 6 months | $8,000 | 540+ | $500,000 |
| SBA Loan | 24 months | $20,000 | 650+ | $5,000,000 |
| Fast Business Loan | 3 months | $8,000 | 500+ | $150,000 |
How the Financing Process Works
Visit our application portal and complete the simple form. You will need basic business info, 3 months of bank statements, and your desired loan amount.
A Crestmont Capital advisor reviews your application and presents multiple financing options matched to your specific needs - seasonal cash flow, inventory cycles, and growth goals.
Once you choose an offer, provide supporting documents: typically 3-6 months of business bank statements, a voided check, and your business license. Larger loans may require tax returns.
Upon final approval, funds are wired directly to your business bank account. Working capital and fast business loans can fund same or next business day. SBA loans fund within 30-90 days.
Real-World Financing Scenarios for Sporting Goods Stores
Scenario 1: Pre-Season Ski Inventory Buy - $90,000 Inventory Financing
Alpine Peak Sports is a ski and snowboard shop in Park City, Utah with $55,000 in average monthly summer revenue. Each August, the owner must place orders for the upcoming ski season: approximately $85,000 to $95,000 in skis, boots, bindings, and outerwear. Using inventory financing through Crestmont Capital, he secures $90,000 at a competitive rate. The fall and winter season generates $380,000 in revenue. After repaying the inventory line and all costs, the season yields approximately $95,000 in net operating profit.
Scenario 2: New Bike Repair Center - $35,000 Equipment Financing
Trailhead Cycles in Portland, Oregon wants to add a full-service bike repair center to increase revenue and customer loyalty. The buildout requires $28,000 in tools and equipment plus $7,000 in facility modifications. Through equipment financing, the owner acquires everything with a 36-month term at predictable monthly payments of approximately $1,050. Within 12 months, the repair center generates an additional $18,000 per month in service revenue - paying for itself in under 2 months of operation.
Scenario 3: Multi-Sport Expansion - $200,000 Small Business Loan
All-Season Athletics operates a single location in Columbus, Ohio focused primarily on team sports. The owner identifies a complementary fitness equipment and yoga accessories market and wants to add a second location in a gym-heavy part of the city. A $200,000 small business loan with a 36-month term covers leasehold improvements, initial inventory, signage, and working capital. The new location reaches $60,000 in monthly revenue within 9 months of opening.
Scenario 4: Emergency Vendor Payment - $20,000 Fast Business Loan
A retailer in Nashville, Tennessee has an unexpected opportunity to purchase $30,000 worth of discontinued premium fitness equipment at 40% below wholesale cost - but the vendor requires payment within 3 business days. The retailer secures a $20,000 fast business loan in 18 hours, combines it with cash reserves, and completes the purchase. The clearance merchandise sells out within 6 weeks at full retail for a gross profit of $24,000.
See Your Financing Options in Minutes
No hard credit pull to check your options. Real advisors, real offers, real fast. Apply today.
Check My OptionsHow Financing Options Compare for Sporting Goods Retailers
| Financing Option | Best For | Speed to Fund | Typical Rate | Collateral Required |
|---|---|---|---|---|
| Working Capital Loan | Inventory, operations, payroll | 1-3 days | 1.15-1.45 factor | No |
| Business Line of Credit | Recurring seasonal draws | 2-5 days | Prime + 2-8% | Sometimes |
| Inventory Financing | Pre-season bulk buys | 3-7 days | 8-24% APR | Inventory |
| Equipment Financing | Tools, repair equipment, POS | 2-5 days | 6-20% APR | Equipment |
| SBA Loan | Expansion, real estate | 30-90 days | Prime + 2.25-4.75% | Yes |
| Traditional Bank Loan | Established, strong credit only | 30-60 days | 5-15% APR | Yes |
Industry Trends Driving Financing Demand
The sporting goods industry is undergoing significant transformation. Forbes reports that the pandemic-era outdoor and fitness boom has largely sustained itself, with consumers continuing to prioritize active lifestyles and wellness spending. This sustained demand creates ongoing opportunity for independent sporting goods retailers - but also competitive pressure from big-box stores and online platforms.
CNBC has highlighted the growing "experience economy" trend, where consumers prefer buying gear from specialty stores that offer expert advice, fitting services, and community events. Independent sporting goods stores that lean into this differentiation - through staff expertise, in-store events, and service departments - consistently outperform those competing purely on price.
HTML Infographic: Sporting Goods Financing by Season
When Sporting Goods Stores Need Capital Most
Why Choose Crestmont Capital for Sporting Goods Store Financing
Crestmont Capital has earned its reputation as the #1 small business lender in the United States by doing one thing exceptionally well: understanding how small businesses actually operate and providing capital that fits their real-world needs. For sporting goods retailers, that means:
- Seasonal Flexibility: We understand that your revenue varies dramatically by season. Our products are designed to accommodate fluctuating cash flow rather than penalize it.
- Speed: Time-sensitive inventory opportunities and vendor deadlines do not wait for 30-day bank approvals. Crestmont funds in as little as 24 hours.
- Multiple Product Options: From a $15,000 fast loan for an opportunistic buy to a $500,000 working capital line for a major expansion, we have the right product for every situation.
- Flexible Qualification: We look at your business performance holistically - not just a credit score. Sporting goods stores with strong seasonal revenues but thin annual averages are often excellent candidates for our programs.
- No Prepayment Penalties (Most Products): Pay down your loan early when sales are strong - with no penalty on most of our products.
- Dedicated Advisors: Every client gets a real person to call - not a 1-800 number and a chatbot. Your advisor knows your business and is available when you need them.
Whether you operate a single-location specialty shop or a growing regional chain, Crestmont Capital has the experience, products, and speed to keep your sporting goods business fully stocked, competitively positioned, and ready to grow. Explore our small business loan options or contact us today to speak with a retail financing specialist.
Frequently Asked Questions
How much can a sporting goods store borrow?
Can I get financing for seasonal inventory purchases?
Do you finance sporting goods stores that sell online?
What is the minimum credit score to qualify?
Can I finance store renovations or expansions?
How long does the application process take?
What happens if I have a slow season and struggle to make payments?
Can I use financing to purchase another sporting goods store?
Is collateral required for sporting goods store financing?
How does Crestmont Capital compare to my bank?
Are there financing options specifically for team sports dealers?
Fund Your Sporting Goods Store’s Next Season
Get real offers from a real lender that understands sporting goods retail. Apply in 5 minutes, get funded in as little as 24 hours.