
Furniture Store Business Financing
Furniture retailers who invest in the right inventory, showroom experience, and customer financing programs consistently win market share - and Crestmont Capital provides the business capital to make those investments possible.
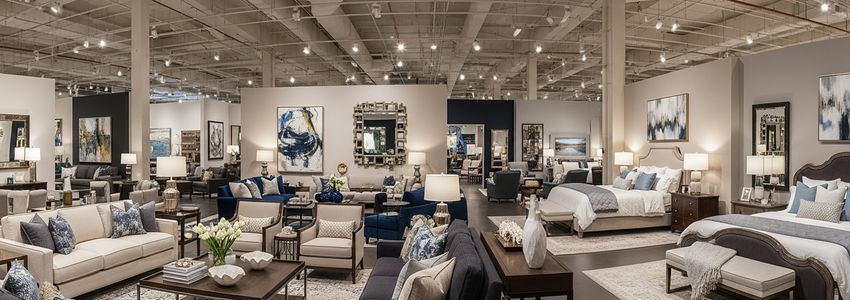
Why Furniture Stores Need Business Financing
Furniture retail is a capital-intensive business at every stage. A typical independent furniture store carries $200,000 to $400,000 in showroom floor inventory. New collections arrive seasonally, requiring capital outlays months before retail sales materialize. Vendor payment terms often require net-30 to net-60 payment while customers may take 90 to 180 days to complete a sale - especially when custom orders and delivery timelines are involved.
The U.S. furniture market generates approximately $115 billion annually, according to industry research, with independent and regional retailers capturing a significant share of the market through personalized service, local delivery, and curated product selections that large national chains cannot replicate. According to U.S. Census Bureau retail trade data, furniture and home furnishing stores are a consistent anchor of main street retail in communities across the country.
To compete effectively, furniture retailers need the capital to refresh showroom floors regularly, maintain adequate inventory depth, offer competitive customer payment plans, and invest in marketing and digital presence. Inventory financing and small business loans from Crestmont Capital make all of that possible.
As Forbes has noted, retail businesses with strong revenue and consistent sales history are among the most fundable small business categories - and furniture stores with proven track records often qualify for substantial financing at competitive rates.
Types of Financing Available for Furniture Stores
Inventory Financing
Inventory financing is the most fundamental tool for furniture retailers. Finance new collection purchases, showroom floor refresh investments, seasonal merchandise, and specialty or custom furniture inventory. The inventory serves as collateral, enabling larger loan amounts and competitive rates. Loan amounts from $25,000 to $750,000 cover the needs of furniture stores at every scale.
Equipment Financing
Equipment financing covers the fixtures and technology that make a modern furniture showroom work: custom display platforms, lighting systems, POS and inventory management systems, delivery vehicles and lift-gate trucks, and warehouse equipment for receiving and staging. Finance up to $2,000,000 with 12-60 month terms.
Working Capital Loans
Unsecured working capital loans address the recurring cash flow needs of furniture retail: covering payroll during slow months, funding marketing campaigns, paying for co-op advertising, or managing the gap between inventory purchase and sale completion.
Business Line of Credit
A revolving business line of credit gives furniture retailers flexible, on-demand access to capital. Draw funds when market opportunities arise - a supplier offering special pricing, an estate liquidation with premium furniture at below-market cost, or a competitor going out of business and vacating prime real estate.
SBA Loans
SBA 7(a) and 504 loans are ideal for furniture retailers making major long-term investments: purchasing a showroom building, acquiring a competitor, or opening a second or third location. SBA loans offer the lowest long-term rates with terms up to 25 years for real estate.
Keep Your Showroom Floor Fresh - Get Funded Today
Inventory, equipment, expansion - Crestmont Capital has furniture store financing solutions that match your business cycle.
Apply Now - Free QuoteWho Qualifies for Furniture Store Financing
| Financing Type | Min. Time in Business | Min. Monthly Revenue | Credit Score | Collateral |
|---|---|---|---|---|
| Working Capital Loan | 6 months | $15,000 | 550+ | None required |
| Inventory Financing | 1 year | $20,000 | 580+ | Inventory |
| Equipment Financing | 1 year | $15,000 | 580+ | Equipment only |
| Business Line of Credit | 1 year | $20,000 | 600+ | None required |
| SBA 7(a) Loan | 2 years | $35,000 | 650+ | Business assets |
| SBA 504 Loan | 2 years | $45,000 | 680+ | Real estate/equipment |
How the Financing Process Works
Real-World Financing Scenarios
Scenario 1: Spring Collection Showroom Refresh
A family-owned furniture store in Virginia needed to invest $175,000 in new spring collection inventory across bedroom, dining room, and living room categories. The inventory purchase needed to happen in January for February delivery - but January was historically the store's slowest revenue month. Crestmont Capital funded a $180,000 inventory loan in 5 days. The spring collection sold at a 42% gross margin, generating $255,000 in revenue through May.
Scenario 2: Adding a Mattress Gallery
A mid-size furniture store in Tennessee saw a growing market in premium mattresses but lacked the dedicated floor space and branded mattress displays to compete effectively. Adding a 1,200 sq ft mattress gallery required $95,000 in inventory, branded display fixtures, and showroom improvements. Crestmont Capital funded the project through a combination of inventory and equipment financing. The mattress gallery added $28,000/month in new revenue within 6 months.
Scenario 3: Buying a Competitor's Inventory Liquidation
When a competing furniture store in a nearby market announced it was closing, the owner of a regional furniture chain had 10 days to acquire $380,000 in high-quality floor inventory at 40 cents on the dollar. The opportunity required fast capital that could not be raised through normal operations. Crestmont Capital funded a $165,000 working capital loan within 48 hours - enough to acquire the most valuable pieces. The liquidation inventory sold at full retail, generating $285,000 in revenue over 3 months.
Scenario 4: Commercial Real Estate Purchase
A successful furniture retailer had been leasing a 15,000 sq ft showroom for 12 years. When the landlord offered to sell the building at $1,800,000, the owner saw an opportunity to convert rent payments into equity. An SBA 504 loan from Crestmont Capital financed 90% of the purchase price over 20 years at a favorable fixed rate. Monthly SBA loan payments of $9,200 were less than the rent that had been increasing annually.
Finance Your Furniture Business Growth
Inventory, showroom upgrades, new locations - Crestmont Capital has the funding solution for every furniture retailer.
Get My Free QuoteHow Financing Options Compare
| Product | Amount Range | Term | Time to Fund | Best For |
|---|---|---|---|---|
| Inventory Financing | $25K - $750K | 6 - 24 months | 3 - 7 days | Collection purchases, floor refresh |
| Working Capital Loan | $10K - $500K | 3 - 24 months | Same day - 48 hrs | Cash flow, opportunistic buys |
| Equipment Financing | $10K - $2M | 12 - 60 months | 2 - 5 days | Displays, POS, delivery vehicles |
| Business Line of Credit | $10K - $500K | Revolving | 3 - 7 days | Ongoing operational flexibility |
| Term Loan | $50K - $5M | 12 - 60 months | 3 - 7 days | New location, major renovation |
| SBA 504 | Up to $5.5M | Up to 25 years | 4 - 12 weeks | Commercial real estate purchase |
Furniture Retail Industry Snapshot
The Furniture Retail Sector By the Numbers
Sources: U.S. Census Bureau Retail Trade, IBIS World, Furniture Today
Why Choose Crestmont Capital for Your Furniture Store
Furniture retail has financial dynamics that require a lender who understands the business: high inventory values, extended sales cycles, seasonal demand peaks, and the importance of showroom investment in driving traffic and conversion. Crestmont Capital's advisors work with furniture retailers at every stage of growth.
- Inventory-Aligned Financing: We structure inventory loans around your buying cycle and seasonal patterns - not a one-size-fits-all monthly schedule.
- Large Loan Capacity: Furniture stores regularly need $100,000 to $750,000 or more for inventory. We have the capacity to fund at that scale quickly.
- Opportunistic Financing: When a competitor liquidation or supplier special offer appears, our fast business loans can fund in 24-48 hours.
- Real Estate Expertise: Our SBA 504 team helps furniture retailers own their buildings rather than rent them, converting a cost center into an asset.
- All Credit Profiles: Revenue-positive furniture stores can access financing even with credit challenges through our alternative lending programs.
Explore our full suite of small business financing options or see specific programs: inventory financing, SBA loans, and equipment financing.
Frequently Asked Questions
Can furniture stores get inventory financing?
How much can a furniture store borrow?
How does furniture inventory financing work?
Can I get financing to refresh my showroom floor with new collections?
Is there financing for furniture delivery vehicles?
Can I get an SBA loan to buy my showroom building?
What if my furniture store has seasonal revenue swings?
Can I get financing to add a mattress department?
Are there loans for furniture store acquisitions?
How fast can I get funded for an urgent inventory opportunity?
Does Crestmont Capital work with furniture franchise locations?
Ready to Invest in Your Furniture Business?
Showroom refresh, new location, or inventory expansion - Crestmont Capital has the funding to make it happen.