Mobile hearing testing van financing is the fastest way for audiology entrepreneurs, hearing clinics, and healthcare outreach organizations to put a fully equipped diagnostic vehicle on the road without draining cash reserves. This guide breaks down how financing works, what it costs, and how to structure a deal that gets your mobile hearing testing van operating in weeks instead of months.
In This Article
What Is Mobile Hearing Testing Van Financing?
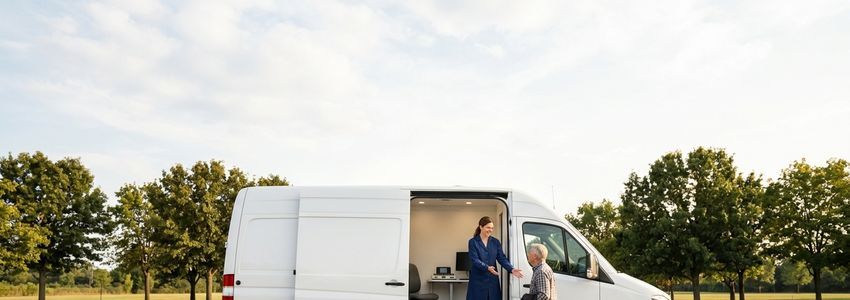
Mobile hearing testing van financing is a specialized form of equipment and vehicle financing that covers the purchase or lease of a custom-outfitted vehicle used to deliver audiology services outside a traditional clinic setting. Unlike a standard commercial van loan, this type of financing typically bundles the chassis, the build-out (soundproof booth, electrical systems, HVAC for climate-controlled testing), and the diagnostic equipment itself into a single structured deal.
A fully equipped mobile hearing testing van usually includes a sound-attenuating test booth, audiometers, tympanometers, otoscopes, hearing aid fitting and verification systems, and a dedicated workstation for patient records. Because these components come from different vendors (a vehicle upfitter, an audiology equipment manufacturer, and sometimes a separate electrical contractor), lenders who understand how to finance the full package in one transaction save business owners significant time and paperwork.
Business owners pursue mobile hearing testing van financing for several reasons: expanding an existing audiology practice into underserved rural areas, partnering with schools and senior living communities for on-site screenings, launching a standalone mobile hearing business, or supplementing a brick-and-mortar clinic with outreach capacity. In every case, the vehicle and equipment represent a significant upfront investment that most operators prefer to finance rather than pay for in cash.
The mobile health model itself has grown substantially over the past decade. Mobile clinics of all kinds, including hearing, vision, dental, and primary care units, have expanded as health systems and independent providers look for ways to reach patients who face transportation barriers, live in healthcare deserts, or simply find it difficult to schedule an in-office visit. For audiology specifically, early detection and intervention matter a great deal, and a van that can show up at a senior center, a manufacturing plant, or a school campus removes a major barrier between a patient and the hearing care they need.
Financing this kind of specialized vehicle differs meaningfully from financing a standard delivery van or service truck. Lenders need to understand not just the value of the chassis but the value and functionality of the build-out and the diagnostic equipment installed inside it. A sound booth and a set of calibrated audiometers represent real, appraisable value, and an experienced equipment finance partner will structure the deal around the total project cost rather than treating the vehicle and the equipment as two unrelated purchases.
Key Stat: According to the National Institute on Deafness and Other Communication Disorders, roughly 15% of American adults, or about 37.5 million people, report some degree of trouble hearing, and the prevalence climbs sharply after age 65 — underscoring the growing demand for accessible, on-site hearing screening services.
Ready to Put a Mobile Hearing Van on the Road?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation — apply in minutes.
Apply Now →Key Benefits of Financing a Mobile Hearing Testing Van
Financing rather than paying cash for a mobile hearing testing van preserves working capital that can be redirected toward staffing, marketing, and building referral relationships with schools, senior centers, and primary care practices. Here are the primary advantages business owners see:
- Preserve cash flow: Spread a six-figure vehicle and equipment investment across predictable monthly payments instead of a single large outlay.
- Faster time to revenue: Structured financing for the full package (vehicle, build-out, and diagnostic equipment) gets you on the road faster than piecing together separate loans.
- Flexible structures: Choose between financing and leasing depending on whether you want to own the asset outright or prefer lower payments with upgrade flexibility.
- Equipment stays current: Leasing options make it easier to upgrade audiometric equipment as newer diagnostic technology becomes available.
- Potential balance sheet advantages: Certain lease structures keep the asset off your balance sheet, which can be useful for businesses managing debt-to-equity ratios with other lenders.
- Build business credit: On-time payments on an equipment or vehicle loan help establish and strengthen your business credit profile over time.
How Mobile Hearing Testing Van Financing Works
The process of financing a mobile hearing testing van follows a fairly consistent path, whether you are an established audiology practice adding a second location on wheels or a new operator launching a standalone mobile hearing business.
Quick Guide
How Mobile Hearing Testing Van Financing Works — At a Glance
Obtain pricing from your upfitter and audiology equipment vendor, or let your lender help source a total project cost.
Provide basic business information, recent bank statements, and the vendor quote for underwriting review.
Most equipment and vehicle financing decisions come back within 24 to 48 hours, with clear rate and term options.
Once documents are signed, funds are released directly to the vendor so your build-out and equipment installation can begin.
Once the build-out is complete and the van passes inspection, you're ready to begin scheduling mobile screenings.
Underwriters evaluating mobile hearing testing van financing typically look at time in business, personal and business credit history, cash flow from bank statements, and the total project cost relative to the expected revenue the mobile unit will generate. Because the underlying vehicle and diagnostic equipment both hold resale value, many lenders are comfortable offering longer terms than they would for a pure working capital loan, which keeps monthly payments manageable.
Most approvals fall into one of two payment structures: a fixed-term installment loan where you build equity in the van and equipment from day one, or a lease where you make lower monthly payments with the option to purchase, renew, or upgrade at the end of the term. The right choice depends on how long you expect to use this specific vehicle configuration and whether equipment technology in your space is evolving quickly.
Timing matters in this process. Vehicle upfitters and specialized audiology equipment manufacturers often have lead times of their own, separate from the financing timeline. Smart operators start the financing conversation as soon as they have a vendor quote in hand, rather than waiting until the build is complete, since approval and funding can often run in parallel with the build-out schedule. This overlap can shave weeks off the total time between deciding to launch a mobile unit and actually seeing patients.
It's also worth understanding how lenders view the resale and residual value of a mobile hearing testing van compared to a standard commercial vehicle. Because the diagnostic equipment is specialized and the pool of buyers for a used mobile hearing unit is smaller than for a generic cargo van, some lenders will structure slightly more conservative terms on the equipment portion of the deal while remaining competitive on the vehicle financing itself. Working with a lender familiar with mobile health vehicles, rather than a generalist auto lender, often results in a more realistic and favorable structure.
Types of Mobile Hearing Testing Van Financing
Not every mobile hearing testing van project looks the same, and financing structures vary to match different business needs and credit profiles.
- Equipment financing: Covers the audiometric and diagnostic equipment specifically, often used when the vehicle itself is already owned or financed separately.
- Commercial vehicle financing: Covers the van or cutaway chassis itself, sometimes combined with the upfit cost if the same lender handles both.
- Equipment leasing: Lower monthly payments with the flexibility to upgrade audiology equipment at the end of the lease term as technology advances.
- SBA-backed loans: For established practices with strong financials, SBA loan programs can offer longer terms and competitive rates for larger mobile health investments.
- Working capital add-ons: Some operators pair their van financing with a working capital facility to cover staffing, marketing, and fuel costs during the ramp-up period.
Equipment covered under most mobile hearing testing van financing packages includes sound booths, audiometers, tympanometers, otoacoustic emissions (OAE) testing equipment, hearing aid programming stations, patient intake software and tablets, backup generators, and the HVAC and electrical upgrades needed to maintain a controlled testing environment inside the vehicle.
Some operators also choose to finance ancillary items alongside the core diagnostic package, such as exterior vehicle wraps for branding and visibility, wheelchair lift systems to improve accessibility, telehealth connectivity equipment for remote consultation with physicians, and secure data storage systems to keep patient records compliant with healthcare privacy regulations. Bundling these items into the same financing agreement, rather than paying for them separately out of pocket, keeps the entire launch budget organized under one predictable monthly payment.
Another consideration is whether to finance a new or used base vehicle. Many mobile hearing testing van operators start with a used cutaway van or box truck chassis and invest the bulk of their budget into a high-quality build-out and equipment package, since the diagnostic equipment is what actually drives patient outcomes and revenue. A knowledgeable equipment finance partner can structure financing around either a new or used chassis, as long as the vehicle passes a basic condition and age assessment.
Who Mobile Hearing Testing Van Financing Is Best For
This type of financing is well suited to a specific set of business models within the audiology and hearing healthcare space:
- Established audiology practices looking to extend their reach into rural communities, senior living facilities, or school districts without opening a second brick-and-mortar location.
- Independent audiologists launching a standalone mobile hearing testing business to serve patients who cannot easily travel to a clinic.
- Hearing aid retail chains adding a mobile outreach unit to generate leads and conduct initial screenings before referring patients to a storefront location.
- Occupational health providers offering on-site hearing conservation screenings for manufacturing, construction, and industrial clients subject to workplace noise exposure requirements.
- Nonprofit and community health organizations expanding access to hearing care in underserved areas, often in partnership with local health departments.

Comparing Mobile Hearing Testing Van Financing to Other Funding Options
Business owners evaluating how to fund a mobile hearing testing van often compare equipment-specific financing against more general small business funding products. Here is how the primary options stack up:
| Financing Option | Best For | Typical Terms | Collateral |
|---|---|---|---|
| Equipment/Vehicle Financing | Purchasing the van and diagnostic equipment as one bundled package | 2-7 years | The financed vehicle and equipment itself |
| Equipment Leasing | Lower monthly payments, easier equipment upgrades | 2-5 years | Leased equipment (lender retains ownership) |
| SBA 7(a) or 504 Loan | Larger, established practices with strong financials | Up to 10-25 years | Business assets, sometimes personal guarantee |
| Unsecured Working Capital | Covering staffing, fuel, and marketing alongside the van purchase | 3-24 months | None (based on cash flow) |
In most cases, equipment and vehicle financing offers the most favorable combination of approval speed, reasonable rates, and manageable monthly payments for a mobile hearing testing van project, because the lender has tangible collateral in the vehicle and diagnostic equipment. Working capital products are better reserved for operating costs rather than the vehicle purchase itself.
How Crestmont Capital Helps Finance Your Mobile Hearing Testing Van
Crestmont Capital works with audiology practices, independent hearing care providers, and mobile health operators to structure financing that covers the full scope of a mobile hearing testing van project, from the vehicle chassis to the diagnostic equipment installed inside it. Rather than forcing you to piece together separate loans from a vehicle lender and an equipment lender, Crestmont can structure a single medical equipment financing package that covers both.
For practices that already own a chassis and need financing for the specialized audiology build-out, Crestmont's healthcare equipment financing programs are designed specifically for diagnostic and clinical equipment like audiometers, OAE systems, and sound booths. If you still need to acquire the vehicle itself, Crestmont's commercial van financing options can be paired with the equipment package for a coordinated funding timeline.
Practices with strong credit and multi-year growth plans may also benefit from exploring SBA loan programs through Crestmont, which can offer longer repayment terms for larger mobile health investments. For a broader look at financing options available to hearing care providers, Crestmont's audiology practice loans guide covers financing strategies beyond vehicles and equipment, including working capital and expansion funding. Operators building out other types of mobile medical units may also find Crestmont's mobile phlebotomy equipment financing guide useful, since many of the underwriting and build-out considerations overlap.
Crestmont's application process is built for speed: a short online application, recent bank statements, and a vendor quote are usually all that's needed to get a same-day or next-day decision, so your mobile hearing testing van project doesn't stall waiting on financing.
Crestmont also works with practices that need to refinance or restructure existing equipment debt tied to a mobile unit, whether to free up cash flow, extend a term, or add a second vehicle to an existing route. If your mobile hearing testing business is growing and you're considering a second or third van to cover additional territory, the same streamlined underwriting process applies, and prior successful payment history with Crestmont can make subsequent approvals even faster. For practices that also operate a fixed clinic location alongside their mobile unit, Crestmont's broader healthcare equipment financing programs can cover in-office upgrades at the same time, simplifying your relationship to a single financing partner across your whole operation.
Let's Structure Your Mobile Hearing Van Financing
Bundle your vehicle and audiology equipment into one streamlined application. No obligation.
Apply Now →Real-World Scenarios
Scenario 1: Rural expansion for an established practice. An audiology practice with two clinic locations wanted to reach patients in surrounding rural counties who couldn't easily travel for appointments. Financing a mobile hearing testing van allowed the practice to schedule weekly circuit routes through underserved towns, generating new patient volume without the overhead of a third physical location.
Scenario 2: School district partnership. An independent audiologist financed a mobile unit specifically to contract with local school districts for annual hearing screenings required under state health guidelines. The predictable contract revenue from the district made it straightforward to project monthly payments against guaranteed income.
Scenario 3: Senior living outreach. A hearing aid retailer financed a mobile testing van to visit assisted living and senior living communities on a rotating schedule, screening residents on-site and referring those who needed hearing aids back to the retail location for fitting and purchase.
Scenario 4: Occupational hearing conservation. An occupational health provider financed a mobile hearing testing van to deliver on-site hearing conservation screenings for manufacturing and construction clients, helping those employers meet workplace safety and noise exposure documentation requirements without sending workers off-site.
Scenario 5: Standalone mobile-only startup. A newly licensed audiologist chose to launch a mobile-only hearing practice rather than lease a traditional storefront, financing the van and full equipment package to keep overhead low while building a client base across several counties.
Scenario 6: Expanding from one van to a small fleet. After two successful years running a single mobile hearing testing van, an operator used a second round of equipment financing to add a second vehicle, doubling weekly screening capacity and allowing the business to serve two separate regional routes simultaneously without pausing service on the original route.
Scenario 7: Telehealth-integrated mobile unit. A hearing healthcare group financed a mobile van equipped with telehealth connectivity, allowing an on-site technician to conduct the physical screening while a remote audiologist reviewed results and consulted with the patient in real time, extending the reach of a small clinical staff across a much wider service area.
Frequently Asked Questions
Your Mobile Hearing Van Project Starts Here
Talk to a financing specialist about your vehicle and equipment needs today.
Apply Now →Next Steps
Collect pricing on your vehicle chassis, upfit, and audiology equipment package.
Pull together recent bank statements and basic business information before applying.
Submit your application online and get a decision typically within 24 to 48 hours.
Sign your documents and get funds disbursed to your vendors so the build-out can begin.
Conclusion
Mobile hearing testing van financing gives audiology practices, independent hearing care providers, and health outreach organizations a practical way to expand access to screening and diagnostic services without the overhead of a second physical location. By bundling the vehicle, build-out, and specialized equipment into a single structured financing package, business owners can move from planning to patient visits in a matter of weeks rather than months. Whether you're extending an established practice into rural communities or launching a standalone mobile hearing business, the right financing partner can make the difference between a stalled project and a van on the road generating revenue.
As demand for accessible, on-site hearing care continues to grow across rural communities, senior living populations, schools, and workplaces with occupational noise exposure, the business case for a mobile hearing testing van has never been stronger. The operators who move quickly to secure financing and get their vehicle built out and on the road are the ones best positioned to capture that demand before competitors in their region do the same. A well-structured mobile hearing testing van financing package removes the single biggest obstacle, the upfront cost, and lets you focus on what matters most: delivering hearing care to patients who need it, wherever they are.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.