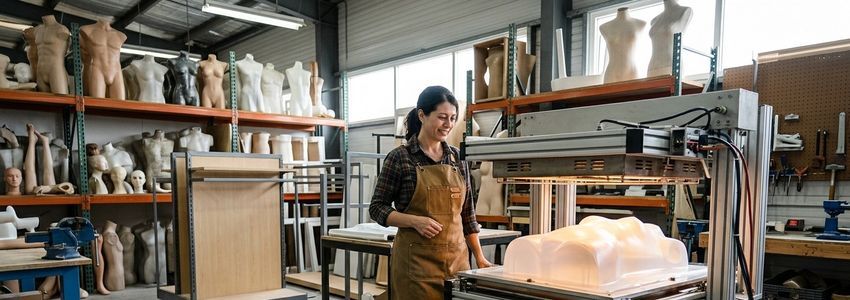
Mannequin and display fabrication equipment financing gives shops that build mannequins, retail fixtures, and visual merchandising displays a way to acquire vacuum formers, CNC routers, molding equipment, and finishing tools without draining cash reserves. For fabricators supplying department stores, boutiques, trade show builders, and museum or theatrical clients, having the right machinery on the floor often determines whether a shop can accept a large order or has to turn it down.
This guide covers exactly how mannequin and display fabrication equipment financing works, which equipment typically qualifies, how much shops commonly finance, and how to choose between a loan, a lease, or an SBA-backed option. Whether you run a small custom mannequin studio or a full-scale display fabrication operation supplying national retail chains, the details below will help you make a confident funding decision.
In This Article
What Is Mannequin and Display Fabrication Equipment Financing?
Mannequin and display fabrication equipment financing is a category of business equipment financing built specifically for shops that design and manufacture mannequins, retail fixtures, visual merchandising displays, and point-of-sale structures. Instead of paying cash upfront for expensive fabrication machinery, a fabricator borrows or leases the funds needed to acquire it, then repays the lender over a set term while the equipment is already producing revenue on live orders.
This type of financing typically covers the machinery and shop infrastructure mannequin and display fabricators depend on daily: vacuum forming machines for shaping plastic and fiberglass mannequin shells, CNC routers and mills for cutting fixture panels and armatures, injection molding equipment for high-volume mannequin parts, fiberglass and resin casting stations, paint and finishing booths, and 3D printers used for prototyping new mannequin poses or fixture designs.
Because the equipment itself generally secures the financing, lenders can often approve fabrication businesses with less documentation and a faster turnaround than an unsecured loan would require. That structure makes equipment financing one of the most accessible funding tools for small and mid-size display fabrication shops, including newer businesses that have not yet built years of financial history.
Key Benefits of Financing Your Fabrication Equipment
Mannequin and display fabrication is an equipment-intensive business. A single vacuum forming machine or injection molder can cost tens of thousands of dollars, and most shops need several major machines working in sequence to deliver a finished mannequin line or fixture order on schedule. Financing lets owners put that equipment to work immediately instead of waiting months or years to save up the cash.
- Preserve working capital. Keep cash available for materials, payroll, and order deposits instead of tying it up in a single equipment purchase.
- Match payments to order cycles. Monthly payments can be structured around the cash flow of seasonal retail orders rather than a single lump-sum outlay.
- Take on larger contracts. New capacity from an additional vacuum former, CNC router, or finishing line lets a shop bid on national retail and chain-store contracts it previously had to pass on.
- Access to newer, more capable machinery. Financing makes it realistic to upgrade to faster, more precise equipment that improves finish quality and reduces production time per unit.
- Potential tax advantages. Many equipment financing structures allow a business to expense a significant portion of the equipment cost in the year it is placed into service, though owners should always confirm specifics with their own accountant.
- Predictable budgeting. Fixed monthly payments make it easier to forecast overhead against upcoming seasonal retail display cycles.
Ready to Equip Your Fabrication Shop?
Get fast, flexible equipment financing from the #1 business lender in the U.S. No obligation, apply in minutes.
Apply Now →How Mannequin and Display Fabrication Equipment Financing Works
The process is more straightforward than most fabrication business owners expect. Here is the typical path from application to equipment on the shop floor:
- Identify the equipment. Get a quote from your equipment vendor, or have a target price range ready if you are financing multiple pieces of machinery at once.
- Submit an application. Most lenders ask for basic business information, time in business, and recent bank statements. Many fabrication shops qualify with a simple application-only process for smaller equipment amounts.
- Underwriting review. The lender evaluates the business's revenue, credit profile, and the resale value of the specific equipment being financed.
- Approval and terms. You receive approved terms covering the financed amount, monthly payment, term length, and any down payment requirement.
- Funding and delivery. Once terms are signed, funds are released to the vendor (or reimbursed to you), and the equipment is delivered and installed in your shop.
- Repayment. You make fixed monthly payments over the agreed term while the equipment is already generating revenue on active fabrication orders.
Approval timelines vary by lender and loan size, but many equipment financing applications for amounts under $250,000 can be approved within one to three business days when documentation is complete, a pace Forbes Advisor's equipment financing guide notes is common across online and alternative lenders.
Types of Equipment You Can Finance
Mannequin and display fabrication shops run a wide mix of machinery, and most equipment financing programs are flexible enough to cover several categories in a single application. Common equipment types financed by shops in this space include:
- Vacuum forming machines for shaping plastic and fiberglass mannequin shells and display panels
- Injection molding equipment for high-volume mannequin parts and fixture components
- CNC routers and mills for cutting fixture panels, armatures, and display bases
- Fiberglass and resin casting stations for sculptural mannequin forms
- Paint booths and finishing equipment, including airbrush and spray systems for lifelike mannequin finishes
- 3D printers for prototyping new mannequin poses, faces, and custom fixture designs
- Table saws, panel saws, and edge banders for wood and laminate fixture construction
- Welding equipment for metal armatures and structural display frameworks
- Delivery vehicles and lift equipment used for installation at retail and trade show sites
Key Stat: The U.S. Census Bureau's retail trade economic census data tracks over one million retail establishments nationwide, a market that depends on a steady pipeline of visual merchandising, mannequin, and fixture replacement work every season.
By the Numbers
Mannequin and Display Fabrication Equipment Financing - Key Figures
1M+
U.S. retail establishments needing display and fixture work
$5K-$500K
Typical equipment financing amount range
3-10 Yrs
Common repayment terms, matched to equipment life
24-72 Hrs
Possible approval time for smaller equipment amounts
Who This Financing Is Best For
Mannequin and display fabrication equipment financing tends to fit a specific set of business situations particularly well. It is most useful for:
- Established mannequin and fixture shops adding a second vacuum former, injection molder, or finishing line to keep up with growing order volume.
- Visual merchandising fabricators expanding from small boutique accounts into national retail chain contracts, which often require higher-capacity, more precise equipment.
- Retail chains with in-house fixture departments that need to replace aging machinery without a large capital outlay from an annual operating budget.
- New fabrication businesses that have secured their first major department store or boutique contract but do not yet have the full equipment lineup required to deliver it.
- Growing shops that want to bid on larger RFPs from retail chains and trade show builders but are currently equipment-constrained.
If your business is capital-constrained but has a clear, immediate use for the equipment, financing is generally a stronger fit than waiting to self-fund a purchase, particularly when a specific order or seasonal deadline is on the line.
Equipment Loan vs. Equipment Lease vs. SBA Loan
There is no single "best" option for every mannequin and display fabrication business. The right choice depends on whether you want to own the equipment outright, how quickly technology in your shop tends to change, and how much documentation you are prepared to provide.
| Feature | Equipment Loan | Equipment Lease | SBA 7(a)/504 Loan |
|---|---|---|---|
| Ownership | You own the equipment once paid off | Option to return, renew, or buy out | You own the equipment once paid off |
| Down payment | Often 0-20% | Often minimal or none | Typically 10-20% |
| Approval speed | Fast, often 1-3 business days | Fast, often 1-3 business days | Slower, often 30-90 days |
| Best for | Equipment you plan to use long-term | Fast-evolving tech you may want to upgrade | Large purchases with time to spare |
| Credit flexibility | Moderate, asset-backed underwriting helps | Often the most flexible for newer businesses | Strictest credit and documentation requirements |
Pro Tip: If a retail order has a hard seasonal delivery deadline, such as a holiday display rollout, an equipment loan or lease is usually the more realistic path. SBA loans offer strong rates but the 30-90 day underwriting timeline rarely lines up with a seasonal production schedule.
How Crestmont Capital Helps Mannequin and Display Fabrication Businesses
Crestmont Capital works with mannequin manufacturers, retail fixture fabricators, and visual merchandising shops across the country to structure fabrication equipment financing around the realities of order-driven, seasonal production work. Rather than a one-size-fits-all application, Crestmont looks at the equipment itself, the order volume driving the purchase, and the shop's overall cash flow to structure a payment plan that fits.
For shops that need working capital alongside new machinery, such as covering materials and labor while a large retail order is in production, Crestmont also offers unsecured working capital loans that can run alongside an equipment financing plan. Businesses that prefer a government-backed structure for a larger equipment package can also explore SBA loan options through Crestmont's lending network.
Crestmont has also financed equipment for adjacent fabrication niches that share many of the same machinery needs as mannequin and display builders, including shops covered in Crestmont's guides to CNC router financing and trade show booth fabrication equipment financing, two fabrication segments that overlap heavily with mannequin and display work in both equipment and skill set.
For shops that want the flexibility to add equipment over time rather than financing a single large purchase up front, Crestmont's equipment leasing programs allow incremental additions to a shop's machinery lineup as new orders come in, without renegotiating a new loan each time. Shops that also need general working capital for day-to-day operations can review Crestmont's broader small business financing options alongside their equipment plan.
Building Your Next Retail Display Line?
Get the fabrication equipment you need funded quickly, with flexible terms built around your production timeline.
Apply Now →Real-World Scenarios
Scenario 1: The growing mannequin shop. A 15-person mannequin manufacturing studio wins a contract to supply a regional department store chain with 400 new mannequin forms ahead of a seasonal reset. The existing vacuum former is booked solid with ongoing work, so the shop finances a second vacuum forming machine to run both the new order and existing accounts in parallel without missing the delivery window.
Scenario 2: The new business with its first big contract. A two-person custom mannequin studio lands its first boutique chain contract, requiring 50 custom-posed forms with a specialty matte finish. The shop does not yet own a dedicated finishing booth, so it finances the equipment against the signed contract, delivering the order on time and building a track record for future retail work.
Scenario 3: The in-house retail fixture department. A mid-size retail chain's internal visual merchandising team is running a 12-year-old CNC router that increasingly needs repairs and slows down fixture production. Rather than pulling from the chain's annual capital budget, the department finances a new router with predictable monthly payments that fit inside its existing visual merchandising line item.
Scenario 4: The trade show fabricator expanding into retail. A fabrication company that has built its business on trade show booths wants to move into higher-margin mannequin and fixture work, which requires vacuum forming and injection molding equipment it does not currently own. Financing a new vacuum former and casting station lets the shop bid competitively on its first department store RFP.
Scenario 5: The seasonal surge. A display fabrication shop wins three simultaneous retail fixture orders ahead of a busy holiday reset season. Rather than delaying any of the three orders, the shop finances a package of equipment, including a second injection molder and an additional finishing station, to run all three production lines at once.
Frequently Asked Questions
Next Steps
Get a quote from your equipment vendor, or estimate a target range if financing multiple machines.
Most applications require a few months of business bank statements to verify cash flow.
Apply online in minutes with basic business details and your equipment quote.
Once approved, funds are released to your vendor and your equipment ships to your shop.
Take On Your Next Retail Fixture Order with Confidence
Crestmont Capital helps mannequin and display fabrication shops finance the equipment behind every successful production run. Apply in minutes.
Apply Now →Conclusion
Mannequin and display fabrication equipment financing gives mannequin manufacturers, retail fixture fabricators, and in-house visual merchandising departments a realistic path to the vacuum formers, injection molders, CNC routers, and finishing equipment that modern retail work demands. Rather than turning down an order because the shop lacks the right machinery, financing lets fabrication businesses say yes to bigger, more complex production runs and build long-term relationships with retail clients that need reliable fixture partners.
Whether you choose an equipment loan, an equipment lease, or an SBA-backed option, the right financing structure should match your shop's cash flow and the timeline of the order driving the purchase. If you are ready to explore mannequin and display fabrication equipment financing for your shop, Crestmont Capital can help you find the structure that fits.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.