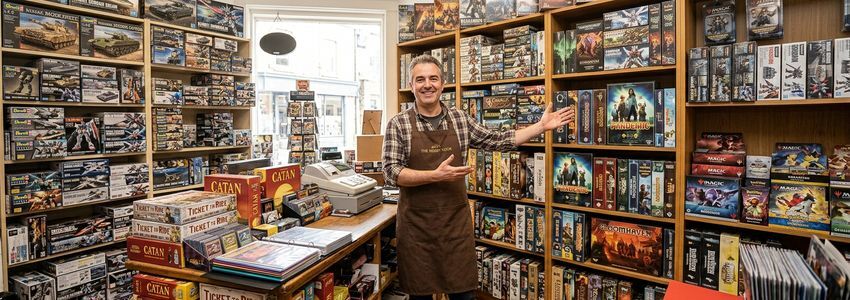
Hobby shop inventory financing gives independent retailers the working capital to stock trading cards, model kits, board games, RC vehicles, puzzles, miniatures, and collectibles ahead of the demand cycles that drive this industry. For hobby shop owners, timing is everything: a new expansion set, a convention-exclusive figure, or a holiday season surge can sell through in days, and if the shelves are not stocked when customers walk in, that sale goes to a competitor or an online marketplace instead.
This guide covers how hobby shop inventory financing works, who qualifies, the types of funding available, and how to decide whether a line of credit, a lump-sum loan, or another structure fits your buying cycle best.
In This Article
What Is Hobby Shop Inventory Financing?
Hobby shop inventory financing is business funding specifically used to purchase the merchandise a specialty retailer sells, rather than funding payroll, rent, or a one-time capital expense. It can take the form of a revolving line of credit, a short-term working capital loan, or in some cases a vendor-specific arrangement negotiated through a distributor.
The core idea is simple: instead of waiting for cash from last month's sales to accumulate before placing the next order, a hobby shop owner uses financing to buy inventory now, sell it to customers, and repay the financing from that revenue. This keeps the buying cycle moving even when a big opportunity, like a liquidating competitor's stock or a limited print run, shows up faster than cash flow alone can support.
Hobby and collectibles retail is a category where this matters more than in many other industries. Trading card releases, tabletop game expansions, scale model kits, and licensed collectibles often have fixed print runs and firm release dates. A shop that cannot place a large enough pre-order misses out entirely, since reprints are not guaranteed and secondary market prices can spike well above the original wholesale cost.
Key Benefits
- Buy in larger quantities: Larger orders often come with better per-unit pricing from distributors, improving margin on every unit sold.
- Never miss a release window: Pre-order deadlines for trading cards, games, and models do not wait for your cash flow to catch up.
- Smooth out seasonality: Build inventory ahead of the holiday season or back-to-school rush without draining your operating cash.
- Seize opportunistic buys: Act quickly when a distributor offers a closeout deal or a competitor liquidates stock.
- Preserve cash reserves: Keep a cushion for rent, payroll, and utilities instead of tying it all up in shelf stock.
- Support multi-category growth: Expand into a new product line, such as adding board games alongside trading cards, without a slow self-funded ramp-up.
Key Stat: According to the U.S. Small Business Administration, access to capital remains one of the most commonly cited barriers for independent retailers, especially those that depend on seasonal or limited-release merchandise cycles.
How It Works
The process for securing hobby shop inventory financing generally follows the same core steps regardless of which product type you choose.
Step 1: Determine your inventory need. Identify the specific purchase driving the request, whether that is a seasonal restock, a new product line, or a bulk purchase tied to a release date or distributor discount.
Step 2: Gather your financial documentation. Most lenders request three to six months of business bank statements, basic business formation documents, and sometimes a recent tax return. The exact requirements scale with the requested funding amount.
Step 3: Apply and get matched to a product. Based on your sales history, time in business, and the purpose of the funds, a lender will typically recommend either a revolving line of credit for recurring restocks or a lump-sum loan for a one-time bulk purchase.
Step 4: Review terms and accept funding. Compare the total repayment cost, the repayment schedule, and any fees before accepting an offer. Qualified applicants are often funded within one to three business days.
Step 5: Place your order and repay over time. Use the funds to pay your distributor or wholesaler, stock the shelves, and repay the financing according to the agreed schedule as the new inventory generates sales.
Ready to Stock Up Before the Next Rush?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation, apply in minutes.
Apply Now →Types of Inventory Financing
Several financing structures can support a hobby shop's inventory needs, and the right choice depends on how often you need capital and how predictable your buying cycle is.
Business line of credit. A revolving business line of credit lets you draw funds as needed, repay, and draw again, which fits hobby shops that reorder fast-moving categories like trading cards or paint supplies on a weekly or monthly basis.
Unsecured working capital loan. An unsecured working capital loan delivers a lump sum that works well for a single large purchase, such as pre-ordering a major expansion set or stocking up for a convention appearance.
SBA loan. For established hobby shops planning a larger, long-term inventory buildup, such as opening a second location, an SBA loan can offer a lower rate in exchange for a longer approval timeline.
Merchant cash advance. A merchant cash advance can provide same-day or next-day funding for an urgent purchase, though the cost of capital is typically higher than other options, making it best suited for short-term needs rather than routine restocking.
Inventory-specific financing. Some lenders structure funding directly around the inventory financing model, where approval and sometimes the credit limit are tied more closely to the value and turnover rate of the stock being purchased.
| Financing Option | Best For | Typical Speed | Repayment Style |
|---|---|---|---|
| Business Line of Credit | Recurring restocks of fast-moving items | 1-3 business days | Draw as needed, repay, reuse |
| Unsecured Working Capital Loan | One-time bulk inventory purchase | 1-2 business days | Fixed term, set schedule |
| SBA Loan | Larger, planned seasonal buildup | 2-8 weeks | Long term, lower rate |
| Merchant Cash Advance | Urgent, short-term cash need | Same day to 1 day | Daily or weekly remittance |
Who It's Best For
Hobby shop inventory financing tends to be the right fit for a specific set of business situations.
- Independent hobby, game, comic, or collectibles shops with at least six months to a year of sales history
- Retailers facing a hard pre-order deadline for a limited release or convention-exclusive item
- Shops with strong seasonal patterns around the holidays, back-to-school, or major release calendars
- Owners looking to add a new product category without draining existing operating cash
- Businesses that have an opportunity to buy discounted bulk inventory from a liquidating distributor or closing competitor
It is a less natural fit for a brand-new shop with no sales history at all, though some lenders will still consider smaller funding amounts based on the owner's personal credit and overall business plan.
Pro Tip: Order limited releases and convention exclusives on a schedule tied to your financing availability, not just your current bank balance, so a strong buying opportunity never slips away because cash is temporarily tied up in shelf stock.
Comparisons to Other Options
Many hobby shop owners initially consider self-funding inventory purchases out of personal savings or simply waiting until enough cash accumulates from prior sales. While this avoids financing costs entirely, it also means missing fast-moving opportunities and consistently under-ordering relative to real demand, which pushes customers toward competitors or online resellers.
A business credit card is another common alternative. Credit cards offer convenience and sometimes rewards, but typically carry higher ongoing interest rates than a dedicated business line of credit or working capital loan, and credit limits are often lower than what a growing hobby shop needs for a major seasonal order.
Trade credit from a distributor, where the distributor allows payment terms of 30 to 60 days, can also help bridge short gaps. However, trade credit terms are set by the distributor and are not always available for every product line or during high-demand release windows, which is where dedicated financing fills the gap.
How Crestmont Capital Helps
Crestmont Capital works with specialty and hobby retailers to structure financing around how this industry actually buys and sells merchandise. Rather than a one-size-fits-all loan product, our team looks at your sales history, seasonality, and the specific purchase you are trying to fund to recommend the right structure.
Options available through Crestmont Capital include a business line of credit for ongoing restocks, an unsecured working capital loan for a one-time bulk purchase, and broader small business financing for shops planning a larger expansion. Owners who are still comparing options across the broader collectibles and specialty retail category may also find it useful to review our guide on comic book store financing, which covers many of the same seasonal buying challenges from a related angle.
Applications can typically be completed online in minutes, with funding decisions and disbursement often happening within one to three business days for qualified businesses.
Never Miss a New Release Again
See how much working capital your hobby shop qualifies for today. Quick application, fast decision.
Check Your Options →Real-World Scenarios
Scenario 1: The trading card release deadline. A hobby shop owner learns that a major trading card manufacturer is releasing a highly anticipated new set with a strict pre-order cutoff two weeks away. Using a business line of credit, the owner places a larger pre-order than cash on hand would allow, sells through the allocation within days of release, and repays the draw well ahead of the next restock cycle.
Scenario 2: Holiday season buildup. A board game and puzzle retailer uses a working capital loan in September to stock up for the November and December shopping rush, more than doubling typical inventory levels across best-selling categories. The increased selection captures sales that would otherwise have gone to larger online retailers with broader stock.
Scenario 3: A closing competitor's liquidation. When a nearby hobby shop announces it is closing, the remaining inventory, including hard-to-find out-of-print items, goes up for sale at a steep discount. An owner with financing already in place is able to move quickly, acquiring the bulk lot before another buyer does and reselling individual items at full retail margin.
Scenario 4: Expanding into a new product category. A shop that has primarily sold tabletop games decides to add a trading card and collectibles section based on customer requests. Rather than slowly testing the category with minimal stock, the owner uses a lump-sum loan to launch with a fuller selection from day one, improving the odds the new section succeeds.
Scenario 5: A convention or trade show appearance. A hobby retailer books a booth at a regional gaming or collectibles convention and needs to stock significantly more inventory than the storefront alone requires. Short-term financing covers the incremental purchase, and the booth sales from the multi-day event repay the advance.
Next Steps
Pin down the specific purchase, release date, or seasonal window driving the request.
Have three to six months of business bank statements ready to speed up review.
Submit your application and compare the structures you are matched to.
Place your order and repay as the new inventory sells through.
Quick Guide
How Hobby Shop Inventory Financing Works, At a Glance
Submit basic business details and recent bank statements in minutes.
A lender reviews your sales history and recommends a line of credit or term structure.
Qualified applicants can be funded in as little as one to three business days.
Place your order with distributors and repay as the business generates revenue.
Stocking Smart for Every Season
Inventory planning in the hobby retail world is as much art as science. Unlike a grocery store restocking staple goods, a hobby shop owner has to forecast demand for items that may only be available for a limited print run, track secondary market pricing trends on collectibles, and juggle multiple product categories that each have their own release calendars. This complexity is exactly why flexible financing, rather than a single rigid loan product, tends to serve this industry best.
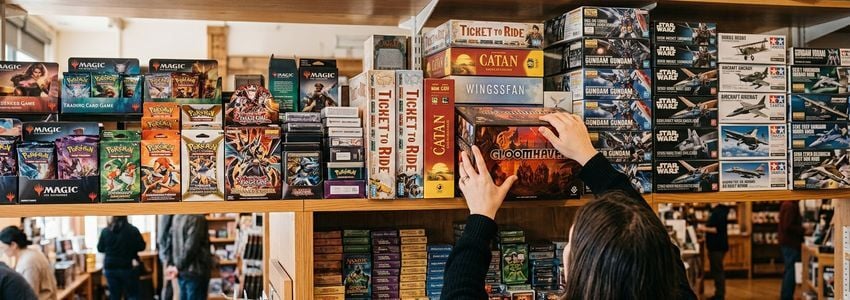
Owners who build a relationship with a financing partner before they need it, rather than scrambling when a deadline appears, are consistently better positioned to act on short-notice opportunities. A pre-approved line of credit, for example, can often be drawn against within hours once a buying decision is made, compared to starting a loan application from scratch under time pressure.
Key Stat: U.S. Census Bureau retail trade data consistently shows hobby, toy, and game stores experience some of the sharpest seasonal swings in the specialty retail sector, making working capital timing especially important for this category.
It is also worth tracking which categories within your store turn over fastest. Trading cards and blind-box collectibles, for instance, often move much faster than large-format display models or high-end scale kits. Matching your financing structure, a revolving line for fast turnover, a term loan for slower-moving bulk purchases, to these different inventory profiles helps keep total financing costs proportional to how quickly each category converts back into cash.
Build the Hobby Shop Inventory Customers Love
Apply today and get a funding decision fast, with no long-term commitment required.
Apply Now →Frequently Asked Questions
What is hobby shop inventory financing?
Hobby shop inventory financing is a type of business funding that gives hobby retailers the working capital needed to purchase stock such as model kits, trading cards, board games, RC vehicles, puzzles, and collectibles ahead of demand, then repay the balance over time as that inventory sells.
How is inventory financing different from a regular business loan?
A traditional term loan is typically a lump sum repaid on a fixed schedule regardless of how sales perform, while inventory financing is specifically structured around purchasing stock, and some lenders tie repayment flexibility or credit limits to the value of the inventory itself.
How much can a hobby shop qualify for?
Qualification amounts generally range from a few thousand dollars for a small independent shop to six figures for a multi-location retailer, with the exact figure depending on monthly revenue, time in business, credit profile, and how the inventory purchase supports projected sales.
Do I need good personal credit to get approved?
Good credit helps secure the lowest rates, but many alternative lenders place more weight on monthly bank deposits and overall business cash flow than on a personal credit score alone, which opens the door for newer or credit-challenged hobby shop owners.
Can a new hobby shop with less than a year in business qualify?
Some lenders require a minimum operating history of six months to a year, but newer shops with strong early sales and consistent deposit activity can sometimes qualify for smaller amounts or alternative products like a business line of credit.
What can the funds be used for besides inventory?
While the primary purpose is stocking shelves with new releases, restocks, and seasonal collections, many owners also use the same funding to cover shipping costs, pay deposits to distributors, or bridge the gap between a large wholesale purchase and the retail sales that follow.
Is it better to use a line of credit or a lump-sum loan for inventory?
A revolving line of credit tends to work well for recurring restocks of fast-moving items like trading cards or paint supplies, while a lump-sum loan or equipment-style structure fits better for a one-time bulk purchase tied to a new product line or seasonal event.
How quickly can a hobby shop get funded?
Many alternative lenders can approve and fund a qualified application within one to three business days, which matters when a limited-edition release, a seasonal rush, or a distributor discount window has a tight deadline.
Will financing inventory hurt my margins?
The cost of financing is a factor to weigh against the cost of a stockout, and many hobby shop owners find that the ability to buy in larger quantities (often at better per-unit pricing) and avoid missed sales offsets the financing expense over a full season.
What documents are typically needed to apply?
Most lenders ask for several months of business bank statements, basic business information such as an EIN and time in business, and sometimes a recent tax return, with less paperwork required for smaller funding amounts.
Can seasonal hobby shops qualify, such as holiday pop-up or back-to-school sellers?
Yes, seasonal sales patterns are common in this industry and many lenders are familiar with hobby and collectibles retail cycles, so a strong fourth-quarter or back-to-school sales history can support an approval even if revenue dips in slower months.
Does the type of hobby merchandise matter to lenders?
Lenders are generally more focused on the business's overall cash flow and sales consistency than on the specific product category, so shops carrying trading cards, miniatures, model trains, RC equipment, or tabletop games are all evaluated on similar financial criteria.
Can I use inventory financing to buy out a closing competitor's stock?
Yes, acquiring discounted bulk inventory from a closing store or liquidating distributor is a common use case, and having financing in place beforehand lets an owner move quickly when that kind of opportunity appears.
What happens if a seasonal item doesn't sell through as expected?
A reputable lender structures repayment around the business's broader cash flow rather than a single product line, so a slow-moving item does not automatically trigger a default, though it is still wise to plan realistic sell-through timelines before committing to a large purchase.
How does a hobby shop owner choose the right lender?
Compare total repayment cost, funding speed, flexibility to renew or increase a line as the business grows, and whether the lender has experience working with specialty and collectibles retailers, since that familiarity can translate into a smoother application process.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.