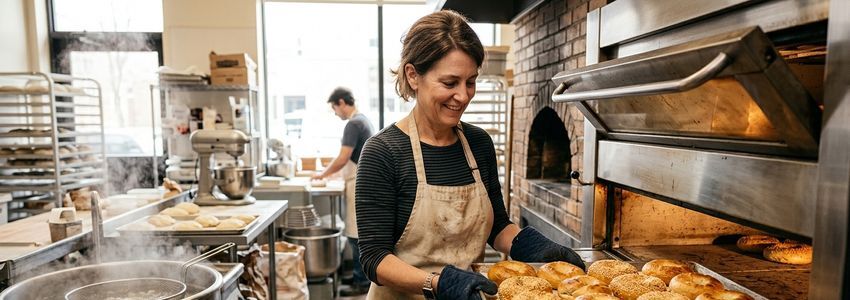
Opening or upgrading a bagel shop takes more than a great recipe. Boiling kettles, deck or rotary ovens, heavy-duty mixers, proofers, and display cases add up fast, and most of that equipment needs to be purchased before a single bagel is sold. Bagel shop equipment financing gives owners a practical way to get a fully functioning kitchen in place without draining cash reserves or delaying opening day.
In This Article
What Is Bagel Shop Equipment Financing?
Bagel shop equipment financing refers to any funding product used to purchase or lease the specialized equipment a bagel shop needs to produce and sell its product. Unlike a general restaurant kitchen, bagel production has its own equipment requirements, starting with boiling kettles or boiling rings that give bagels their signature chewy crust, followed by a deck oven or rotary rack oven that bakes them with the right steam and heat distribution.
Beyond the oven and kettle, financing typically covers spiral or planetary mixers capable of handling dense bagel dough, bagel forming machines for consistent shaping at volume, proofing boxes or retarder-proofers to control fermentation timing, walk-in coolers and freezers, display cases, slicers, and point-of-sale systems. Because much of this equipment holds real resale value, lenders are often comfortable structuring financing around it as collateral.
Whether you are opening your first location, replacing an aging oven, or building out a second shop, the right financing structure determines how quickly you can move from signed equipment quote to a fully operational production line.
Key Benefits of Financing Your Bagel Shop Equipment
- Preserve working capital. Instead of spending cash reserves on ovens and mixers, financing spreads the cost over time so you retain capital for ingredients, staffing, and marketing during your critical opening months.
- Open or expand faster. Financing lets you acquire a full equipment package at once rather than waiting to save enough cash to buy one machine at a time.
- Match payments to revenue. Many equipment financing structures are designed so your payment schedule aligns with the ramp-up period as a new location builds a steady customer base.
- Access better equipment sooner. Leasing in particular lets you upgrade to a larger rotary oven or faster mixer as volume grows, without being locked into undersized equipment.
- Protect against equipment failure. Financing a backup or replacement oven before your current one fails can prevent costly, revenue-killing downtime.
- Build business credit. Consistent, on-time payments on equipment financing can help establish or strengthen your business credit profile for future growth.
Key Stat: According to U.S. Census Bureau data, bakeries and specialty food shops are one of the fastest-growing categories of new food service establishments, with equipment and build-out costs consistently cited as the largest barrier to opening.
How Bagel Shop Equipment Financing Works
The process generally follows a straightforward path, though specifics vary by lender and the size of your equipment package.
Step 1: Get an equipment quote. Work with a restaurant equipment dealer or manufacturer to put together an itemized quote for the ovens, mixers, kettles, and other equipment you need. This quote becomes part of your financing application.
Step 2: Application and documentation. You submit basic business information, financial statements or bank statements, and the equipment quote. If you are an established shop, recent revenue history can strengthen your application considerably.
Step 3: Underwriting and structure selection. The lender reviews your application and, if approved, works with you to determine whether an equipment loan, equipment lease, working capital advance, or a combination best fits your opening timeline and cash flow.
Step 4: Funding and installation. Once terms are finalized and documentation is signed, funds are released or the equipment is procured and delivered. Your ovens, mixers, and kettles are installed, inspected, and connected, and your financing payment schedule begins on the agreed terms.
Ready to Equip Your Bagel Shop?
Get fast, flexible equipment financing from the #1 business lender in the U.S. No obligation, apply in minutes.
Apply Now →Types of Equipment You Can Finance for a Bagel Shop
Not every financing product fits every bagel shop's equipment list. Here are the main categories worth understanding before you apply.
Boiling Kettles and Boiling Rings
The boiling step is what separates a true bagel from a bread roll shaped like one. Commercial boiling kettles and rings range from compact countertop units for small shops to larger continuous boiling systems for high-volume wholesale operations, and financing can cover either.
Deck Ovens and Rotary Rack Ovens
Smaller shops often use deck ovens, which bake bagels directly on a stone hearth for a traditional crust. Higher-volume operations frequently invest in rotary rack ovens, which rotate full racks of bagels for even baking at much greater throughput. Rotary ovens cost significantly more, which is why many owners finance this piece separately from the rest of their build-out.
Mixers and Dough Equipment
Bagel dough is dense and requires a heavy-duty spiral or planetary mixer built to handle the strain. Financing can cover mixer capacity upgrades as your production volume grows beyond what a smaller mixer can reliably handle.
Proofers, Retarders, and Refrigeration
Controlling fermentation timing is critical to bagel quality and consistency. Retarder-proofers, walk-in coolers, and reach-in refrigeration units are commonly bundled into a single equipment financing package alongside the oven and mixer.
Display Cases, Slicers, and Point-of-Sale Systems
Front-of-house equipment, including bakery display cases, bagel slicers, and point-of-sale systems, rounds out most full-shop financing packages and can typically be included alongside your back-of-house kitchen equipment.
SBA-Backed Options
Depending on your business history and the scale of your build-out, SBA loan programs may also be worth exploring for larger equipment purchases, since the U.S. Small Business Administration backs a portion of the loan, which can make lenders more comfortable extending favorable terms.
Quick Guide
How Bagel Shop Equipment Financing Works, At a Glance
Work with a restaurant equipment dealer to get an itemized quote for your ovens, mixers, kettles, and proofers.
Submit your application along with the equipment quote and basic financial documentation.
Once approved, funds are released or the equipment is purchased and delivered directly to your shop.
Your equipment is installed, inspected, and ready to put into daily production.
Who This Financing Is Best For
Bagel shop equipment financing tends to be the right fit for a range of business owners, including:
- First-time bagel shop owners opening their initial location and needing to preserve cash for rent deposits, staffing, and opening inventory.
- Existing bakery or restaurant owners adding a bagel program to an existing kitchen and needing specialized boiling and baking equipment.
- Wholesale bagel producers scaling from a single retail shop into supplying grocery stores, cafes, or restaurants and needing higher-volume rotary ovens and mixers.
- Multi-location operators replicating a proven equipment setup across a second or third shop.
- Shops replacing aging equipment before an oven or mixer failure causes unplanned downtime and lost revenue.
Comparing Your Financing Options
Choosing between a loan, a lease, working capital, or an SBA-backed option depends heavily on your opening timeline, cash position, and long-term plans. The table below breaks down how the major options compare.
| Financing Option | Best For | Ownership | Typical Payment Style |
|---|---|---|---|
| Equipment Financing (Loan) | Owners planning a permanent, stable location | You own the equipment once paid off | Fixed monthly payment |
| Equipment Leasing | Owners who want to upgrade equipment or preserve cash flow | Lender or lessor owns the equipment during the term | Lower monthly payment |
| Unsecured Working Capital | Covering ingredients, staffing, or build-out gaps | Not tied to equipment ownership | Fixed term or draw-based repayment |
| SBA-Backed Loans | Larger build-outs or multi-location expansion | You own equipment purchased with loan proceeds | Fixed monthly payment, longer terms |
Many bagel shop owners end up combining structures over time, starting with an equipment loan or lease for their initial build-out, then layering in a working capital line as they scale and need to cover ingredients, staffing, or a second location's equipment.
Pro Tip: Get a detailed, itemized quote from your equipment vendor before applying for financing. Lenders move faster when they can see exactly what is being purchased, whether it is a single rotary oven or a full kitchen build-out.
How Crestmont Capital Helps Bagel Shop Owners
Crestmont Capital works with food and bakery businesses to structure financing that matches the realities of running a production-heavy kitchen, not a one-size-fits-all template. Whether you need a bakery equipment financing package for your ovens and mixers or broader food equipment financing for your full kitchen build-out, our team can help identify the right structure for your goals.
For owners who want to lower upfront costs by sourcing a rotary oven or mixer secondhand, our used equipment financing options can help. If your credit history isn't spotless, our bad credit equipment financing programs are built specifically to help business owners in that position get approved based on the strength of the equipment and business plan rather than credit score alone.
You can review all of our funding categories on our small business financing hub to see which structure lines up with where your bagel shop is today. For related reading, our guide on commercial bakery oven financing dives deeper into oven selection and financing, and our post on funding solutions for bakery companies covers broader financing options beyond equipment alone.
Turn Fresh-Baked Bagels Into a Growing Business
Crestmont Capital structures bagel shop equipment financing around your production volume, not a rigid template. See what you qualify for today.
Get Your Quote →Real-World Scenarios
Scenario 1: The First-Time Shop Owner
Rachel has spent three years perfecting her bagel recipe at farmers markets and is ready to open a storefront. She needs a boiling kettle, a deck oven, a spiral mixer, and a retarder-proofer, totaling roughly $95,000. Rather than draining her savings, she uses an equipment loan to finance the full package, keeping cash on hand for her opening month's rent and payroll.
Scenario 2: The Bakery Adding a Bagel Program
An established bakery wants to add fresh bagels to its morning lineup. Since their existing oven cannot handle the steam and heat profile bagels require, they finance a dedicated deck oven and boiling setup as a standalone equipment loan, layered on top of their existing kitchen.
Scenario 3: The Wholesale Scale-Up
A single-location bagel shop lands a wholesale contract to supply bagels to a regional grocery chain. To meet the volume, they need to replace their deck oven with a rotary rack oven and upgrade to a larger mixer, a combined investment of roughly $180,000. They use equipment leasing to keep monthly payments manageable while the wholesale revenue ramps up.
Scenario 4: The Credit-Challenged Entrepreneur
Marcus wants to open a bagel shop but has a below-average credit score from a previous business setback. Because the kitchen equipment itself serves as strong collateral, he qualifies for equipment financing through a bad credit equipment financing program, allowing him to open despite his credit history.
Scenario 5: The Emergency Oven Replacement
An established bagel shop's twelve-year-old deck oven fails unexpectedly during a busy weekend. Rather than closing for weeks while saving up cash, the owner secures fast equipment financing to replace the oven within days, minimizing lost revenue and keeping regular customers from going elsewhere.
Key Stat: According to the U.S. Small Business Administration, there are an estimated 36.2 million small businesses in the United States, and access to capital consistently ranks as one of the top barriers to launching or scaling equipment-intensive food businesses like bagel shops.
Frequently Asked Questions
Your New Oven Doesn't Have to Wait
Financing your bagel shop equipment doesn't have to slow you down. Apply now and move forward with confidence.
Apply Now →Next Steps: Getting Started With Bagel Shop Equipment Financing
Conclusion
Bagel shop equipment financing gives owners a practical way to open, upgrade, or expand a production-heavy kitchen without tying up all their available cash. Whether you need a single equipment loan for your first boiling kettle and oven, a leasing structure to stay flexible as volume grows, or working capital to support a wholesale scale-up, matching the right financing product to your specific plan makes the difference between a stalled opening and a fully running bagel operation. Crestmont Capital works with bakery and food business owners across the country to structure financing built around how their business actually operates.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.