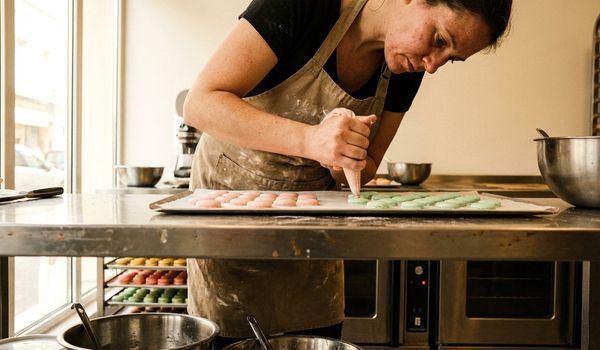
Macarons are one of the most technically demanding products in the pastry world, and building a business around them takes far more than skill with a piping bag. Between commercial deck ovens, precision mixers, climate-controlled display cases, premium almond flour, and retail build-out costs, a French macaron bakery requires serious capital before the first box is ever sold. That is exactly where macaron shop financing comes in: specialized business funding designed to help bakery owners cover equipment, inventory, build-out, marketing, and working capital without draining personal savings.
Whether you are launching a dedicated macaron boutique, adding a macaron program to an existing cafe, or scaling a farmers market operation into a brick-and-mortar shop, this guide walks through every financing option available to macaron shop owners, what lenders look for, and how to get funded fast.
In This Article
- What Is Macaron Shop Financing?
- Key Benefits of Financing Your Macaron Shop
- How Macaron Shop Financing Works
- Types of Financing for Macaron Shops
- Who Qualifies for Macaron Shop Financing?
- Comparing Your Financing Options
- How Crestmont Capital Helps Macaron Shop Owners
- Real-World Financing Scenarios
- Frequently Asked Questions
- How to Get Started
What Is Macaron Shop Financing?
Macaron shop financing is an umbrella term for the business funding products bakery owners use to start, operate, and expand a macaron-focused business. It covers everything from equipment loans for deck ovens and mixers to working capital for ingredients, packaging, payroll, and rent. Because macarons sit at the premium end of the pastry market, the economics of a macaron shop look different from a standard bakery, and the funding needs reflect that.
Consider what goes into a single macaron. The shells require finely milled almond flour, aged egg whites, and precise humidity control. The fillings call for quality chocolate, fruit purees, butter, and cream. Production demands consistency across hundreds of identical pieces per batch, which means commercial-grade mixers, convection or deck ovens with tight temperature tolerances, and refrigerated display cases that hold a narrow temperature band. Add in food-safe packaging, branding, and a retail space with the polish customers expect from a premium French pastry brand, and startup costs commonly land between $50,000 and $250,000 depending on the market and format.
Most founders do not have that kind of cash sitting in a business account, and even those who do are often better off preserving it. Financing spreads the cost of equipment, build-out, and inventory over months or years, letting the shop generate revenue while it pays down the funding. It also gives established shops a way to jump on growth opportunities, like a wholesale contract with a grocery chain or a holiday e-commerce surge, without waiting to accumulate cash.
Macaron shop financing is not one product. It is a category that includes equipment financing, term loans, business lines of credit, SBA-backed loans, and short-term working capital solutions. The right mix depends on what you are funding, how fast you need it, and where your business stands financially. The sections below break down each option in detail.
Key Benefits of Financing Your Macaron Shop
Some bakery owners view financing as a last resort, something to use only when cash runs short. Experienced operators see it differently. Used strategically, financing is a growth tool that protects your cash position and lets you move faster than competitors. Here is what the right funding makes possible:
- Preserve your cash reserves. Keeping $50,000 in the bank instead of spending it on ovens means you can absorb a slow quarter, a surprise repair, or a rent increase without panic.
- Match payments to revenue. Monthly payments on equipment or a term loan align the cost of growth with the income that growth produces, instead of front-loading every expense before opening day.
- Open sooner. Waiting to save the full cost of a build-out can delay your launch by years. Financing compresses that timeline into weeks.
- Scale for peak demand. Wedding season, the winter holidays, and Valentine's Day can multiply macaron orders. Funding lets you buy ingredients, packaging, and temporary labor ahead of the rush, then repay from the surge in sales.
- Win wholesale contracts. A grocery or cafe chain order can transform a small shop, but only if you can produce at volume. Financing the extra capacity is what makes saying yes possible.
- Build business credit. Successfully repaying financing establishes a credit history for your company, which unlocks larger facilities and better terms later.
The common thread is leverage. A macaron shop that finances wisely can produce more, sell more, and grow faster than one limited to the cash it has already earned, while keeping enough liquidity to handle the surprises every food business eventually faces.
Ready to Open Your Macaron Shop?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation - apply in minutes.
Apply Now →How Macaron Shop Financing Works
The mechanics of bakery financing are simpler than most owners expect, especially with a direct online lender. While every product has its own details, the process almost always follows the same five steps.
Step 1: Define the Funding Need
Start with a specific number and a specific purpose. "I need $78,000 to cover a deck oven, two planetary mixers, a refrigerated display case, and three months of rent" is a fundable request. "I need money for my bakery" is not. Lenders move faster and offer better terms when the use of funds is concrete, and you will make a better product choice when you know whether you are funding a long-lived asset or a short-term cash gap.
Step 2: Choose the Right Product
Equipment purchases fit equipment financing. Ongoing, uneven expenses like ingredients and payroll fit a line of credit. A major one-time project like a build-out fits a term loan or SBA loan. The next section details each type, but the rule of thumb is simple: match the length of the funding to the life of what it buys.
Step 3: Apply
Online applications with direct lenders typically take under ten minutes and ask for basic business information, a few months of bank statements, and the owner's details. Traditional banks and SBA lenders ask for far more: tax returns, financial statements, a business plan, and sometimes collateral documentation. Know which lane you are in before you start.
Step 4: Review and Approval
Direct lenders use revenue, bank activity, and credit data to make decisions quickly, often within hours and frequently the same day. Banks and SBA loans can take weeks to months. Approval amounts, rates, and terms depend on your credit profile, time in business, and revenue.
Step 5: Funding and Deployment
Once approved and accepted, funds are deposited directly into your business account, sometimes within 24 to 48 hours with a direct lender. Equipment financing may pay the vendor directly. From there, you put the capital to work and begin repayment on the agreed schedule.
Types of Financing for Macaron Shops
Not all funding works the same way, and picking the wrong product can cost you thousands in unnecessary interest or fees. Here are the six financing types macaron shop owners use most, with honest guidance on when each one makes sense.
1. Equipment Financing
Equipment financing is purpose-built for the machinery a macaron shop runs on: deck or convection ovens, planetary mixers, sheeters, blast chillers, refrigerated display cases, and espresso machines. The equipment itself serves as collateral, which makes this one of the easiest products to qualify for, even for newer businesses. Terms typically run two to seven years, matching the useful life of the equipment, and down payments are often low or zero. For a macaron shop, where a single commercial deck oven can run $8,000 to $30,000 and a full production setup can exceed $75,000, equipment financing is usually the backbone of the funding plan. Crestmont Capital offers dedicated bakery equipment financing designed around exactly these purchases.
2. Working Capital Loans
Working capital loans are short-term funds for operating expenses: ingredients, packaging, payroll, rent, utilities, and marketing. They shine when revenue is lumpy. A macaron shop that does 40% of its annual sales between November and February can use a working capital loan in October to stock up on almond flour, chocolate, gift boxes, and seasonal staff, then repay from holiday revenue. Terms are usually 6 to 18 months.
3. Business Line of Credit
A business line of credit gives you a revolving pool of funds you draw from as needed, paying interest only on what you use. For a macaron shop, it is the ideal shock absorber: cover a surprise mixer repair, a last-minute wedding order, or a slow month without reapplying each time. Once repaid, the credit becomes available again. Many established shops keep a line of credit open permanently as their financial safety net.
4. SBA Loans
Loans backed by the U.S. Small Business Administration offer some of the lowest rates and longest terms available to small businesses, with amounts reaching into the millions. The trade-off is speed and paperwork: expect a detailed application, extensive documentation, and a timeline measured in weeks or months. For a large project like buying a building or funding a multi-location expansion, the SBA loan programs are worth the wait. For time-sensitive needs, they usually are not.
5. Term Loans
A term loan delivers a lump sum you repay over a fixed period, typically one to five years, with predictable payments. It fits big, one-time investments that are not pure equipment: a retail build-out, a second location, a major rebrand, or buying out a partner. Rates are lower than short-term products for qualified borrowers.
6. Merchant Cash Advances
A merchant cash advance provides fast cash repaid as a percentage of daily card sales. It is the most expensive option on this list and should be a last resort for true emergencies, not a growth tool. If a lender's first offer is an MCA, ask what else you qualify for.
| Financing Type | Best For | Typical Amounts | Terms | Speed |
|---|---|---|---|---|
| Equipment Financing | Ovens, mixers, display cases | $5,000 - $500,000 | 2 - 7 years | 1 - 3 days |
| Working Capital Loan | Ingredients, payroll, seasonal stock-up | $10,000 - $250,000 | 6 - 18 months | 24 - 48 hours |
| Business Line of Credit | Ongoing flexibility, emergencies | $10,000 - $250,000 | Revolving | 1 - 5 days |
| SBA Loan | Real estate, major expansion | $50,000 - $5,000,000 | 7 - 25 years | Weeks to months |
| Term Loan | Build-out, second location | $25,000 - $500,000 | 1 - 5 years | 2 - 7 days |
| Merchant Cash Advance | Emergencies only | $5,000 - $250,000 | Variable (daily) | Same day - 2 days |
Key Stat: According to the U.S. Census Bureau's Economic Census, retail bakeries generate billions in annual receipts across tens of thousands of establishments, and specialty pastry continues to be one of the fastest-growing premium segments in food retail.
Who Qualifies for Macaron Shop Financing?
Qualification standards vary by product and lender, but every funder is trying to answer the same three questions: Can this business repay? Has it shown it can manage money? And does the plan make sense? Here is how the criteria typically break down.
Credit Score
For direct online lenders, a personal credit score of 600 or higher opens most doors, and 650 or better unlocks the strongest rates. Banks and SBA lenders generally want 680 or above. Lower scores do not end the conversation, especially for equipment financing, where the equipment secures the loan. Owners with challenged credit can still fund ovens and mixers, though at higher rates.
Time in Business
Six months of operating history is the common minimum for working capital and lines of credit with direct lenders, with better terms at the one-year and two-year marks. Startups are not shut out: equipment financing and some term products fund pre-revenue businesses when the owner has solid credit and industry experience.
Revenue
Most direct lenders look for at least $10,000 to $15,000 in monthly revenue, verified through business bank statements. For a macaron shop selling $3 to $4 per macaron at retail, that threshold represents a modest, established operation. Higher revenue supports larger funding amounts.
Documentation
Expect to provide three to six months of business bank statements, basic business information (EIN, entity type, ownership), and a government-issued ID. Equipment financing adds a vendor quote or invoice. SBA and bank loans require personal and business tax returns, financial statements, and often a business plan with projections.
If you are a home-based macaron maker preparing to go commercial, strengthen your application before you apply: form an LLC, open a dedicated business bank account, run all revenue through it, and gather your farmers market or wholesale sales records. Three months of clean, consistent business deposits dramatically improve your options.
By the Numbers
Macaron Shop Startup Costs - Key Figures
$75K
Typical mid-range equipment and build-out budget for a dedicated macaron shop
33.3M
Small businesses operating in the U.S., per the SBA - the engine of the economy
24-48 hrs
Funding speed with Crestmont Capital once approved - no weeks of waiting
2-7 yrs
Equipment financing terms that match the working life of your ovens and mixers
Comparing Your Financing Options
Every financing decision is a trade-off among three things: cost, speed, and ease of approval. Bank and SBA loans sit at the low-cost, slow, hard-to-qualify end. Merchant cash advances sit at the expensive, instant, easy end. Direct lenders like Crestmont Capital occupy the practical middle: reasonable rates, funding in days, and qualification standards a real-world bakery can meet.
For most macaron shops, the decision tree looks like this. If the purchase is equipment, start with equipment financing, where the asset secures the loan and rates reflect that lower risk. If the need is recurring or unpredictable, a line of credit beats repeated loan applications. If the project is large and your timeline is flexible, price out an SBA loan alongside a term loan and compare total cost. And whatever the need, compare the total repayment amount, not just the quoted rate. A lower rate with a longer term can cost more in total than a higher rate paid off quickly.
Independent reviews of the small business lending market, such as the small business loan coverage at Forbes Advisor, consistently highlight the same advice: know your numbers before you apply, borrow against a specific revenue-generating purpose, and read the full repayment schedule before signing. That discipline matters more than the specific product you choose.
How Crestmont Capital Helps Macaron Shop Owners
Crestmont Capital is the #1 business lender in the U.S., and bakery financing is core to what we do every day. We fund macaron shops, patisseries, and specialty bakeries at every stage, from first-time founders building out a retail space to established shops scaling into wholesale and e-commerce.
Our equipment financing program covers the full macaron production line: deck and convection ovens, planetary mixers, sheeters, blast chillers, display cases, and packaging equipment, with terms up to seven years and funding in as little as 24 to 48 hours. Shops that need flexibility layer on a business line of credit for ingredients, payroll, and seasonal swings. Because we are a direct lender, you work with one team from application through funding, with no broker runaround.
We have published detailed guides for adjacent bakery businesses that macaron shop owners find useful, including our dog bakery business loans guide for specialty bakeries and our breakdown of commercial convection oven financing for shops pricing out their production equipment. The same principles that fund those businesses apply directly to a French macaron operation.
What sets Crestmont apart is speed with judgment. Our advisors know bakery economics, so a request to finance a $22,000 deck oven and three months of almond flour inventory gets evaluated by someone who understands why both line items matter. Apply online in minutes, talk with a specialist the same day, and get a decision fast enough to keep your opening date.
Fund Your Bakery With the #1 Lender
Equipment, working capital, and credit lines built for bakeries. Apply in minutes, funded in days.
Apply Now →Real-World Macaron Shop Financing Scenarios
Financing makes the most sense when you see it applied to situations bakery owners actually face. These six scenarios reflect the funding requests macaron businesses bring to lenders every week.
Scenario 1: The Home Baker Goes Brick-and-Mortar
Claire spent two years selling macarons at weekend farmers markets, building a waitlist for her custom flavor boxes. She signed a lease on a 900-square-foot retail space and needed $95,000: $48,000 for a deck oven, two mixers, a blast chiller, and a display case, $32,000 for build-out, and $15,000 for opening inventory and working capital. An equipment financing package covered the machinery with a five-year term, and a short-term working capital loan covered the rest. She opened in ten weeks instead of saving for three more years.
Scenario 2: Adding a Macaron Program to an Existing Cafe
A profitable neighborhood cafe wanted to add French macarons to capture afternoon traffic and corporate gift orders. The production upgrade required a convection oven, a 20-quart mixer, refrigeration, and packaging, totaling $28,000. With two years of business history and steady revenue, the owners qualified for equipment financing at a strong rate, with the projected macaron margin covering the monthly payment within the first quarter.
Scenario 3: The Holiday E-Commerce Surge
An online macaron brand does nearly half its annual sales between mid-November and late December. In September, the owner drew $40,000 from a business line of credit to buy almond flour, chocolate, gift boxes, and temporary packing labor, and to fund a shipping upgrade. By January, holiday revenue had repaid the draw in full, and the credit line returned to standby for the next peak.
Scenario 4: Winning a Wholesale Contract
A regional grocery chain offered a macaron shop shelf space in 14 stores, but the contract required tripling production within 60 days. The shop financed a second deck oven, a larger mixer, and a walk-in refrigerator for $61,000 through equipment financing, plus a $25,000 working capital loan for ingredients and packaging. The wholesale revenue now exceeds the combined payments by a wide margin.
Scenario 5: Rebuilding After a Credit Setback
Marcus closed a previous business during a difficult year and took a hit to his personal credit. His new macaron concept was strong, but banks declined him. Because the equipment itself secures the loan, he qualified for equipment financing on a convection oven and display case despite a 590 credit score, at a higher rate with a larger down payment. Eighteen months of on-time payments rebuilt his credit profile, and he refinanced the balance at a materially better rate.
Scenario 6: Wedding Season Staffing and Inventory
A macaron shop specializing in wedding towers and favors books most of its events between May and October. Each spring, the owner draws on her line of credit to hire and train two seasonal decorators and to pre-buy specialty ingredients at volume pricing. The draws are repaid by fall, every year, and the shop never turns away a booking for lack of cash.
Pro Tip: Ingredient costs make or break macaron margins. Premium almond flour typically runs $4 to $6 per pound wholesale, and a busy shop can go through hundreds of pounds a month. When you model your funding request, budget ingredients at your projected peak volume, not your current average, so the capital lasts through your growth curve.
The pattern across all six scenarios is the same: the funding was tied to a specific, revenue-generating purpose, the product matched the asset, and the repayment schedule aligned with when the money would come back in. That alignment is what separates financing that builds a business from debt that buries one.
Frequently Asked Questions
What is macaron shop financing? +
Macaron shop financing is business funding used to start, operate, or expand a French macaron bakery. It includes equipment financing for ovens and mixers, working capital loans for ingredients and payroll, business lines of credit for flexible cash flow, term loans for build-outs, and SBA-backed loans for major expansions.
How much can a macaron shop borrow? +
Amounts range from $5,000 for a single piece of equipment to $500,000 or more for a full build-out or multi-location expansion. What you qualify for depends on revenue, time in business, credit, and the funding type. Most independent macaron shops fund between $25,000 and $150,000 for their initial equipment and opening costs.
What credit score do I need for macaron shop financing? +
Direct lenders typically look for a personal score of 600 or higher, with the best rates at 650 and above. Banks and SBA lenders usually want 680 or more. Equipment financing is the most forgiving option for lower scores because the equipment secures the loan.
Can a brand-new macaron shop get financing with no revenue history? +
Yes, though options narrow. Startups most often qualify for equipment financing, where the machinery collateralizes the loan, especially when the owner has good personal credit and industry experience. A detailed plan, vendor quotes, and evidence of pre-launch sales such as farmers market records all strengthen a startup application.
What can macaron shop financing be used for? +
Almost any legitimate business expense: ovens, mixers, and display cases; retail build-out and signage; ingredients and packaging; payroll and training; marketing and e-commerce; rent deposits; and day-to-day working capital. Equipment financing is restricted to the equipment itself, while working capital and term loans are flexible.
How fast can a macaron shop get funded? +
With a direct lender like Crestmont Capital, approval often comes the same day and funding within 24 to 48 hours. Bank loans take several weeks, and SBA loans can take one to three months from application to funding. If timing matters, say so upfront so the product matches your deadline.
Do I need collateral for a macaron shop loan? +
Not always. Equipment financing uses the equipment itself as collateral, so no additional assets are required. Unsecured working capital loans and lines of credit rely on revenue and credit strength rather than pledged assets. Larger bank and SBA loans may require collateral or a personal guarantee.
What documents do I need to apply? +
For most direct-lender products: three to six months of business bank statements, your EIN and entity details, ownership information, and a government-issued ID. Equipment financing also needs a vendor quote or invoice. SBA and bank loans add tax returns, financial statements, and a business plan.
Are SBA loans a good fit for macaron shops? +
For large, patient-money projects like buying a building or funding a major expansion, SBA loans offer excellent rates and long terms. For opening a first shop or covering a time-sensitive need, the weeks-to-months timeline and heavy documentation usually make faster products a better practical fit.
Can I finance just the macaron-making equipment? +
Absolutely. Equipment financing can cover a single mixer or a complete production line, and many shops fund exactly that: ovens, mixers, sheeters, blast chillers, and refrigerated display cases. Terms typically run two to seven years, and the equipment secures the loan.
What interest rates should I expect? +
Rates vary widely by product, credit, and business strength. Strong borrowers see equipment financing and term loan pricing comparable to single-digit or low-double-digit annual rates, while short-term and lower-credit products cost more. Always compare the total repayment amount and the monthly payment's fit against your margins, not just the headline rate.
Can I get macaron shop financing with bad credit? +
Often, yes. Equipment financing is the most accessible path because the machinery reduces the lender's risk. Expect higher rates and possibly a larger down payment. A track record of on-time payments then rebuilds your profile for better terms on the next round of funding.
Is a line of credit or a term loan better for a macaron shop? +
They solve different problems. A term loan fits a defined one-time project with a known cost, like a build-out. A line of credit fits recurring or unpredictable needs, like seasonal ingredient purchases, repairs, and slow-month coverage. Many established shops carry both: a term loan for the big project and a line of credit for everything else.
How does repayment work? +
Most equipment financing and term loans use fixed monthly payments over a set term. Working capital loans may use daily or weekly payments. Lines of credit bill interest on the outstanding balance, with the principal available again as you repay. Match the payment frequency to your cash flow: retail bakeries with daily card sales handle frequent small payments well.
Will applying for financing hurt my credit score? +
Many direct lenders, including Crestmont Capital, start with a soft credit review that does not affect your score, so you can see real options before committing. A hard inquiry may occur later in the process, which has a small, temporary impact. Responsibly repaid business financing ultimately strengthens your credit profile.
Your Macaron Shop Deserves Fast Funding
Join thousands of bakery owners who chose America's #1 business lender. Decision in hours, funding in days.
Apply Now →How to Get Started
Complete our quick application at offers.crestmontcapital.com/apply-now - takes just a few minutes.
A Crestmont Capital advisor will review your needs and match you with the right financing option for your shop.
Receive your funds and put them to work - often within days of approval.
Conclusion
A successful macaron shop runs on two ingredients: pastry skill and capital. The skill you already have. The capital is what macaron shop financing provides, whether that means equipment financing for the ovens and mixers at the heart of production, a working capital loan to ride out seasonal swings, a line of credit for flexibility, or a term loan for the build-out that turns your concept into a storefront.
The owners who thrive are the ones who treat financing as a strategic tool rather than a last resort: they match the product to the purpose, borrow against revenue-generating uses, and keep enough cash in reserve to handle surprises. With funding available in as little as 24 to 48 hours, there is no reason to let a slow savings timeline delay your opening or stall your growth.
Crestmont Capital has funded thousands of bakeries and food businesses across the country, and our advisors understand the economics of specialty pastry. If you are ready to launch, expand, or simply stabilize your macaron business, apply today and find out what your shop qualifies for.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.
Allan Garfinkle
Allan Garfinkle is the Chief Revenue Officer at Crestmont Capital, where he has spent more than a decade leading revenue strategy, business development, and operational growth. With 28 years of experience building and advising startups and small businesses, Allan has helped more than 10,000 business owners navigate financing decisions, growth opportunities, and changing economic conditions. He earned a Bachelor of Science in Economics and an MBA with a concentration in Finance from Northeastern University, as well as a Juris Doctor from New England Law, where his studies focused on contracts and business law. His writing draws on extensive practical experience in small-business lending, equipment financing, business credit, and commercial finance.