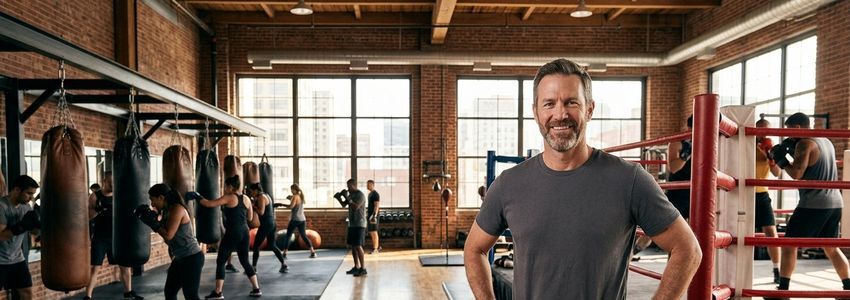
Boxing gym equipment financing lets gym owners acquire rings, heavy bags, speed bags, free weights, cardio machines, and padded flooring without paying the full cost upfront. Whether you are opening a new boxing gym, replacing worn-out equipment, or expanding into a larger space, understanding your financing options helps you move fast without draining your operating cash.
This guide covers exactly how boxing gym equipment financing works, which products fit different budgets and credit profiles, what lenders look for, and how to use funding strategically to grow a profitable gym.
In This Article
What Is Boxing Gym Equipment Financing?
Boxing gym equipment financing is a type of business funding specifically structured to help gym owners purchase or lease the physical assets a boxing facility needs to operate: rings, heavy bags, speed bags, double-end bags, free weights, resistance equipment, cardio machines, padded mats, and locker room fixtures. Instead of paying the full purchase price out of pocket, the gym spreads the cost over a fixed monthly payment, typically over 24 to 60 months.
Most equipment financing structures use the equipment itself as collateral. That means the lender has a secured interest in the ring, bags, or machines you are purchasing, which reduces the lender's risk compared to an unsecured loan. Lower risk for the lender generally translates into more competitive rates and more flexible approval criteria for the gym owner, even for newer businesses or owners with less-than-perfect credit.
Industry Snapshot: The U.S. Fitness and Recreational Sports Centers industry (NAICS 713940) includes roughly 33,000 firms, and more than 84% operate with fewer than 20 employees, according to U.S. Census Bureau Statistics of U.S. Businesses data. Combat sports and boxing-specific gyms make up a fast-growing niche within that broader category, driven by rising demand for group fitness boxing classes alongside traditional training programs.
Key Benefits of Financing Boxing Gym Equipment
Financing equipment instead of paying cash gives a gym owner more than just breathing room on a single purchase. Used strategically, it becomes a tool for steady, controlled growth.
- Preserve working capital - Keep cash on hand for rent, payroll, marketing, and unexpected expenses instead of tying it all up in a single equipment purchase.
- Open or expand faster - Get a full ring, bag setup, and strength area in place before your grand opening instead of waiting months to save enough cash.
- Access commercial-grade equipment - Finance higher-quality, more durable gear built for heavy daily use rather than settling for lower-grade equipment you can afford outright.
- Predictable monthly payments - Fixed payments make budgeting simple and protect your margins from interest rate swings common with revolving credit.
- Potential tax advantages - Financed equipment payments and depreciation may offer deductions; consult your accountant for specifics tied to your situation.
- Build business credit - Consistent, on-time payments on an equipment financing account help establish a stronger credit profile for future financing needs.
Ready to Equip Your Boxing Gym?
Get fast, flexible financing from the #1 business lender in the U.S. No obligation - apply in minutes.
Apply Now →How Boxing Gym Equipment Financing Works
The equipment financing process is designed to be faster and more accessible than a traditional bank loan, especially for established alternative lenders that specialize in small business funding.
- Identify the equipment and total cost - Get a quote from your equipment vendor for the ring, bags, weights, and any flooring or installation you need.
- Submit an application - Most applications take 10-15 minutes and ask for basic business details, monthly revenue, and time in business.
- Provide supporting documents - Lenders typically request 3-6 months of business bank statements, a vendor quote or invoice, and proof of business ownership.
- Underwriting review - The lender evaluates your cash flow, credit profile, and the equipment itself to determine your approval amount and terms.
- Review and accept your offer - You receive a term sheet detailing the payment amount, term length, and any down payment required.
- Funding and equipment delivery - Once approved, funds are released to the vendor or directly to you, and your equipment is ordered or delivered.
- Begin fixed monthly payments - Repayment starts on a set schedule, usually monthly, over the agreed term.
By the Numbers
Boxing Gym Financing - Key Statistics
33K+
Fitness and recreational sports center firms in the U.S.
84%
Operate with fewer than 20 employees
24 Hrs
Typical approval time with alternative lenders
24-60 Mo
Typical equipment financing term length
Types of Financing Available for Boxing Gym Equipment
Different financing products serve different needs. Choosing the right one depends on how much equipment you need, your current cash flow, and your credit profile.
Equipment Loans
An equipment loan provides the full purchase amount upfront, which you repay over a fixed term with the equipment serving as collateral. This is the most direct way to finance a ring, bag system, or full weight room buildout, and it typically offers the longest terms and most competitive rates of any option on this list.
Equipment Leasing
Equipment leasing lets you use the equipment for a set period in exchange for a monthly payment, often with the option to purchase, upgrade, or return the equipment at the end of the term. Leasing tends to carry lower monthly payments than a loan, which can help newer gyms manage cash flow while still accessing commercial-grade gear.
Gym-Specific Equipment Financing
Some lenders, including Crestmont Capital, offer gym equipment financing built specifically around the revenue patterns and equipment needs of fitness businesses, including boxing and combat sports facilities. These products often account for the seasonal membership cycles common in gyms.
Used Equipment Financing
If you are working with a tighter budget, used equipment financing allows you to finance pre-owned rings, bags, and machines at a lower total cost, while still spreading payments over time instead of paying cash upfront.
Bad Credit Equipment Financing
Gym owners with a lower credit score are not automatically excluded from financing. Bad credit equipment financing options exist for business owners with credit challenges, often with the equipment itself offsetting some of the added risk for the lender.
| Financing Type | Best For | Funding Speed | Typical Term |
|---|---|---|---|
| Equipment Loan | Owning equipment outright | 2-5 days | 24-60 months |
| Equipment Leasing | Lower monthly payments | 1-4 days | 12-48 months |
| Used Equipment Financing | Tighter startup budgets | 2-5 days | 12-48 months |
| Bad Credit Equipment Financing | Owners with credit challenges | 2-7 days | 12-48 months |
What Equipment Qualifies for Financing
Most tangible, durable equipment used in a boxing gym can be financed, including:
- Boxing rings and ring platforms
- Heavy bags, speed bags, and double-end bags with mounting rigs
- Free weights, dumbbells, and plate-loaded strength machines
- Cardio equipment such as treadmills, rowers, and stationary bikes
- Padded flooring, mats, and wall padding
- Locker room fixtures, benches, and storage systems
- Sound systems and timer/round-clock equipment
- Point-of-sale systems and gym management software hardware
Equipment financing is generally not available for soft costs like rent, marketing, or payroll. If your gym needs a mix of equipment and working capital for other expenses, you may want to combine equipment financing with a separate working capital product.
Who Qualifies for Boxing Gym Equipment Financing
Qualification standards vary by lender and product, but alternative lenders are generally far more accessible than traditional banks for gym owners.
Time in Business
Most lenders prefer at least 6 months of operating history, though some equipment-specific products are available to brand-new gyms since the equipment itself secures the financing.
Monthly Revenue
Lenders typically look for consistent monthly revenue, though the exact threshold depends on the loan amount and product type. Gyms with membership revenue and class fees have an advantage because recurring income is easier for lenders to evaluate.
Credit Score
Traditional banks often require a credit score of 680 or higher. Alternative lenders can work with scores as low as 500-550 for certain equipment financing products, particularly when the equipment serves as strong collateral.
Vendor Quote or Invoice
Most equipment financing applications require a formal quote or invoice from the equipment vendor showing the item, price, and specifications.
Pro Tip: Applying during a strong revenue month, such as right after a membership drive or seasonal sign-up push, can improve your approval odds and terms compared to applying during a slow month.
Financing vs. Paying Cash vs. Buying Used
Gym owners generally weigh three paths when it comes to acquiring boxing equipment: financing new equipment, paying cash outright, or buying used equipment with cash. Each has tradeoffs.
Paying cash outright avoids interest costs entirely, but it ties up capital that could otherwise cover rent, payroll, or a marketing push during your critical opening months. For many new gyms, the opportunity cost of depleting cash reserves outweighs the interest savings.
Buying used equipment with cash lowers the upfront cost but can mean inheriting worn padding, outdated weight stacks, or equipment nearing the end of its usable life, which may need replacement sooner than financed new equipment.
Financing new equipment spreads the cost over time, preserves cash flow, and gets commercial-grade gear into your gym from day one, with a predictable payment that fits into your monthly budget. For most growing gyms, financing provides the best balance of speed, equipment quality, and financial flexibility.
Build the Gym Your Members Deserve
Crestmont Capital helps boxing and fitness business owners finance rings, bags, and machines fast.
Apply Now →How Crestmont Capital Helps Boxing Gym Owners
Crestmont Capital is a direct lender rated #1 in the U.S. for small business financing. We work with boxing gyms, kickboxing studios, and combat sports facilities at every stage, from a single-room startup to a multi-location operation.
Our equipment financing and equipment leasing programs are built to move fast, with most applications reviewed within 24 hours and funding delivered in as little as 1-3 business days. We evaluate your full business picture, not just a credit score, which means we can often fund gyms that traditional banks decline.
When you need financing beyond equipment, such as working capital to cover payroll during a slow month or a line of credit for ongoing flexibility, Crestmont Capital offers those products too, all through a single streamlined application.
If you are weighing your options, our guide on boxing gym business loans covers the full range of financing available beyond equipment, and our equipment leasing for martial arts and boxing gyms resource dives deeper into leasing structures specifically.
Real-World Scenarios
Scenario 1: The New Gym Buildout
A first-time boxing gym owner in Tampa signs a lease on a 4,000 square foot space and needs a full ring, 12 heavy bags, speed bag stations, and padded flooring totaling $48,000. Rather than draining his entire startup savings, he finances the equipment over 48 months, preserving enough cash to cover three months of rent and his initial marketing push before opening day.
Scenario 2: Replacing Worn-Out Bags
A five-year-old boxing gym in Cleveland has heavy bags that are torn, lopsided, and overdue for replacement. The owner finances a $12,000 bag and rigging upgrade over 24 months rather than paying cash, keeping her reserve fund intact heading into a slower winter membership cycle.
Scenario 3: Adding a Strength Training Area
A boxing gym in Austin wants to add a dedicated strength and conditioning section to compete with full-service fitness clubs. The owner finances $35,000 in plate-loaded machines, free weights, and cardio equipment, and the added strength offering drives a 20% increase in new memberships within four months.
Scenario 4: Upgrading to a Second Ring
A growing combat sports gym in Chicago has waitlists for both its boxing and sparring classes. The owner finances a second competition-grade ring for $18,000, allowing the gym to run two simultaneous class sessions and nearly double class capacity during peak evening hours.
Scenario 5: Opening a Satellite Location
An established gym owner in Phoenix opens a second location across town and needs an entirely new equipment set, from rings to cardio machines, totaling $62,000. Financing the full buildout lets him open the second location without touching the cash flow generated by his original gym.
Scenario 6: Buying Used Equipment on Financing
A budget-conscious gym owner in Denver sources a used but well-maintained ring and a set of commercial weight machines for $22,000 total. He finances the used equipment rather than paying cash, keeping his working capital available for a grand opening promotion and signage.
Frequently Asked Questions
Get the Equipment Your Gym Needs
Apply today and see your financing options for rings, bags, weights, and more in minutes.
Apply Now →How to Get Started
Gather pricing on the ring, bags, weights, or equipment package you need to finance.
Complete our quick application at offers.crestmontcapital.com/apply-now - takes just a few minutes.
A funding specialist will match you with the right equipment financing product for your gym.
Once approved, your equipment is ordered or delivered and your gym is ready to grow.
Conclusion
Boxing gym equipment financing gives gym owners a practical way to acquire rings, bags, weights, and cardio equipment without draining the cash reserves a new or growing business needs to survive its early months. Whether you are opening your first location, replacing worn-out gear, or expanding into a larger facility, matching the right financing product to your situation keeps your gym moving forward on your timeline, not your bank account's.
Crestmont Capital works with boxing and combat sports gym owners across the country to structure fast, flexible equipment financing that fits real gym budgets and growth plans. Apply today at offers.crestmontcapital.com/apply-now and speak with a dedicated funding specialist about your boxing gym equipment financing options.
Disclaimer: The information provided in this article is for general educational purposes only and is not financial, legal, or tax advice. Funding terms, qualifications, and product availability may vary and are subject to change without notice. Crestmont Capital does not guarantee approval, rates, or specific outcomes. For personalized information about your business funding options, contact our team directly.